Complete Guide to FHA Loan Requirements in Kentucky

FHA loans are a popular choice for many first-time homebuyers in Kentucky. This is due to their flexible qualifying criteria. If you’re considering an FHA loan in the Bluegrass State, understanding the key qualifying factors is crucial. Here’s a comprehensive guide to the criteria you need to know:

  1. Credit Score Requirements:
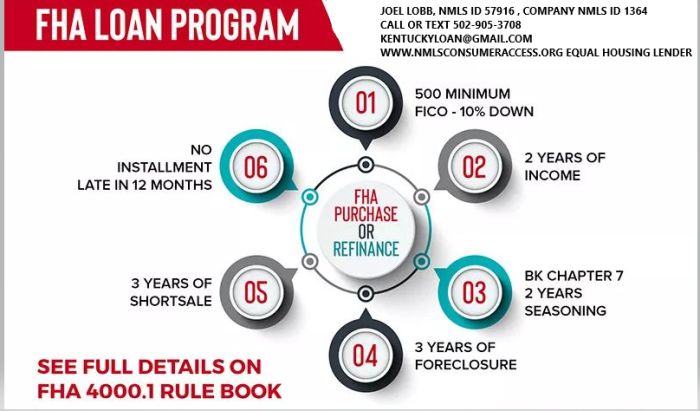
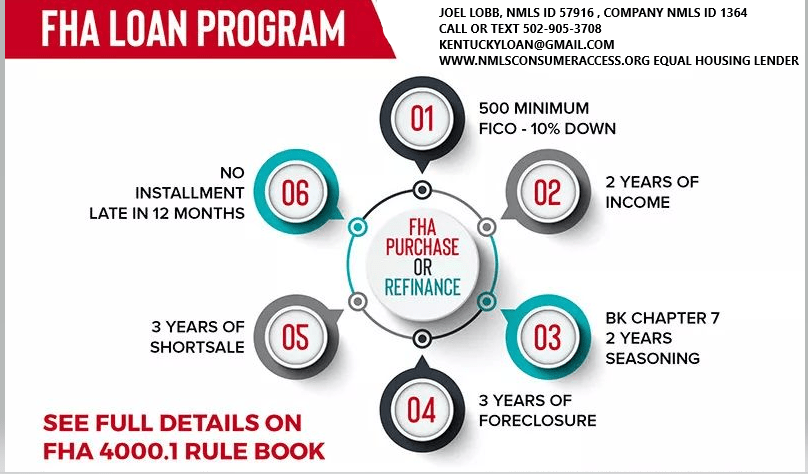
    • FHA loans are known for accommodating borrowers with lower credit scores. The minimum required credit score can vary. Typically, a credit score of 580 or higher is needed to qualify for the minimum down payment of 3.5%. Borrowers with credit scores between 500 and 579 might still qualify. They will need a higher down payment, usually around 10%.
  2. Down Payment:
    • The minimum down payment for an FHA loan in Kentucky is 3.5% of the home’s purchase price. This is advantageous for buyers who may not have substantial savings for a larger down payment, making homeownership more accessible.
  3. Work History:
    • Lenders typically look for a steady 2 year employment history when considering FHA loan applications. A consistent work history is beneficial. It is preferable to have worked with the same employer or within the same field. This helps demonstrate financial stability and the ability to repay the loan.
  4. Debt-to-Income Ratio (DTI):
    • The debt-to-income ratio is a crucial factor in mortgage approval. For FHA loans, the maximum allowable DTI ratio is typically around 40% to 45% of your gross monthly income. It can go higher up to 56% with good credit scores, a large down payment, or a shorter-term loan. Lenders may also consider higher ratios in certain cases if compensating factors are present.
  5. Bankruptcy and Foreclosure:
    • FHA loans have lenient guidelines regarding bankruptcy and foreclosure. Generally, borrowers with a past bankruptcy may qualify for an FHA loan after two years. This is possible if they have re-established good credit and demonstrated responsible financial behavior. For foreclosures, the waiting period is usually three years.
  6. Mortgage Term:
    • FHA loans offer various mortgage term options, including 15-year, 20 year, 25 year and 30-year fixed-rate loans. The choice of term depends on your financial goals and ability to manage monthly payments.
    • Occupancy: Primary residences with 1-4 units. Not for investment properties or second homes.
    • Mortgage Insurance on the loan for life of loan. Larger down payments and shorter terms will reduce the upfront mi and monthly mi premiums
    • can be used for refinances, not only for purchases.
    • No income limits nor property restrictions on where home is located
    • Can close within 30 days typically with good appraisal and title work

FHA Loan Requirements in Kentucky for Credit scores, Down payment, Debt Ratio and work history below

RequirementDetails
Credit Score– 580+: Eligible for a 3.5% down payment.
– 500-579: Requires a 10% down payment.
Down PaymentMinimum of 3.5% for qualified buyers; 10% for lower credit scores below 580 to 500 score range
Debt-to-Income Ratio (DTI)– Ideal: 45% or lower on front end ratio or housing ratio.
– Acceptable: Up to 57% with compensating factors. There are two ratios. Front end and back end with front end being maxed at 45% and the backed end ratio being 56.99% with an AUS approval. If manually underwritten, see guidelines here
Employment HistoryMust provide at least **2 years of consistent employment—College transcripts can supplement with a less than 2 year work history

Key Benefits of FHA Loans in Kentucky

  1. Low Credit Score Requirements
    • FHA loans accept borrowers with credit scores as low as 500. However, a score of 580+ qualifies you for the lowest down payment option.
  2. Low Down Payment Options
    • You can purchase a home with as little as 3.5% down if you meet credit requirements, making FHA loans more accessible than conventional loans.
  3. Competitive Interest Rates
    • FHA loans typically offer rates comparable to conventional mortgages. They may even offer lower rates. This could save you money over the life of the loan.
  4. Flexible Loan Uses
    • With an FHA 203(k) loan, you can bundle home purchase and renovation costs into a single mortgage.
  5. Assumable Loans
    • FHA loans can be transferred to a new buyer. This feature is especially valuable if you sell your home when interest rates are higher.

Understanding these qualifying criteria can help you navigate the FHA loan application process in Kentucky more effectively. Working with an experienced mortgage professional can provide valuable guidance. They offer assistance tailored to your specific financial situation and homeownership goals.

Joel Lobb  Mortgage Loan Officer

Any questions, please don’t hesitate to reach out via, text, email,  or call.  Advice is always free. 
 
One of Kentucky’s highest rated mortgage loan officers for FHA, VA, USDA, Kentucky Housing KHC and conventional mortgage loans.  
1 – 📅 Email – kentuckyloan@gmail.com 
2.  📞 Call/Text – 502-905-3708
 

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans

🌐 Websitewww.mylouisvillekentuckymortgage.com
🏢 Address911 Barret Ave., Louisville, KY 40204


Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.
Kentucky Local Home Loan Lender Services

✅ First-Time Home Buyers Welcome
✅ FHA, Rural Housing (USDA), VA, and Kentucky Housing Corporation (KHC) Loans
✅ Conventional Loan Options Available
✅ Fast Local Decision-Making
✅ Experienced Guidance Through the Home Buying Process


NMLS 57916  | Company NMLS #173846
The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approvalnor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people.
(www.nmlsconsumeraccess.org).
Kentucky First Time Homebuyers FHA, VA, USDA & Rural Housing, KHC and Fannie Mae mortgage loans
 

MINIMUM CREDIT SCORES REQUIRED FOR KENTUCKY FHA, VA, USDA MORTGAGE LOANS

  1. Kentucky FHA Loans: Kentucky FHA loans are known for their lenient credit score requirements, making them accessible to borrowers with lower credit scores. However, a minimum score of 500 to 580 is typically required, depending on the down payment.

  2. Kentucky VA Loans: VA loans offer flexible credit score requirements, while on paper VA states they don’t require a minimum score to insure the mortgage loan,  most lenders preferring a FICO score of 620 or higher. Veterans, active-duty service members, and eligible spouses can benefit from VA loan options.

  3. Kentucky USDA Loans: USDA loans are designed for rural homebuyers and require no minimum FICO score , but most lenders will want a credit score of 640 or higher. These loans offer zero down payment options for eligible properties.

  4. KHC Mortgage Loans: Kentucky Housing Corporation (KHC) mortgage loans may vary in credit score requirements depending on the lender. It’s essential to work with a knowledgeable mortgage broker like Joel Lobb to understand specific lender guidelines. KHC requires a minimum 620 credit score for FHA, VA, USDA and 660 for Conventional loan programs 


Text/call: 502-905-3708

email:
 kentuckyloan@gmail.com

http://www.mylouisvillekentuckymortgage.com/

Best Mortgage Options: Kentucky VA, FHA, USDA, and Fannie Mae

Comparing Kentucky VA loans to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky

Kentucky VA loans Compared to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky

When comparing Kentucky VA loans to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky, several factors come into play. These factors include credit score requirements, income considerations, work history, and debt ratios. They also involve how each loan type treats bankruptcy and foreclosure. Let’s delve into the benefits and differences of each loan type:

Kentucky Mortgage Credit Score Requirements:

  • Kentucky VA Loan: VA loans typically have more flexible credit score requirements compared to conventional loans. While there’s no specific minimum score set by VA , most Kentucky VA lenders often look for a credit score of 620 or higher. I can do VA loans down to a 580 credit score.
  • Kentucky USDA Loan: USDA loans also offer flexibility, with no minimum score required per USDA guidelines, but most Kentucky USDA lenders will want a 640 score or higher. I Can do Kentucky USDA loans down to a 580 credit score on a manual underwrite.
  • Kentucky FHA Loan: FHA loans are known for accommodating borrowers with lower credit scores, often accepting scores as low as 500 with a 10% down payment or 580 with a 3.5% down payment.
  • Kentucky Fannie Mae Loan: Fannie Mae loans usually require a minimum credit score of 620 or higher, although some lenders may have slightly different requirements.

Kentucky Mortgage Income and Work History:

  • Kentucky VA Loan: VA loans consider your stable income and employment history but may be more lenient if you have a history of military service or steady employment. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky USDA Loan: USDA loans often have income limits based on the area’s median income, and you need a stable income source. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky FHA Loan: FHA loans consider your income stability and work history, with guidelines that vary by lender. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky Fannie Mae Loan: Fannie Mae loans typically require a stable income and employment history, similar to conventional loans. 2 years of employment needed for loan application-minimal job gaps

Kentucky Mortgage Debt Ratio Requirements:

  • Kentucky VA Loan: VA loans generally have more lenient debt-to-income (DTI) ratio requirements, often allowing for a higher DTI compared to conventional loans. VA loans can get approved on much higher debt to income ratios vs FHA, USDA and Fannie Mae loans. 65% or higher in some situations but if manual underwrite, will want the ratios closer to 41% with good residual income for VA loan. VA loans are the only type of loans that require a residual income…FHA, Fannie Mae, USDA does not have residual income requirements
  • Kentucky USDA Loan: USDA loans have very strict DTI ratio limits, typically around 41% to 45% max on the backend ratio and 33% or less on the front end. By far the most restrictive on debt ratios vs FHA, VA, and Fannie Mae loans
  • Kentucky FHA Loan: FHA loans also have relatively flexible DTI ratio limits (56% back end ratio possible on a AUS approval), making them accessible to borrowers with moderate levels of debt. Front end ratio max 45%
  • Fannie Mae Loan: Fannie Mae loans follow standard DTI ratio guidelines similar to conventional loans. TYpically the second most restrictive on debt ratios right behind USDA loans on tighter debt to income ratio requirements, with the max back-end ratio no more than 50% –Front end ratio max 45%

Kentucky Mortgage Bankruptcy and Foreclosure Requirements:

  • Kentucky VA Loan: VA loans are more forgiving of past bankruptcy or foreclosure, often requiring a waiting period of 2 years for Chapter 7 bankruptcy and 1-2 years for foreclosure.
  • Kentucky USDA Loan: USDA loans have specific waiting periods after bankruptcy (3 years for Chapter 7) and foreclosure (3 years).
  • Kentucky FHA Loan: FHA loans have shorter waiting periods after bankruptcy (2 years for Chapter 7) and foreclosure (3 years).
  • Kentucky Fannie Mae Loan: Fannie Mae loans typically require longer waiting periods after bankruptcy (4-7 years) and foreclosure (7 years).

Advantages and Disadvantages of Kentucky VA loans, USDA, Fannie Mae and FHA:

  • Kentucky VA Loan Advantages: Zero down payment, competitive interest rates, no private mortgage insurance (PMI) requirement, lenient credit and DTI ratios, and flexible eligibility criteria for veterans and active-duty service members.
  • Kentucky VA Loan Disadvantages: Funding fee (although it can be rolled into the loan), limited to eligible veterans, service members, and some spouses.
  • Kentucky USDA Loan Advantages: Zero down payment, lower interest rates, flexible credit requirements, and available in eligible rural areas.
  • Kentucky USDA Loan Disadvantages: Limited to rural properties, income limits, and property eligibility criteria.
  • Kentucky FHA Loan Advantages: Low down payment (3.5%), flexible credit requirements, competitive interest rates, and accessible to first-time homebuyers.
  • Kentucky FHA Loan Disadvantages: Mortgage insurance premiums (MIP), stricter property standards, and limits on loan amounts.
  • Kentucky Fannie Mae Loan Advantages: Available for a wide range of properties, competitive interest rates, and options for low down payments.
  • Kentucky Fannie Mae Loan Disadvantages: Stricter credit and DTI requirements, potential for private mortgage insurance (PMI), and limited flexibility for borrowers with past financial challenges.

In summary, choosing the right loan type depends on your specific financial situation, eligibility criteria, and property location. VA loans offer excellent benefits for eligible veterans and service members, while USDA, FHA, and Fannie Mae loans provide alternatives with their own advantages and considerations.

Joel Lobb  Mortgage Loan Officer

Text/call: 502-905-3708
email: kentuckyloan@gmail.com

http://www.mylouisvillekentuckymortgage.com/

How to Qualify for an FHA Mortgage Loan in Kentucky: A Guide for First-Time Homebuyers

There are many ways to get the mortgage to buy your first home. The FHA is one option. If you are a first-time homebuyer in Kentucky, an FHA loan could be the perfect option for you. There are many flexible requirements, low down payments, and financial assistance options available. These are just a few of the many things that can help make homeownership more accessible.


What is an FHA Loan?

An FHA loan is a government-backed mortgage insured by the Federal Housing Administration (FHA). It’s designed for low-to-moderate-income borrowers, offering relaxed qualification standards compared to conventional loans. Here are the main advantages:

  • Low down payment: As little as 3.5% of the purchase price.
  • Lower credit score requirements: Minimum score of 500 with 10% down or 580 with 3.5% down.
  • Seller-paid closing costs: Sellers can contribute up to 6% of the purchase price.
  • Flexible qualifying criteria: Higher debt-to-income (DTI) ratios and options for non-occupant co-signers.

How to Qualify for a Kentucky FHA Loan

1. Credit Score Requirements

  • 580 or higher: You’ll need a minimum credit score of 580 to qualify for the 3.5% down payment option.
  • 500-579: You can still qualify with a 10% down payment, but many lenders prefer a score of 580 or higher.
  • Bankruptcy or Foreclosure:
    • Chapter 7 bankruptcy: Must be 2 years removed, with good credit since.
    • Chapter 13 bankruptcy: Can qualify after 1 year of on-time payments with trustee approval.
    • Foreclosure: Must be 3 years removed, unless there are extenuating circumstances.

2. Income and Debt-to-Income Ratio

  • DTI ratio: Typically, up to 45%% of your income can go toward your mortgage payment, and up to 56.9% can go toward all debts, depending on your credit and financial history.
  • Work history: You must have a stable employment history of at least 2 years in the same field. Recent graduates can use college transcripts as a substitute.

3. Down Payment and Gift Options

  • 3.5% down payment: This can be gifted by a family member, employer, or nonprofit organization, drawn off a retirement account like a 401k or money saved up.
  • Cash deposits: Cash cannot be used as proof of funds for your down payment—only traceable sources are allowed.

4. Property Requirements

  • Must be your primary residence. FHA loans are not for investment properties or second homes.
  • Eligible property types: Single-family homes, townhomes, condos (must be approved condo development on HUD approved list), duplexes, and some manufactured homes (if affixed to a permanent foundation).
  • Appraisal: The property must be appraised by an FHA-approved appraiser to meet HUD standards.

5. Mortgage Insurance Premium (MIP)

  • Upfront MIP: 1.75% of the loan amount, which can be rolled into the loan.
  • Annual MIP: 0.45%-1.05% of the loan amount, depending on the down payment and loan term.

Kentucky FHA Loan Limits for 2025

In all Kentucky counties, the FHA loan limit is $524,225 for a single-family home up to $1,008,300 for a four-unit property


Why Choose an FHA Loan as a Kentucky First-Time Buyer?

Pros

  • Lower credit thresholds: You can qualify with a credit score as low as 500.
  • Smaller down payments: With as little as 3.5% down with a 580 credit score
  • Seller-paid costs: The seller can pay a significant portion of your closing costs.
  • Higher debt to income ratios
  • Lenient on past bankruptcies and foreclosures.

Cons

  • Mortgage insurance: You’ll pay MIP for the life of the loan if your down payment is less than 10%.
  • Property requirements: Homes must meet specific standards, which may limit your options.
  • a lot of sellers will not accept an FHA mortgage as a offer due to property may need work to meet FHA HUD minimum standards
  • Purchase price limits and only can be used for primary residence

FHA Loans vs. Conventional Loans

Feature FHA Loan Conventional Loan
Credit Score 500+ 620+
Down Payment 3.5% (580+ credit score) 3%-20%
Mortgage Insurance Required for life of loan Can be removed at 20% equity
Debt-to-Income Ratio Up to 55% Up to 45%
Property Standards Strict requirements More flexibility

Other Kentucky First-Time Homebuyer Programs

1. Kentucky Housing Corporation (KHC)

  • Down payment assistance up to $10,000.
  • Tax credit programs for first-time buyers.

2. USDA Loans

  • Zero-down-payment option for eligible rural areas.
  • Minimum credit score of 620-640 preferred.

3. VA Loans

  • No down payment or private mortgage insurance required for eligible veterans. No minimum credit score, higher debt to income ratios allowed and no monthly mortgage insurance and low 30 year fixed rates

Need Help Getting Approved for an FHA Loan in Kentucky?

As an experienced mortgage loan officer specializing in FHA loans for Kentucky first-time homebuyers, I’m here to guide you every step of the way.

Contact Me Today:

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans

Websitewww.mylouisvillekentuckymortgage.com
Address: 911 Barret Ave., Louisville, KY 40204


Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

Equal Housing Lender

www.nmlsconsumeraccess.org

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.

5 Things I Wish I’d Knew Before Getting an FHA Mortgage

FHAdownpaymentsKentucky FHA Loan Requirements