2026 FHA Loan Requirements in Kentucky Explained

Updated August 1, 2026

This is the complete guide to qualifying for an FHA loan in Kentucky in 2026. It covers the exact credit score cutoffs, down payment rules, debt-to-income limits, loan limits, mortgage insurance costs, and the waiting periods that apply after a bankruptcy or foreclosure — everything a Kentucky buyer needs to know before applying.

Kentucky FHA Loan Requirements at a Glance (2026)

Requirement2026 Guideline
Minimum credit score (3.5% down)580
Minimum credit score (10% down)500–579
Kentucky FHA loan limit (1-unit)$541,287 — same in all 120 Kentucky counties
Debt-to-income ratioTypically up to 43–50% with compensating factors and AUS approval
Upfront mortgage insurance (UFMIP)1.75% of loan amount (can be financed)
Annual mortgage insurance (MIP)0.55% for most buyers with minimum down payment
OccupancyPrimary residence only
Waiting period after Chapter 7 bankruptcy2 years from discharge
Waiting period after foreclosure3 years

Credit Score Requirements for Kentucky FHA Loans

FHA sets two credit score tiers:

  • 580 or higher: eligible for the minimum 3.5% down payment.
  • 500 to 579: still possible, but requires 10% down.

Keep in mind these are FHA’s floors — individual lenders can add their own overlays. Many Kentucky lenders want 620, but as a broker I have access to lenders that will go down to lower scores for FHA loans. If you’ve been turned down elsewhere because of your score, it’s worth a second look.

No credit score at all? FHA allows non-traditional credit (rent, utilities, phone, insurance payment history) for buyers with no score, though underwriting is stricter.

Down Payment Rules

The minimum FHA down payment is 3.5% of the purchase price with a 580+ score. On a $250,000 Kentucky home, that’s $8,750. The entire down payment can come from:

  • Your own savings
  • Gift funds from a family member (very common for first-time buyers)
  • Approved down payment assistance, such as KHC’s up to $12,500 DAP

Sellers can also pay up to 6% of the purchase price toward your closing costs and prepaids — one of the most generous seller-concession limits of any loan program.

Debt-to-Income (DTI) Limits

FHA is the most forgiving major loan program on DTI. The standard benchmark is 31% housing / 43% total, but with an Automated Underwriting System (AUS) approval and compensating factors — reserves, residual income, minimal payment shock — Kentucky buyers are regularly approved with total DTI up to 50%, and in some cases up to 56.9% with strong compensating factors.

2026 Kentucky FHA Loan Limits

For 2026, the FHA loan limit for a single-family home is $541,287 in every Kentucky county — Kentucky has no high-cost counties, so the same limit applies in Jefferson, Fayette, Boone, and all 117 other counties. Limits are higher for 2-4 unit properties.

FHA Mortgage Insurance in 2026

Every FHA loan carries two kinds of mortgage insurance:

  • Upfront (UFMIP): 1.75% of the loan amount, almost always financed into the loan.
  • Annual (MIP): 0.55% per year for most buyers putting 3.5% down (slightly lower with 5%+ down), paid monthly.

With less than 10% down, monthly MIP stays for the life of the loan — most Kentucky buyers plan to refinance into a conventional loan once they reach 20% equity to drop it.

FHA Appraisal and Property Requirements

The home must pass an FHA appraisal, which checks both value and HUD’s minimum property standards: safe, sound, and sanitary. Common Kentucky flags include peeling paint on pre-1978 homes, missing handrails, roof issues, and non-functioning utilities. Condos must be in an FHA-approved project — see our list of FHA-approved condos in Kentucky.

FHA After Bankruptcy, Foreclosure, or Bad Credit

FHA has the shortest waiting periods of any mainstream program:

  • Chapter 7 bankruptcy: 2 years from discharge (with re-established credit)
  • Chapter 13 bankruptcy: as little as 12 months of on-time plan payments, with court approval
  • Foreclosure or deed-in-lieu: 3 years
  • Collections and charge-offs: often allowed without payoff, depending on AUS findings

Employment and Income

FHA generally wants a two-year work history, but it does not have to be with the same employer — job changes within the same field, recent graduates, and returning-to-work parents can all qualify with proper documentation. Overtime, bonus, and part-time income need a two-year history to count.

Frequently Asked Questions

What credit score do I need for an FHA loan in Kentucky?

580 for the 3.5% down payment option. Between 500 and 579 you need 10% down. Some lenders add higher overlays; a broker can shop lenders with no overlays.

What is the FHA loan limit in Kentucky for 2026?

$541,287 for a single-family home, the same in every Kentucky county.

How much are FHA closing costs in Kentucky?

Typically 3–5% of the purchase price including prepaids and escrows, but sellers can contribute up to 6% — many Kentucky FHA buyers close with little beyond their 3.5% down payment.

Can I use down payment assistance with an FHA loan?

Yes. KHC’s down payment assistance (up to $12,500) pairs with an FHA first mortgage through KHC-approved lenders, and gift funds from family are allowed for the full down payment.

How long does an FHA loan take to close in Kentucky?

Typically about 30 days from contract when your documentation is complete up front.

Get Pre-Approved for a Kentucky FHA Loan

I’ve helped Kentucky buyers with FHA loans for over 20 years, including buyers with lower credit scores, past bankruptcies, and higher debt ratios that other lenders turned away. Free pre-approvals, same-day answers.

Call or text Joel Lobb at 502-905-3708 or email kentuckyloan@gmail.com.

Joel Lobb — Mortgage Loan Officer
NMLS #57916 | EVO Mortgage, Company NMLS #1738461
Equal Housing Lender.

This information is for educational purposes only and is not a commitment to lend. All loans subject to credit approval, underwriting, property approval, and program guidelines, which can change without notice. Not affiliated with or endorsed by FHA, HUD, or any government agency.

Top Kentucky Grants for First-Time Homebuyers

Kentucky offers several grant programs

Kentucky offers several grant programs to help residents achieve their dream of homeownership. These programs provide financial assistance to eligible buyers, making the purchase of a home more affordable. Here’s an overview of the current grant options available to Kentucky homebuyers:

1. Kentucky Housing Corporation (KHC) Down Payment Assistance Program

The KHC offers up to $12,500 in down payment assistance to eligible first-time homebuyers. This program can be used in conjunction with KHC’s first mortgage loans.

Eligibility:

  • Must be a first-time homebuyer or not have owned a home in the past three years
  • Meet income and purchase price limits, which vary by county
  • Complete a homebuyer education course

2. Kentucky Affordable Housing Trust Fund

This program provides funds to create or preserve affordable housing for low-income households. While not a direct grant to homebuyers, it can help create affordable housing opportunities.

3. USDA Rural Development Grant

Although not specific to Kentucky, this federal program is available in many rural areas of the state.

Key features:

  • Provides loans and grants for low-income individuals in rural areas
  • Can be used for home purchases or repairs
  • Income limits and location restrictions apply

4. Louisville Metro Down Payment Assistance Program

Specific to Louisville, this program offers forgivable loans of up to $25,000 to help with down payment and closing costs.

Eligibility:

  • Must be a first-time homebuyer
  • Income must be at or below 80% of the area median income
  • Property must be located within Louisville Metro

5. Lexington Homeownership Assistance Program

This program, specific to Lexington, provides up to $15,000 in down payment and closing cost assistance.

Eligibility:

  • Must be a first-time homebuyer
  • Income must be at or below 80% of the area median income
  • Property must be located within Lexington-Fayette Urban County

6. Individual Development Account (IDA) Program

While not exclusive to homebuying, this program can help prospective homeowners save for a down payment.

Key features:

  • Provides matching funds for savings (typically $2 for every $1 saved)
  • Can be used for homeownership, education, or starting a small business
  • Income and asset limits apply

7. Welcome Home Grant

FeatureWelcome Home GrantKHC DPA
TypeGrant (no repayment if retained)Repayable loan (second mortgage)
Amount TypicalUp to ~$20,000*Up to $12,500
PaybackNone if stays 5+ years*Monthly payments over 15 yrs
Retention/Terms5-year deed restrictionStandard mortgage second lien
Income Limits≤80% MRB householdMRB or Secondary Market
Qualifying IncomeHousehold inclusiveDependent on mortgage product underwriter
First-Time BuyerOptionalDepends on mortgage product
AccessThrough FHLB member lendersThrough KHC-approved lenders
AvailabilitySeasonal, limitedOngoing

How to Apply

To apply for these grants, contact the respective program administrators:

  1. For KHC programs: Visit www.kyhousing.org
  2. For USDA Rural Development: Visit www.rd.usda.gov/ky
  3. For city-specific programs: Contact your local housing authority or visit the city’s official website
  4. Welcome Home Grant
  5. Program is administered through participating FHLB Cincinnati member lenders (banks and credit unions that belong to the FHLB system).
  6. Buyers must contact a participating mortgage lender early and reserve funds once the program opens (often first-come, first-served).
  7. A fully executed purchase contract and signed mortgage application are typically required to reserve funds.
  8. KHC DPA
  9. Must work with a KHC-approved lender; you cannot apply directly to KHC.
  10. The KHC-approved lender will bundle the first mortgage and the DPA second mortgage into one closing transaction.
  11. Implication:
  12. Both programs require lender participation. The Welcome Home Grant is tied to a different funding source (FHLB) than KHC’s internal DPA loan.

Be aware that grant availability and terms may change. Therefore, you should check with the program administrators for the most up-to-date information. Additionally, many of these programs require participants to complete homebuyer education courses. These courses can provide valuable information about the homebuying process.

By taking advantage of these grant programs, Kentucky residents can make their dream of homeownership more attainable. Explore all options. Consult with housing counselors or financial advisors. This will help you determine the best path to homeownership for your specific situation.

Kentucky Home Buyer Grants 2026

Down Payment Assistance & Forgivable Grants

Statewide Repayable
KHC Regular DAP

$12,500

  • Pairs with FHA, VA, USDA, or Conventional
  • Max Purchase Price: $544,232
  • 4.75% rate (15-year term)
  • No liquid asset review required
Kentucky Housing
Statewide Grant
2026 Welcome Home Program

Up to $20,000

  • Opens: April 6, 2026 (8:00 AM ET)
  • True Grant: 5-year retention requirement
  • Income limit: 80% MRB limits
  • First-come, first-served (seasonal)
Welcome Home Grant
Louisville Specific
Louisville Metro DPA

Up to $40,000

  • Forgivable after 5–15 years
  • Window: Feb 3 – March 4, 2025 (check 2026 dates)
  • Must be at/below 80% AMI
  • Property must be in Louisville Metro
Louisville DPA
Lexington Specific
Lexington Homeownership

Up to $15,000

  • REACH Inc. & Habitat for Humanity options
  • Typically 0% to 2% interest loans
  • For Fayette County residents/workers
  • Non-repayable subsidies available
Lexington Assistance
Program Structure Max Amount Best For…
Welcome Home Forgivable Grant $20,000 Low-income (below 80% MRB)
KHC DAP Repayable 2nd $12,500 Statewide buyers (up to $544k price)
USDA Rural 0% Down Loan 100% LTV Rural/Suburban properties
VA Home Loan 0% Down Loan 100% LTV Veterans & Active Duty

Joel Lobb

Mortgage Broker | EVO Mortgage
Specializing in Kentucky First-Time Buyer Programs

Call or Text: 502-905-3708
Equal Housing Equal Housing Lender
Joel Lobb NMLS #57916 | EVO Mortgage NMLS #1738461
10602 Timberwood Circle, Louisville, KY 40223. This is an advertisement. Not a commitment to lend. All programs subject to change.

Options for Bad Credit Home Buyers in Kentucky

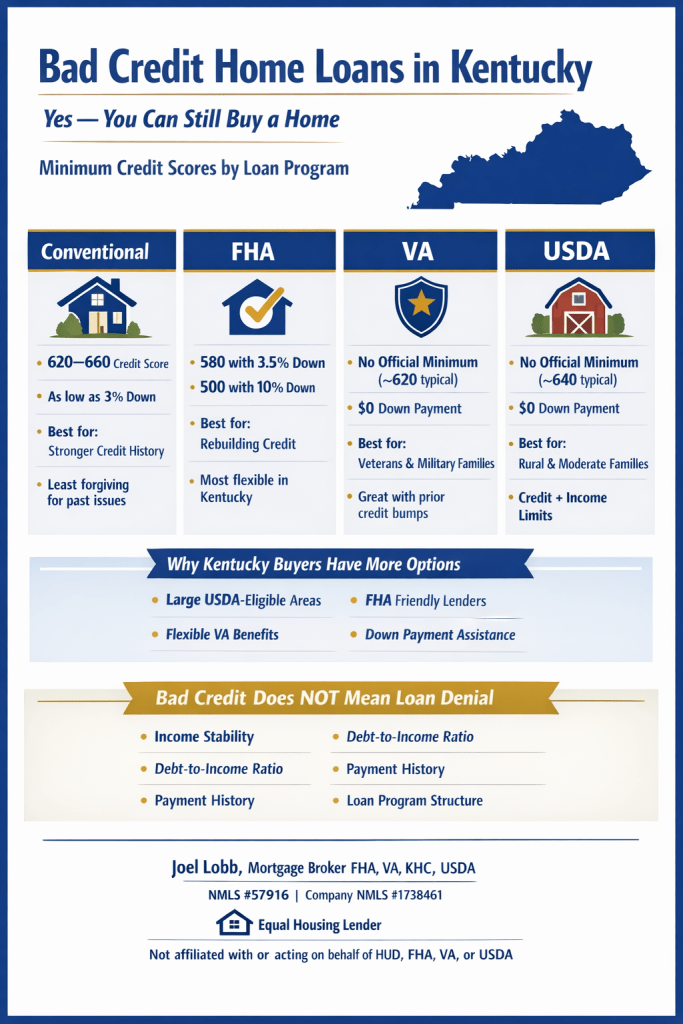
Bad Credit Home Loans in Kentucky

Many Kentucky homebuyers assume a low credit score automatically disqualifies them from buying a home. That assumption is incorrect. Several mortgage programs are specifically designed to help buyers with past credit issues qualify for financing sooner than expected.

In Kentucky, the most common loan options for buyers with bad or fair credit include FHA, VA, USDA, and select conventional loan programs. Each option has different credit score thresholds, down payment requirements, and underwriting flexibility.

Minimum Credit Score Requirements by Loan Type

Conventional loans typically require a minimum credit score between 620 and 660, depending on the program and automated underwriting results. While down payments can be as low as 3 percent, conventional loans are generally the least forgiving when it comes to recent late payments, collections, or limited credit history.

FHA loans in Kentucky are the most common solution for buyers rebuilding credit. FHA financing allows approvals with credit scores as low as 580 with only 3.5 percent down. In limited cases, buyers with scores down to 500 may qualify with a 10 percent down payment, provided the overall risk profile is strong.

Eligible service members and veterans may benefit from VA loans in Kentucky, which do not have an official minimum credit score requirement set by the agency. Most lenders look for scores around 620, but VA loans remain one of the most flexible options available, offering zero down payment and no monthly mortgage insurance.

For buyers purchasing outside major metro areas, USDA loans in Kentucky can provide 100 percent financing with competitive interest rates. While there is no official minimum credit score, most USDA lenders require a 640 score for automated approval, along with meeting income and household eligibility guidelines.

Why Kentucky Buyers Often Qualify With Lower Credit Scores

  • Large portions of Kentucky qualify for USDA rural housing loans
  • FHA loans are widely accepted by Kentucky lenders
  • VA loans provide exceptional flexibility for eligible veterans
  • Down payment assistance programs can be layered correctly with the right loan structure

What Mortgage Underwriters Actually Review

Mortgage approval is based on the full financial picture, not just the credit score. Underwriters evaluate income stability, work history, debt-to-income ratio, recent payment behavior, available assets, and how the loan is structured.

In many cases, a borrower with a lower credit score but strong income stability and clean recent payment history can be a stronger approval than someone with a higher score and excessive debt.

Bottom Line for Kentucky Homebuyers

Bad credit does not automatically mean loan denial. The right loan program, structured correctly from the start, often matters more than the credit score alone. Many Kentucky buyers qualify months or even years sooner than they expect once their options are reviewed properly.

NMLS #57916 | Company NMLS #1738461
Equal Housing Lender.
This is not a commitment to lend. All loans are subject to credit approval and program requirements.

Bad Credit Home Loans in Kentucky

Kentucky FHA Loan Credit Score Requirements

What credit score do you need to qualify for a Kentucky FHA loan? Straight talk: the Federal Housing Administration (FHA) requires a minimum credit score of 500 to be eligible. However, your final terms depend on your score and your lender’s additional requirements (known as overlays).

FHA Minimum Credit Guidelines (HUD)

  • 580 and up: Eligible for 96.5% financing — 3.5% down.
  • 500–579: Eligible for 90% financing — 10% down.
  • Under 500: Not eligible for FHA financing.

Two Things You Must Satisfy

There are two layers of approval you must clear:

  1. HUD/FHA rules: The official, baseline eligibility outlined in the HUD Handbook (FHA’s mortgage insurance rules).
  2. Lender overlays: Individual lenders can and do impose stricter standards — often requiring scores from 580 to 620 or higher.

Why Lenders Use Overlays

Lenders add overlays to manage risk. Even if you meet FHA’s minimums, lenders evaluate:

  • Debt-to-income (DTI) ratio
  • Employment and income stability
  • Source of down payment
  • Recent credit history (late payments, collections, bankruptcies)

What Score Range Gets Approved Most Often?

In practice, most FHA approvals fall in the 600–699 range. Lower-score approvals (500–579) are possible but typically carry higher down payments, stricter DTI limits, and sometimes higher rates.

Next Steps — If Your Score Is Below 580

If you’re below 580, you have tactical options:

  • Consider targeted credit repair to remove inaccurate items and lower utilization.
  • Increase your down payment to reduce lender risk.
  • Shop lenders — some local Kentucky lenders have more flexible overlays than others.
  • Explore alternative programs: VA loans, USDA loans, and KHC programs may have different criteria.

Bottom Line

Meet FHA’s minimum of 500 to be eligible, but 580 or higher is the practical target to get the best terms (3.5% down and competitive rates). Your lender’s overlay will often be the deciding factor — so work with a lender who understands Kentucky’s market and can help you position your application.

Get pre-approved — Start your free application

About the author: Joel Lobb — Mortgage Broker specializing in FHA, VA, USDA, and KHC loans across Kentucky. Learn more about Joel or contact us to schedule a consultation.

Disclaimer: This content is provided for informational purposes and is not endorsed by FHA or HUD. Lending rules change; consult a loan officer for current eligibility and program details.

Your Trusted Kentucky Mortgage Expert Joel Lobb

Your Trusted Kentucky Mortgage Expert

I specialize in assisting Kentucky First-Time Homebuyers with mortgage loans, including FHA, VA, USDA & Rural Housing, KHC (Kentucky Housing Corporation), and Fannie Mae programs. With over 20 years of experience in the mortgage industry, I’ve helped more than 1,300 Kentucky families achieve their dream of homeownership or refinance their current mortgages to secure lower payments.

Whether you’re a first-time buyer or looking to refinance, I am here to guide you through every step of the process with personalized attention, expert advice, and the best loan options available to fit your unique needs.

Down Payment Assistance:
For Kentucky first-time homebuyers, we still have down payment assistance available through KHC programs. These funds can make a huge difference in reducing upfront costs and making homeownership more accessible.

Why Work With Me?

  • Local Expertise: I know the ins and outs of Kentucky’s housing market and loan programs.
  • Fast Approvals: I offer free mortgage applications with same-day approvals to keep the process moving quickly.
  • Customized Loan Solutions: Whether you’re buying a home or refinancing, I’ll find the right loan program to fit your needs.
  • Personalized Service: I treat every client like family, ensuring you’re supported and informed throughout the process.

About My Website
Visit my website for a wealth of resources tailored to Kentucky homebuyers. You’ll find:

  • Step-by-step guides for first-time homebuyers.
  • Information on loan programs like FHA, VA, USDA, and KHC.
  • Tools to help you calculate potential payments and affordability.
  • Blog posts with tips and updates on the Kentucky housing market.
  • secure portal to start your loan application and upload documents.

Please Note: My website is not endorsed by the FHA, VA, USDA, or any government agency. It is an independent platform created to educate and assist homebuyers with expert advice and accessible tools.

Contact Me Anytime
📞 Call/Text: 502-905-3708
📧 Emailkentuckyloan@gmail.com
🌐 Websitewww.mylouisvillekentuckymortgage.com

Licensing Info: Kentucky Mortgage Loan Only

  • NMLS Personal ID: 57916


Email ThisBlogThis!Share to XShare to FacebookShare to Pinterest

Joel Lobb, Mortgage Broker FHA, VA, KHC, USDA

Why Work With Me? Local Expertise: I know the ins and outs of Kentucky’s housing market and loan programs. Fast Approvals: I offer free mortgage applications with same-day approvals to keep the process moving quickly. Customized Loan Solutions: Whether you’re buying a home or refinancing, I’ll find the right loan program to fit your needs. Personalized Service: I treat every client like family, ensuring you’re supported and informed throughout the process. About My Website Visit my website for a wealth of resources tailored to Kentucky homebuyers. You’ll find: Step-by-step guides for first-time homebuyers. Information on loan programs like FHA, VA, USDA, and KHC. Tools to help you calculate potential payments and affordability. Blog posts with tips and updates on the Kentucky housing market. A secure portal to start your loan application and upload documents. Please Note: My website is not endorsed by the FHA, VA, USDA, or any government agency. It is an independent platform created to educate and assist homebuyers with expert advice and accessible tools.

https://reviewsonmywebsite.com/js/v2/embed.js?id=8ed8fd45a2fd062872f56952886c1ec5