Kentucky FHA Loan Updates: What You Need to Know


Kentucky FHA Loan Guidelines for Credit, Down payment, income,


Kentucky FHA Loans: New Guidelines for Collections & Disputes 2026

Kentucky FHA Loans: New 2026 Guidelines

Collections, Disputes & Judgements Explained

If you’re a Kentucky first-time homebuyer with collections, disputes, or judgements on your credit report, you’re not alone—and you’re not disqualified from homeownership. The Federal Housing Administration (FHA) recently updated its lending guidelines to provide more flexibility and clarity around credit challenges.

Whether you’ve faced financial hardship, billing disputes, or collection accounts, understanding these new FHA rules could be the key to securing your Kentucky mortgage.

📋 Effective Date: All loans with case numbers assigned on or after September 9th, 2026

Understanding FHA Loans with Bad Credit, Disputes & Collections

What Are Disputed Accounts on Your Credit Report?

A disputed account appears on your credit report when you’ve officially challenged information you believe is inaccurate or incorrect. Many Kentucky borrowers don’t realize that disputed accounts can affect their ability to qualify for an FHA loan. The good news? FHA has clarified how these accounts will be evaluated going forward.

Collection Accounts & FHA Loan Qualification

Collection accounts are one of the biggest obstacles for Kentucky first-time homebuyers trying to get approved. Under the new 2026 FHA guidelines, the agency has provided specific underwriting rules that actually offer more opportunity than you might think.

Judgements on Credit Reports

If you have judgements on your credit report, FHA underwriters will evaluate them carefully, but they don’t automatically disqualify you. The new guidelines provide specific direction on how these accounts are assessed during the mortgage approval process.

New FHA Guidelines for Collections, Judgements & Disputes

Collection Account Rules: The $2,000 Threshold

Here’s how FHA Fannie Mae’s DU (Desktop Underwriter) system now handles collection accounts:

If your collection accounts total $2,000 or more cumulatively:

  1. Pay in Full — The collection debt(s) must be paid in full prior to or at closing, OR
  2. Payment Plan — You can establish a payment arrangement with the creditor, and the monthly payment is included in your debt-to-income ratio, OR
  3. 5% Payment Calculation — Include a monthly payment of 5% of the outstanding balances of each collection account in your debt-to-income ratio

If your collection accounts total less than $2,000: These may be treated more favorably during underwriting, though FHA DU will still require verification.

💡 Important for Kentucky Borrowers: If you’re married and in a community property state, collection accounts from your spouse are also counted toward this threshold—even if they’re a non-borrowing spouse.

Manual Underwriting Triggers

Certain credit situations require manual underwriting instead of automated approval. Your Kentucky FHA application will likely be manually reviewed if:

  • $1,000 or more in disputed derogatory credit accounts appears on your credit report
  • 20% or greater decline in self-employed income
  • Mortgage lates within the last 12 months

While manual underwriting takes longer, it doesn’t mean you’ll be denied. Many Kentucky borrowers with credit challenges are successfully approved through manual underwriting because a trained loan officer can explain your circumstances and compensating factors.

Payment History Requirements for FHA Approval

FHA has strict (but achievable) payment history standards:

  • All mortgage and installment loan payments must be on time within the last 12 months
  • No more than two 30-day late payments within the last 24 months
  • No derogatory credit on revolving accounts (credit cards, lines of credit) in the last 12 months
  • Collection accounts must be addressed per the guidelines above

Additional 2026 FHA Updates

New Well Water Testing Requirements

If you’re purchasing a Kentucky home with a private well, be aware of updated FHA requirements for well water testing:

Well water tests must now be:

  • Performed by a disinterested third party (not you, the seller, or anyone with a financial interest in the transaction)
  • Conducted using a method acceptable to your local health authority
  • Documented before approval

Well water testing is now required for:

  • Newly constructed properties and/or new wells
  • Properties with deficiencies in the well or water quality identified by an appraiser
  • Areas where water safety issues have been reported or are known
  • Properties near dumps, landfills, industrial sites, farms, or hazardous waste areas
  • Properties where the well and septic system are less than 100 feet apart

Overtime, Bonus & Tip Income: Simplified Calculations

Good news for Kentucky borrowers with variable income: FHA has clarified how overtime, bonuses, and tips are calculated for loan qualification.

Your overtime, bonus, or tip income will be calculated as the LESSER of:

  1. Average income earned over the previous 2 years (or the total time if earned less than 2 years), OR
  2. Average income earned over the previous year

Commission & Business Expense Requirements Removed

FHA has completely eliminated previous requirements regarding unreimbursed business expenses and commission income or automobile allowances. This aligns FHA guidelines with current IRS tax law, making it easier for self-employed borrowers and those with commission-based income to qualify.

Interested Party Contribution (IPC) Limits

Under the 2026 guidelines, mortgagees and third-party originators are now explicitly included in IPC limits. This means:

  • Lenders cannot contribute toward your down payment to artificially lower your upfront costs
  • Exception: Premium pricing credits don’t count against IPC limits—unless the lender is also acting as the seller, agent, builder, or developer

DTI Requirements & Qualification

31% Front-End / 43% Back-End FHA

31% of your gross monthly income can go toward housing costs. 43% of your gross monthly income can go toward all monthly debts.

No compensating factors required to meet these ratios, making FHA one of the most accessible loan programs for Kentucky borrowers.

Documentation You’ll Need for Underwriting

If your Kentucky FHA application requires manual underwriting due to credit challenges, be prepared to provide:

Employment & Income Documentation

  • Verbal Verification of Employment (VOE)
  • Paystubs covering the most recent 30-day period
  • W2s for the past 2 years
  • 2-year employment history

Housing & Credit History

  • Verification of Rent (VOR) or 12 months of cancelled checks if credit report doesn’t show last 12 months of housing payment history
  • Letter of Explanation (LOX) for any derogatory credit or late payments within the last 24 months

Cash Reserves

  • At least 1 month in reserves from your own funds (cannot be a gift)
  • 3 months required if purchasing a 3-4 unit property

Ready to Get Approved for a Kentucky FHA Loan?

With over 20 years of experience helping Kentucky families overcome credit challenges to achieve homeownership, I specialize in FHA loans for borrowers with collections, disputes, judgements, late payments, and more.

📧 kentuckyloan@gmail.com

📞 502-905-3708 (Call or Text)

I offer free FHA mortgage applications with same-day approvals. Let’s discuss your options today.

About Joel Lobb – Kentucky Mortgage Loan Officer

With over 20 years of mortgage industry experience, I’ve helped more than 1,300 Kentucky families secure homeownership through FHA, VA, USDA, KHC, and Fannie Mae programs.

Licensing & Credentials

  • License Type: Kentucky Mortgage Loan Only
  • NMLS Personal ID: 57916
  • Company NMLS ID: 1738461
  • Verify License: www.nmlsconsumeraccess.org

Kentucky FHA Loan Programs Available

  • ✓ Collections & Disputed Accounts
  • ✓ Judgements
  • ✓ Bad Credit & Low Credit Scores
  • ✓ Late Payments (within 24 months)
  • ✓ Self-Employed & Variable Income
  • ✓ Down Payment Assistance (KHC Programs)
  • ✓ First-Time Homebuyer Programs
FHA Collections & Disputes Infographic * { margin: 0; padding: 0; box-sizing: border-box; } body { font-family: ‘Segoe UI’, Tahoma, Geneva, Verdana, sans-serif; background: linear-gradient(135deg, #f5f7fa 0%, #c3cfe2 100%); padding: 20px; display: flex; justify-content: center; align-items: center; min-height: 100vh; } .infographic { background: white; width: 100%; max-width: 900px; border-radius: 15px; box-shadow: 0 10px 40px rgba(0,0,0,0.15); overflow: hidden; } .header { background: linear-gradient(135deg, #1e3c72 0%, #2a5298 100%); color: white; padding: 40px 30px; text-align: center; } .header h1 { font-size: 2.2em; margin-bottom: 10px; font-weight: 700; } .header p { font-size: 1.1em; opacity: 0.95; } .content { padding: 40px 30px; } .section { margin-bottom: 50px; } .section-title { font-size: 1.6em; color: #1e3c72; margin-bottom: 25px; padding-bottom: 15px; border-bottom: 3px solid #2a5298; display: flex; align-items: center; } .section-title .icon { font-size: 1.8em; margin-right: 15px; } .collection-flow { display: grid; grid-template-columns: 1fr 1fr 1fr; gap: 20px; margin-bottom: 30px; } .flow-box { background: linear-gradient(135deg, #667eea 0%, #764ba2 100%); color: white; padding: 25px; border-radius: 10px; text-align: center; position: relative; } .flow-box.option { background: linear-gradient(135deg, #f093fb 0%, #f5576c 100%); } .flow-box h3 { font-size: 1.3em; margin-bottom: 15px; } .flow-box p { font-size: 0.95em; line-height: 1.6; } .flow-box .amount { font-size: 1.4em; font-weight: bold; margin: 15px 0; color: #fff; } .flow-box .arrow { position: absolute; right: -25px; top: 50%; transform: translateY(-50%); font-size: 1.8em; color: #2a5298; } .flow-box:last-child .arrow { display: none; } @media (max-width: 768px) { .collection-flow { grid-template-columns: 1fr; } .flow-box .arrow { display: none; } } .options-grid { display: grid; grid-template-columns: 1fr 1fr 1fr; gap: 15px; margin-top: 25px; } .option-card { background: linear-gradient(135deg, #ffeaa7 0%, #fdcb6e 100%); padding: 20px; border-radius: 8px; border-left: 5px solid #e17055; text-align: center; } .option-card h4 { color: #d63031; margin-bottom: 10px; font-size: 1.1em; } .option-card p { color: #333; font-size: 0.9em; line-height: 1.5; } .option-card .number { font-size: 1.5em; color: #d63031; font-weight: bold; margin-bottom: 10px; } @media (max-width: 768px) { .options-grid { grid-template-columns: 1fr; } } .disputed-section { background: #fff3cd; border-left: 5px solid #ff9800; padding: 25px; border-radius: 8px; margin-bottom: 30px; } .disputed-section h3 { color: #856404; margin-bottom: 15px; font-size: 1.3em; } .disputed-section p { color: #333; line-height: 1.7; margin-bottom: 15px; } .trigger-list { display: grid; grid-template-columns: 1fr 1fr; gap: 20px; margin-top: 25px; } .trigger-item { background: #fff; border: 2px solid #e74c3c; border-radius: 8px; padding: 20px; text-align: center; } .trigger-item .icon { font-size: 2em; margin-bottom: 10px; color: #e74c3c; } .trigger-item h4 { color: #e74c3c; margin-bottom: 8px; font-size: 1em; } .trigger-item p { color: #555; font-size: 0.9em; } .payment-history { background: #e8f5e9; border: 2px solid #4caf50; border-radius: 8px; padding: 25px; margin-top: 25px; } .payment-history h3 { color: #2e7d32; margin-bottom: 20px; font-size: 1.3em; } .requirement-item { display: flex; align-items: flex-start; margin-bottom: 15px; padding-bottom: 15px; border-bottom: 1px solid #c8e6c9; } .requirement-item:last-child { border-bottom: none; margin-bottom: 0; padding-bottom: 0; } .requirement-item .check { color: #4caf50; font-weight: bold; margin-right: 15px; font-size: 1.3em; flex-shrink: 0; } .requirement-item p { color: #333; line-height: 1.6; } .dti-box { background: linear-gradient(135deg, #3498db 0%, #2980b9 100%); color: white; padding: 30px; border-radius: 10px; text-align: center; margin-top: 25px; } .dti-box h3 { margin-bottom: 20px; font-size: 1.4em; } .dti-values { display: grid; grid-template-columns: 1fr 1fr; gap: 20px; } .dti-item { background: rgba(255,255,255,0.15); padding: 15px; border-radius: 8px; } .dti-item .label { font-size: 0.9em; opacity: 0.9; } .dti-item .value { font-size: 2em; font-weight: bold; margin-top: 5px; } .footer { background: #f8f9fa; padding: 25px; text-align: center; border-top: 2px solid #e0e0e0; color: #666; } .footer p { margin-bottom: 10px; font-size: 0.95em; } .footer strong { color: #2a5298; } .key-takeaway { background: linear-gradient(135deg, #667eea 0%, #764ba2 100%); color: white; padding: 20px; border-radius: 8px; text-align: center; margin-top: 30px; font-size: 1.1em; font-weight: 600; }

FHA Loans & Collections

Your Guide to Disputed Accounts & Collections 2026

💰 Collection Accounts: The $2,000 Threshold

Step 1: Check Total

Add up all collection accounts on your credit report

Step 2: Compare

$2,000?

Is your total more or less?

Step 3: Choose Path

Select your payment strategy

1

Pay in Full

Pay before or at closing

2

Payment Plan

Monthly payment included in DTI

3

5% Calculation

5% of balance added to DTI

Disputed Accounts

What Triggers Manual Underwriting?

If you have $1,000 or more in disputed derogatory accounts, your application will be reviewed by a human underwriter instead of automated approval. This isn’t bad news—it means your circumstances can be explained!

⚠️

$1,000+ Disputes

Disputed derogatory accounts trigger manual review

📉

Self-Employment Drop

20% or greater income decline

Recent Mortgage Lates

Late payments in the last 12 months

Good News

Manual review = opportunity to explain!

Payment History Requirements

What FHA Requires

All mortgage & installment payments on time in the last 12 months

No more than 2 late payments (30 days) within the last 24 months

No derogatory credit on revolving accounts (credit cards) in the last 12 months

Collections must be addressed per the $2,000 threshold rules

📊 FHA Debt-to-Income Ratios

Your Maximum DTI Limits

Front-End Ratio
31%

Housing costs only

Back-End Ratio
43%

All monthly debts

No compensating factors required to meet these ratios

💡 Bad credit ≠ No approval. Collections and disputes can be managed with the right strategy!

Gift Funds for a Kentucky FHA Mortgage

Getting Gift Funds for your down payment on a Kentucky FHA Mortgage. 

Gift Funds for a Mortgage Loan Approval.

What is the Great Way to do it?

To avoid getting turn down for your Kentucky FHA mortgage loan if you are getting a gift from your mom, dad or another family member, please follow these rules:

The source of the down payment must always show Kentucky FHA gift funds and their source (usually a relative). It cannot be a personal loan or cash.

Common Gift Fund Issues:

Scenario 1 – only gift funds being used in the transaction
Gift amount: $5,000

Common submission problem:

  • Source of down payment submitted as “checking and savings account.”
  • Asset submitted as “checking account” with the financial institution as “Gift from Relative.”

Correct submission practice:

  • Source of a down payment should be submitted as an “FHA Gift from a relative for $5,000”
  • If funds are not yet in the bank account, DU should be submitted as miscellaneous assets, “Gift for $5,000”

Scenario 2 – (gift funds and borrower’s own funds being used in transaction)
Gift amount: $5,000

Common submission problem:

  • Checking account has $7,000 in total – including the gift.
  • Source of down payment submitted as “checking and savings account.”
  • Asset submitted as “checking account”:
    • Financial institution with $7,000 AND
    • Miscellaneous asset, “Gift from relative of $5,000”
  • When ran this way, the gift is put through twice and assets are overstated by $5,000.

Correct submission practice:

  • Source of down payment should be submitted as an “FHA Gift from relative $5000.”
  • Since the gift fund is already in the Borrower’s bank account, DU should be submitted as “checking or savings” in ABC account in the amount of $7,000. DU will recognize that $5,000 of the $7,000 in the account is from a gift. 
Scenario 3 – (gift funds and borrower’s own funds being used in transaction)
Gift amount: $5,000Correct submission practice:
  • Checking account currently has $2,000. The $5,000 gift will be wired to the title company.
  • Source of down payment submitted as “checking and savings account.”
  • Asset submitted as “checking account:”
    • The financial institution with $7,000, AND
    • Miscellaneous asset, “Gift from relative of $5,000.”

Correct submission practice:

  • Source of down payment should be run as “FHA Gift from relative $5,000.”
  • Since gift funds will be provided to the title company and not the borrower:
    • DU should be submitted as checking or savings in ABC account in the amount of $2,000, AND
    • Miscellaneous assets, “gift funds as $5,000.”


bb501-gotquestion2b252812529


Understanding FHA’s Identity of Interest Transactions

Does FHA Restrict down payment requirements on Identity of Interest Transactions?

The 85 percent maximum LTV restriction does not apply for Kentucky FHA Loans in regards to FHA Identity-of-Interest transactions under the following circumstances:

👇👇👇

FAMILY MEMBER TRANSACTIONS•  the principal residence of another family member; or  a property owned by another family member in which the borrower has been a tenant for at least six months immediately predating the sales contract. A lease or other written evidence to verify occupancy is required.

BUILDER’S EMPLOYEE PURCHASE• An employee of a builder, who is not a family member, purchases one of the builder’s new houses or models as a principal residence.

CORPORATE TRANSFER • A corporation transfers an employee to another location, purchases the employee’s house, and sells the house to another employee.

TENANT PURCHASE• the current tenant purchases the property where the tenant has rented the property for at least six months immediately predating the sales contract. A lease or other written evidence to verify occupancy is required.

Source: FHA Handbook 4000.1

What You Need To Know About Identity Of Interest Transactions


Text/call 502-905-3708
kentuckyloan@gmail.com

http://www.nmlsconsumeraccess.org/
If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.
Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/
— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency

Kentucky FHA Homes: Current Listings & Bidding Info

Kentucky HUD homes (FHA $100 down candidate list)

These HUD-owned listings are currently showing bid activity. All homes are sold as-is and bidding must be submitted through a HUD-registered selling broker.

Tip: HUD HomeStore lets you search by “State, City, ZIP, Address or Case #.”
(Open HUDHomeStore)

110 Glades St, Berea, KY 40403 (Madison County)

$273,700 · 4 beds · 3 baths · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-482211
Status highlights
Price reduced

761 River Rd, Edmonton, KY 42129 (Metcalfe County)

$144,000 · 5 beds · 3 baths · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-712269
Status highlights
Price reduced

159 Mount Sterling Rd, Paris, KY 40361 (Bourbon County)

$142,000 · 2 beds · 1 bath · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-736010
Status highlights
Price reduced

45 Lee Dr, Beaver Dam, KY 42320 (Ohio County)

$140,000 · 3 beds · 2 baths · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-739539
Status highlights

1311 E Main Street, Horse Cave, KY 42749 (Hart County)

$120,000 · 3 beds · 2 baths · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-711292
Status highlights

509 Ponder Br, Frenchburg, KY 40322 (Menifee County)

$114,400 · 4 beds · 2 baths · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-727188
Status highlights
Price reduced

816 E 15th St, Owensboro, KY 42303 (Daviess County)

$90,000 · 2 beds · 1 bath · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-692830
Status highlights

410 Chapel St, Falmouth, KY 41040 (Pendleton County)

$90,000 · 2 beds · 2 baths · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-696999
Status highlights

511 E Bellville St, Marion, KY 42064 (Crittenden County)

$68,000 · 2 beds · 1 bath · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-720151
Status highlights
Price reduced

707 N Levisa Rd, Mouthcard, KY 41548 (Pike County)

$40,000 · 3 beds · 1.1 baths · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-563350
Status highlights
New listing

214 Silk Stocking Loop, Van Lear, KY 41265 (Johnson County)

$26,520 · 3 beds · 2 baths · Listing period: Extended · Bids open: 01/27/2026

HUD case #
201-330704
Status highlights
Hard to sell

208 North Lakeshore Drive, Owenton, KY 40359 (Owen County)

$210,000 · 3 beds · 1 bath · Listing period: Exclusive · Bids open: 01/27/2026

HUD case #
201-659268
Status highlights

3265 Chaumount Rd, Park City, KY 42160 (Edmonson County)

$200,000 · 4 beds · 2 baths · Listing period: Exclusive · Bids open: 02/03/2026

HUD case #
201-748894
Status highlights
New listing

6904 Holly Lake Dr, Louisville, KY 40291 (Jefferson County)

$165,000 · 2 beds · 1 bath · Listing period: Exclusive · Bids open: 01/27/2026

HUD case #
201-744748
Status highlights

1438 N Old Stilesville Rd, Eubank, KY 42567 (Pulaski County)

$120,000 · 3 beds · 2 baths · Listing period: Exclusive · Bids open: 01/27/2026

HUD case #
201-727348
Status highlights

Kentucky Mortgage Broker Offering FHA, VA, USDA, Conventional, and KHC Down Payment Assistance Home Loans's avatarLouisville Kentucky Mortgage Loans

Search Results for HUD Homes in KY

13 listings found
ListGallery
Save SearchEmail SearchView MapExport toDisplay: 
5
10
20
Property CaseAddressPriceStatusBedBathListing PeriodBid Open DateDetails 
201-39890485 Tomahawk Dr
Louisa, KY, 41230
Lawrence County
$146,50032.00Extended 01/31/2022View Street
Map it
Email Info
201-4113676893 Ky 57
Vanceburg, KY, 41179
Lewis County
$53,00042.00Exclusive 02/04/2022View Street
Map it
Email Info
201-44332299 Falls Br
Belfry, KY, 41514
Pike County
$88,20032.00Extended 01/31/2022View Street
Map it
Email Info
201-4631047916 Owenton Rd
Frankfort, KY, 40601
Franklin County
$130,00032.00Extended 01/31/2022View Street
Map it
Email Info
201-4923659655 Marshall Rd
Ryland Hght, KY, 41015
Kenton County
$137,70021.00Extended 01/31/2022View Street
Map it
Email Info
201-5602351280 Alton Rd
Lawrenceburg, KY, 40342

View original post 164 more words

How long does it take to close a Kentucky Rural Housing Loan in Kentucky?

Current Underwriting Turn Times on Rural Housing USDA Loans in Kentucky
Kentucky Rural Housing USDA Turn Times

Are you interested in knowing the current status of USDA’s turn times? USDA provides this information on their website.

Kentucky USDA loans are not slow — that’s a myth.

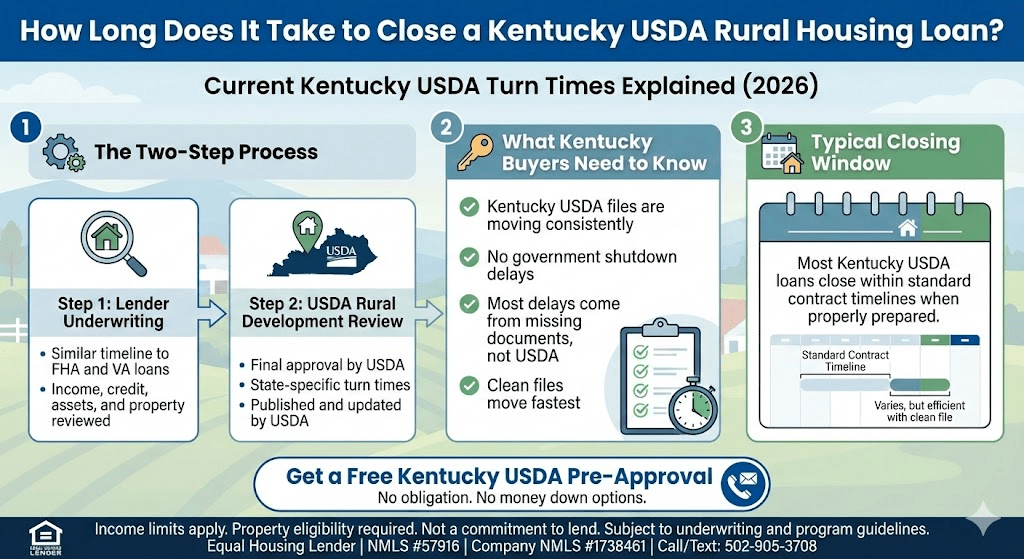
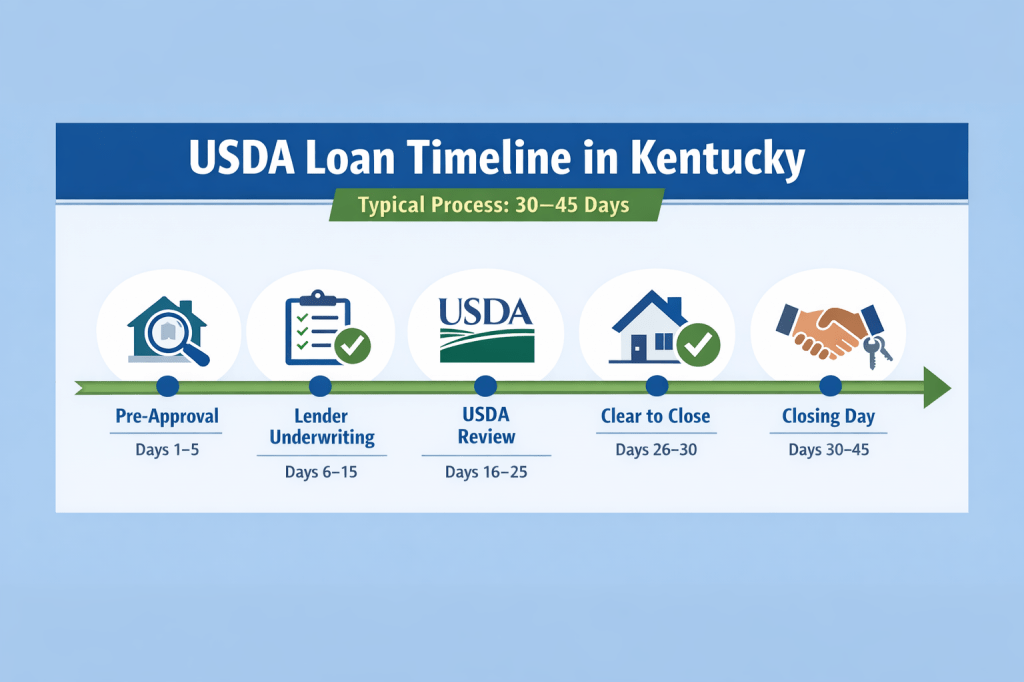
A USDA Rural Housing loan has two approvals: lender underwriting and final USDA review. In Kentucky, both are moving steadily, and most loans are closing within normal contract timelines.

The real key? A clean, well-documented file from the start.

If you’re looking for a true no-down-payment option in eligible rural areas and want realistic timelines (not guesswork), start with a proper USDA pre-approval.

How long does it take to close a Kentucky USDA Rural Housing loan?

Last updated: January 25, 2026
Serving Kentucky homebuyers with USDA Rural Housing, FHA, VA, Conventional, and KHC Down Payment Assistance.

If you’re considering a USDA Rural Housing loan in Kentucky, your timeline depends on two underwriting stages. The lender underwriting phase is usually similar to FHA and VA timelines. The second phase is the final review completed by USDA Rural Development, and that is the step most buyers worry about.

Current Kentucky USDA turn times

USDA publishes state-by-state underwriting turn time updates on their official website. If you want the current Kentucky Rural Development review time, that public update is the most reliable benchmark.

Tip: Ask your lender what date your file will be submitted to Rural Development and whether the submission package is “clean” (complete). Clean packages move faster.

The two-step USDA approval process

Step 1: Lender underwriting

  • Income, assets, credit, and property reviewed
  • Typically tracks closely with FHA and VA underwriting speed
  • Most delays come from missing documentation or unclear income

Step 2: USDA Rural Development review

  • Final USDA approval after lender underwriting
  • State-specific turn times (Kentucky is published by USDA)
  • Turn times can move up or down based on volume

What affects closing time the most?

  • Document completeness at submission (the biggest factor)
  • Income type (hourly overtime, commission, self-employment, seasonal work)
  • Eligibility items (household income calculation, property eligibility, appraisal/repairs)
  • How quickly conditions are cleared once issued

Bottom line for Kentucky homebuyers

In today’s market, Kentucky USDA loans are moving consistently. The shutdown-era horror stories are not the norm. When the file is packaged correctly and conditions are handled fast, many USDA contracts can close within standard purchase timelines.

Get a free Kentucky USDA pre-approval

Want a realistic timeline based on your income, county, and property? Start with a proper pre-approval and a clean documentation plan.

Call/Text: 502-905-3708  | 
Email: kentuckyloan@gmail.com

FAQ: Kentucky USDA Rural Housing turn times

Are USDA loans slow in Kentucky?

Not inherently. The timeline depends on file quality, appraisal/repairs, and the current Rural Development review queue. A clean, complete submission is the best way to avoid delays.

What can I do to speed up my USDA closing?

Provide all documents upfront, respond to conditions quickly, and work with a lender who packages Rural Development submissions correctly the first time.

Does USDA publish Kentucky turn times?

Yes. USDA posts state-by-state underwriting/processing turn time information on their official site. That update is the best reference for what Kentucky is doing right now.

Income limits apply. Property eligibility required. Not a commitment to lend. Subject to underwriting and program guidelines.
Equal Housing Lender | NMLS #57916 | Company NMLS #1738461


<!–

How long does it take to close a Kentucky USDA Rural Housing loan infographic
Infographic: Kentucky USDA Rural Housing turn times explained (2026).

–>

{
“@context”: “https://schema.org&#8221;,
“@graph”: [
{
“@type”: “Article”,
“headline”: “How long does it take to close a Kentucky USDA Rural Housing loan?”,
“description”: “Kentucky USDA Rural Housing loan timelines explained, including the two-step underwriting process and what affects closing speed.”,
“inLanguage”: “en-US”,
“dateModified”: “2026-01-25”,
“datePublished”: “2026-01-25”,
“author”: {
“@type”: “Person”,
“name”: “Joel Lobb”
},
“publisher”: {
“@type”: “Organization”,
“name”: “Joel Lobb, Mortgage Broker FHA, VA, KHC, USDA”
}
},
{
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Are USDA loans slow in Kentucky?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Not inherently. The timeline depends on file quality, appraisal and repairs, and the current Rural Development review queue. A clean, complete submission is the best way to avoid delays.”
}
},
{
“@type”: “Question”,
“name”: “What can I do to speed up my USDA closing?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Provide all documents upfront, respond to conditions quickly, and work with a lender who packages Rural Development submissions correctly the first time.”
}
},
{
“@type”: “Question”,
“name”: “Does USDA publish Kentucky turn times?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Yes. USDA posts state-by-state turn time information on their official website. That update is the best reference for what Kentucky is doing right now.”
}
}
]
},
{
“@type”: “LocalBusiness”,
“name”: “Joel Lobb, Mortgage Broker FHA, VA, KHC, USDA”,
“telephone”: “+1-502-905-3708”,
“email”: “kentuckyloan@gmail.com”,
“areaServed”: “Kentucky”,
“serviceType”: [
“USDA Rural Housing Loans”,
“FHA Loans”,
“VA Loans”,
“Conventional Loans”,
“KHC Down Payment Assistance”
]
}
]
}

Kentucky Mortgage Broker Offering FHA, VA, USDA, Conventional, and KHC Down Payment Assistance Home Loans's avatarLouisville Kentucky Mortgage Loans

Current Underwriting Turn Times on Rural Housing USDA Loans in Kentucky

Kentucky Rural Housing USDA Turn Times

Are you interested in knowing the current status of USDA’s turn times? USDA provides this information on their website.

View original post