
Getting a Mortgage in Chapter 13 Bankruptcy: Kentucky Guide

Home › Bankruptcy Mortgage Help › Can You Get a Kentucky Mortgage While in Chapter 13 Bankruptcy?

Can You Get a Kentucky Mortgage While in Chapter 13 Bankruptcy?

Yes — you can get a Kentucky mortgage while in an active Chapter 13 bankruptcy, but this is a narrow approval lane. Most borrowers do not qualify unless they have at least 12 months of on-time payments, court approval, and a debt-to-income ratio that still works with the bankruptcy payment included.

Need a real answer instead of a guess?
Call or text 502-905-3708 for a free Kentucky mortgage review.

What Are the Requirements for a Kentucky Mortgage During Chapter 13?

1) 12 Months of On-Time Chapter 13 Payments

You generally must show at least 12 consecutive months of on-time Chapter 13 payments before applying for a mortgage. If you are only at month 10 or 11, most lenders will not move forward.

2) Court Approval Is Required

You usually need written permission from the bankruptcy court before taking on a new mortgage. Your bankruptcy attorney typically files a motion to incur debt or motion to borrow, and the court reviews whether the proposed payment fits your budget.

3) You Still Must Qualify Financially

Chapter 13 does not override standard underwriting. You still need acceptable income, employment stability, credit, assets, and debt-to-income ratios. The Chapter 13 plan payment must be counted in your total debt ratio.

Debt-to-Income Ratio Guidelines

Most manually underwritten Chapter 13 mortgage files aim for these general benchmarks:

  • Housing ratio around 31% of gross monthly income
  • Total debt ratio around 43% of gross monthly income

Some files can stretch higher with strong compensating factors, but if the new house payment plus your bankruptcy payment and other debts push the numbers too far, the loan usually will not work.

Credit Score Requirements

Mortgage lenders do not use the scores shown on most consumer apps. They use mortgage-specific FICO scores from Experian, Equifax, and TransUnion, then qualify you off the middle score.

  • 620 and above: strongest approval range
  • 580 to 619: possible, but tougher
  • Below 580: usually not realistic right now

If your mortgage scores are under 620, it may make more sense to improve the file first rather than force a weak approval attempt.

Best Loan Programs for Kentucky Borrowers in Chapter 13

FHA Loans

FHA loans are the most common option for borrowers in an active Chapter 13 bankruptcy because they allow more flexible credit guidelines and manual underwriting in many cases.

  • 3.5% down payment minimum
  • Flexible credit compared to conventional loans
  • Often the best fit for credit rebuilding buyers

Read the full Kentucky FHA loan guide

USDA Loans

USDA loans can offer 100% financing, but they are more restrictive. The property must be in an eligible rural area and household income limits apply. In practice, these files usually work best when the borrower has stronger credit.

  • No down payment required
  • Property must be in an eligible USDA area
  • Household income limits apply
  • Stronger credit usually improves odds

Read the Kentucky USDA loan guide

VA Loans

If you are an eligible veteran or active-duty borrower, a VA loan may be an option during Chapter 13. The biggest advantages are no down payment and no monthly mortgage insurance, but the file still must be manually underwritten when required.

  • Zero down payment for eligible borrowers
  • No monthly mortgage insurance
  • Strong option for qualified veterans

Read the Kentucky VA loan guide

KHC Down Payment Assistance

Kentucky Housing Corporation programs may help eligible borrowers with down payment and closing cost assistance, depending on income, credit profile, and the first mortgage program being used.

  • Can help reduce cash to close
  • Often paired with FHA, VA, USDA, or conventional first mortgages
  • Program terms depend on borrower eligibility and current offerings

Read the Kentucky KHC mortgage guide

Why Most Chapter 13 Mortgage Files Get Denied

  • Applying before 12 full months of Chapter 13 payments are complete
  • Late bankruptcy plan payments
  • Using consumer credit scores instead of mortgage scores
  • Forgetting to include the Chapter 13 payment in debt-to-income calculations
  • Trying to get zero down financing with weak credit and no reserves
  • Not getting court approval before moving forward

How to Improve Your Approval Odds

  • Make every Chapter 13 payment on time
  • Keep credit card balances low
  • Avoid overdrafts and negative bank balances
  • Do not open new credit accounts
  • Build savings for down payment, closing costs, and reserves
  • Talk with a mortgage broker before house hunting

Internal Link Silo: Related Kentucky Mortgage Guides

FHA Loan Resources

Learn down payment rules, credit score requirements, mortgage insurance, and FHA eligibility in Kentucky.

Explore Kentucky FHA loan options

USDA Rural Housing Resources

See how zero-down USDA financing works in eligible Kentucky rural and suburban areas.

Explore Kentucky USDA loan options

VA Loan Resources

Review eligibility, no-down-payment advantages, and VA-specific financing rules for Kentucky veterans.

Explore Kentucky VA loan options

KHC Down Payment Assistance

See how Kentucky Housing Corporation programs may help with down payment and closing costs.

Explore Kentucky KHC programs

Credit Repair and Mortgage Scores

Understand how mortgage credit scores work and what steps may improve your approval chances.

Read the Kentucky credit improvement guide

Frequently Asked Questions

Can I get a mortgage before 12 months in Chapter 13?

No. In most cases, you need 12 full months of on-time Chapter 13 payments before applying.

Do I need court approval to buy a house during Chapter 13?

Yes. Most borrowers need written permission from the bankruptcy court before taking on a new mortgage.

What loan is usually best during Chapter 13 bankruptcy?

FHA is usually the most common and practical option, although USDA and VA may also work depending on eligibility.

Can I get a zero down mortgage while in Chapter 13?

Possibly. USDA and VA may allow zero down for eligible borrowers, but these files still must meet stricter underwriting requirements.

Do lenders use Credit Karma scores?

No. Mortgage lenders use mortgage-specific FICO scores and qualify you based on the middle score.

Get a Free Kentucky Mortgage Review

Want to know whether you can qualify while in Chapter 13 bankruptcy?

Call/Text: 502-905-3708

kentuckyloan@gmail.com

Apply or learn more online


Joel Lobb, Mortgage Broker FHA, VA, KHC, USDA

NMLS #57916 | Company NMLS #1738461

Equal Housing Lender

This is not a commitment to lend. All loans are subject to credit approval and program requirements.

This website is not affiliated with or endorsed by FHA, VA, USDA, KHC, or any government agency.

{ “@context”:”https://schema.org”, “@type”:”BreadcrumbList”, “itemListElement”:[ { “@type”:”ListItem”, “position”:1, “name”:”Home”, “item”:”https://www.mylouisvillekentuckymortgage.com/” }, { “@type”:”ListItem”, “position”:2, “name”:”Bankruptcy Mortgage Help”, “item”:”https://www.mylouisvillekentuckymortgage.com/category/bankruptcy/” }, { “@type”:”ListItem”, “position”:3, “name”:”Can You Get a Kentucky Mortgage While in Chapter 13 Bankruptcy?”, “item”:”https://www.mylouisvillekentuckymortgage.com/kentucky-mortgage-chapter-13-bankruptcy/” } ] } { “@context”:”https://schema.org”, “@type”:”FAQPage”, “mainEntity”:[ { “@type”:”Question”, “name”:”Can I get a mortgage before 12 months in Chapter 13?”, “acceptedAnswer”:{ “@type”:”Answer”, “text”:”No. In most cases, you need 12 full months of on-time Chapter 13 payments before applying.” } }, { “@type”:”Question”, “name”:”Do I need court approval to buy a house during Chapter 13?”, “acceptedAnswer”:{ “@type”:”Answer”, “text”:”Yes. Most borrowers need written permission from the bankruptcy court before taking on a new mortgage.” } }, { “@type”:”Question”, “name”:”What loan is usually best during Chapter 13 bankruptcy?”, “acceptedAnswer”:{ “@type”:”Answer”, “text”:”FHA is usually the most common and practical option, although USDA and VA may also work depending on eligibility.” } }, { “@type”:”Question”, “name”:”Can I get a zero down mortgage while in Chapter 13?”, “acceptedAnswer”:{ “@type”:”Answer”, “text”:”Possibly. USDA and VA may allow zero down for eligible borrowers, but these files still must meet stricter underwriting requirements.” } }, { “@type”:”Question”, “name”:”Do lenders use Credit Karma scores?”, “acceptedAnswer”:{ “@type”:”Answer”, “text”:”No. Mortgage lenders use mortgage-specific FICO scores and qualify you based on the middle score.” } } ] } { “@context”:”https://schema.org”, “@type”:”Article”, “headline”:”Can You Get a Kentucky Mortgage While in Chapter 13 Bankruptcy?”, “description”:”Learn how to qualify for a Kentucky mortgage while in Chapter 13 bankruptcy, including the 12-month payment rule, court approval, FHA, USDA, VA, and KHC options.”, “mainEntityOfPage”:{ “@type”:”WebPage”, “@id”:”https://www.mylouisvillekentuckymortgage.com/kentucky-mortgage-chapter-13-bankruptcy/” }, “author”:{ “@type”:”Person”, “name”:”Joel Lobb” }, “publisher”:{ “@type”:”Organization”, “name”:”Joel Lobb, Mortgage Broker FHA, VA, KHC, USDA”, “logo”:{ “@type”:”ImageObject”, “url”:”https://www.mylouisvillekentuckymortgage.com/wp-content/uploads/your-logo.png” } }, “datePublished”:”2026-03-31″, “dateModified”:”2026-03-31″ }
How to Qualify for FHA Loans in Kentucky: Key Guidelines

Kentucky FHA Loan Requirements 2026: Credit, Down Payment, Limits & Approval Guide | Joel Lobb
Updated for 2026

Kentucky FHA Loan Requirements 2026: Credit, Down Payment, Limits & Approval Guide

Everything Kentucky first-time homebuyers need to know — credit scores, down payment, debt-to-income, mortgage insurance, property rules, waiting periods, and the deal-killers many lenders do not explain upfront.

Get pre-approved in as little as 24 hours — even if your credit is not perfect.

3.5% Minimum Down Low down payment option
580 Minimum Score Credit-friendly program
43% Typical Max DTI Can go higher with AUS
1.75% Upfront MIP Usually financed
2 yrs Work History Same field is what matters
$0 Application Fee No upfront application cost

Trusted by 1,300+ Kentucky families • 20+ years experience • FHA, VA, USDA & KHC specialist

What Is an FHA Loan and Why Does It Matter in Kentucky?

An FHA loan is a mortgage insured by the Federal Housing Administration under HUD. The FHA does not lend money directly. Instead, it insures approved lenders against loss, which allows those lenders to offer more flexible approval guidelines than many conventional programs.

For Kentucky homebuyers, especially first-time buyers, FHA financing can be a practical path to homeownership because it may allow:

  • Lower minimum credit scores than many conventional loans
  • Down payment as low as 3.5%
  • Gift funds for down payment and closing costs
  • Higher debt-to-income ratios in many cases
  • A way to buy after bankruptcy or foreclosure once waiting periods are met

1. Income & Employment Requirements

Two-Year Work History Is the Baseline

FHA generally looks for a two-year employment history. That does not always mean two years with the same employer. The bigger issue is consistency in the same line of work and the ability to document stable income.

  • Two years of employment history is preferred
  • Job changes are usually fine if they are in the same field or a logical advancement
  • Recent graduates may be able to use education history to support the file
  • Self-employed borrowers generally need two years of tax returns
  • Part-time, overtime, bonus, and commission income usually need a history before counting
💡

Kentucky tip: A job change for more pay in the same field is usually not the problem. Unexplained gaps, inconsistent hours, and unstable earnings are what create underwriting friction.

2. Credit Score & Down Payment

FHA Credit Score Tiers

Credit Score Range Minimum Down Payment Real-World Status
620 and above 3.5% Most lender-friendly
580 to 619 3.5% Usually workable
500 to 579 10% Limited lender options
Below 500 Not eligible Not FHA eligible
⚠️

Lender overlays matter. FHA may allow lower scores, but many lenders set stricter internal minimums. That is why borrowers often hear one thing online and something very different when they actually apply.

3. Debt-to-Income Limits

Front-End and Back-End DTI

Debt-to-income ratio measures how much of your gross monthly income goes toward monthly debt obligations. FHA reviews both housing-only and total debt ratios.

DTI Type What It Includes Common Target
Front-End Mortgage payment, taxes, insurance, and FHA mortgage insurance About 31%
Back-End Housing payment plus all monthly debts on credit About 43%
💡

AUS flexibility: With a strong automated approval, debt ratios can often go above 43%. With manual underwriting, the file usually gets much tighter and compensating factors matter a lot more.

4. Acceptable Down Payment Sources

Funds Must Be Verified and Sourced

FHA is flexible about where funds come from, but not loose about documentation. Every dollar used for down payment and closing costs needs a clean paper trail.

Acceptable Sources

  • Personal checking or savings
  • Verified gift funds from family or eligible donors
  • Retirement account withdrawals or loans when documented
  • Sale of personal property with documentation
  • Approved down payment assistance programs

Common Problems

  • Cash deposits with no paper trail
  • Borrowed funds from unapproved sources
  • Undocumented transfers between accounts
  • Large deposits that cannot be explained
  • Gift funds without a gift letter and evidence of transfer
⚠️

Bottom line: The money itself is often not the issue. Documentation is the issue. If the money cannot be sourced, it can derail the approval even when the borrower otherwise qualifies.

5. Property Requirements

The Home Has to Meet FHA Standards

FHA is not just approving the borrower. It is also approving the collateral. The property must be safe, sound, and marketable.

  • The property must be owner-occupied as a primary residence
  • The appraisal must support value and FHA minimum property standards
  • Health and safety issues may need to be repaired before closing
  • Utilities generally need to be on for proper appraisal review
  • Manufactured homes have additional foundation and eligibility requirements
💡

Important: FHA financing can be used on single-family homes, many condos, certain multi-unit owner-occupied properties, and some manufactured homes, but every category has its own eligibility rules.

6. Bankruptcy & Foreclosure Waiting Periods

Waiting Periods Do Exist, but FHA Is More Forgiving Than Many Programs

Credit Event Typical FHA Waiting Period Notes
Chapter 7 Bankruptcy 2 years From discharge date in most cases
Chapter 13 Bankruptcy 12 months On-time trustee payments and court approval usually required
Foreclosure 3 years From completion date in most cases
Short Sale Varies May be sooner depending on how it reported and current credit profile

7. Federal Debt & the CAIVRS Check

CAIVRS Is the Federal Database Many Buyers Never Hear About

Before FHA approval, borrowers are checked through CAIVRS, the federal database that flags certain unresolved government-related defaults or claims.

  • Defaulted federally backed student loans
  • Prior FHA or other government-backed loan claims
  • Certain unresolved federal delinquencies or judgments
🚫

A CAIVRS hit can stop the deal cold. This is not something you finesse around. The underlying issue usually has to be resolved before the FHA loan can move forward.

8. FHA Mortgage Insurance Premium

Mortgage insurance is part of the FHA tradeoff. It is one reason FHA works for lower down payment and more flexible credit, but it also increases the payment.

Upfront MIP
1.75%
Usually financed into the loan amount
Annual MIP
0.45%–1.05%
Paid monthly as part of the mortgage payment

On a $200,000 FHA loan, the upfront mortgage insurance premium adds about $3,500 to the loan amount if financed. Monthly mortgage insurance varies, but it can make a meaningful difference in payment planning.

💡

Long-term strategy: Many FHA borrowers later refinance into a conventional loan once they build equity and improve credit, because FHA mortgage insurance does not work like conventional PMI in many cases.

The Top FHA Deal-Killers in Kentucky

After working through hundreds of FHA files, these are the issues that most often kill deals, delay closings, or force borrowers to regroup.

Credit overlays

The FHA guideline may say one thing, but the actual lender may require a higher score or cleaner profile.

Unsourced funds

Cash deposits, undocumented transfers, or gift money with no paper trail can stop the loan.

Appraisal issues

Safety, condition, value, or eligibility problems can delay or kill the transaction.

Federal debt problems

Defaulted student loans or other federal issues can cause a CAIVRS denial.

High debt ratios

If the automated system does not approve it, manual underwriting can get strict quickly.

Inconsistent income

Variable hours, weak earnings history, or recent instability can reduce qualifying income.

The Smart Long-Term FHA Strategy

FHA is often the best entry point, not always the best forever loan. For many Kentucky buyers, the real win is using FHA to get in the home now, then improving the credit profile and refinancing later when the numbers make sense.

1

Get pre-approved

Run the numbers honestly and determine what is actually workable today.

2

Use the right assistance

Layer in any available gift funds or down payment assistance that fits the file.

3

Buy with a plan

Get into the home, stabilize finances, build equity, and improve the credit profile.

4

Refinance later

Review conventional refinance options when rates, equity, and scores line up.

Frequently Asked Questions — Kentucky FHA Loans

Can I get an FHA loan with a 580 credit score in Kentucky?

Yes. FHA guidelines allow 580 with 3.5% down, but many lenders have overlays. Real-world approval depends on the full file, not just the score.

Is there down payment assistance available for Kentucky FHA loans?

Yes. Some Kentucky borrowers may qualify for Kentucky Housing Corporation down payment assistance, depending on income, credit, and program limits.

How long does FHA approval take in Kentucky?

A pre-approval can often be issued quickly with full documentation. From contract to closing, many FHA purchases land in the 30 to 45 day range, though every file is different.

Can I use an FHA loan to buy a duplex in Kentucky?

Yes, if you live in one unit as your primary residence and the property meets FHA rules. FHA is not for a pure non-owner-occupied investment purchase.

Does FHA mortgage insurance ever go away?

That depends on the loan structure, but many FHA borrowers eventually refinance into conventional financing once they have enough equity and improved credit.

What is the FHA loan limit for Kentucky in 2026?

Loan limits depend on property type and county rules in effect for the year. Always verify current limits for the specific property and loan structure before proceeding.

Ready to Apply for an FHA Loan in Kentucky?

Start your free mortgage review with Joel Lobb. Get straight answers on credit, income, down payment, and what you may qualify for now — without wasting time on the wrong program.

JL

Joel Lobb — Kentucky Mortgage Loan Officer

20+ years of experience | 1,300+ Kentucky families helped | FHA, VA, USDA, KHC & Conventional loans

NMLS #57916 Company NMLS #1738461 Licensed in Kentucky Equal Housing Lender

NMLS #57916 | Company NMLS #1738461 | Equal Housing Lender. This is not a commitment to lend. All loans are subject to credit approval and program requirements. This website is not affiliated with or endorsed by FHA, VA, USDA, KHC, or any government agency. Licensed in Kentucky only. NMLS Consumer Access

Kentucky FHA Loan Essentials for New Homebuyers

Louisville Kentucky Mortgage Lender for FHA, VA, KHC, USDA and Rural  Housing Kentucky Mortgages: What is the difference between Conventional, FHA  and VA Mortgage loans in Kentucky?


<!– WordPress.com-friendly page content (no , no , no ) –>

Kentucky FHA Loans (2026): Requirements, Down Payment, Credit Scores, and How to Get Approved

If you are buying a home in Kentucky and want a low down payment option with more flexible credit guidelines, an FHA loan is often the most practical path. This guide covers the FHA rules that matter in 2026, the common underwriting issues that slow people down, and the fastest way to get a clean pre-approval.

Want a same-day pre-approval review? Call or text 502-905-3708 or email kentuckyloan@gmail.com.

Helpful links (official + Kentucky-specific):
• FHA loan limits lookup (by Kentucky county): HUD FHA Mortgage Limits
• FHA underwriting rules source document: HUD Handbook 4000.1
• Kentucky Housing down payment assistance overview: KHC Down Payment Assistance


Quick FHA Requirements Snapshot (Kentucky)

  • Minimum down payment: 3.5% with 580+ credit score; 10% with 500–579 (case-by-case).
  • Primary residence only (no investment property).
  • FHA appraisal required and the home must meet FHA property standards.
  • Seller concessions allowed up to 6% of the sales price toward certain closing costs and fees.
  • Mortgage insurance is required (upfront + monthly/annual).

Want me to price your payment and cash-to-close fast? Text “FHA” to 502-905-3708 and I will reply with a document checklist.


Credit Score Guidelines for Kentucky FHA Loans

FHA guidelines allow:

  • 580+ credit score: eligible for the 3.5% minimum down payment option.
  • 500–579 credit score: may be eligible with 10% down (approval depends on the full file).
  • Below 500: generally not eligible for FHA financing.

Important: lenders can add “overlays” (stricter requirements than FHA). That is why two lenders can give two different answers on the same borrower. If you want a straight answer, I will review your scenario and tell you what is realistically approvable.

Next step: Call or text 502-905-3708 for a quick credit-and-income review.


Down Payment and Closing Costs (What Kentucky Buyers Actually Pay)

FHA requires a minimum down payment based on credit score. Closing costs are separate and typically include lender fees, title, escrow, and prepaid items like taxes and homeowners insurance.

3 ways Kentucky FHA buyers reduce cash-to-close

  • Seller concessions (up to 6% of the sales price, when allowed and properly structured).
  • KHC Down Payment Assistance (for eligible borrowers using a KHC first mortgage).
  • Lender credits (higher rate trade-off to reduce upfront costs, when it makes sense).

External reference on seller concessions: HUD guidance on interested party contributions


Kentucky FHA Loan Limits (2026)

FHA loan limits change by county and are updated periodically. The cleanest way to avoid outdated numbers is to pull your county limit directly from HUD.

Use this official lookup tool: HUD FHA Mortgage Limits by County

If you text me your county (or the property address), I will confirm the current FHA limit and your max purchase price: 502-905-3708.


Debt-to-Income Ratio (DTI): What FHA Looks At

FHA underwriting looks at housing expense compared to income and total monthly debts compared to income. A common baseline guideline you will see referenced is 31% for housing and 43% for total debt, with exceptions possible depending on automated underwriting results and compensating factors.

  • Housing ratio (front-end): proposed house payment compared to gross monthly income.
  • Total DTI (back-end): house payment plus monthly debts compared to gross monthly income.

If your DTI is tight, the fix is usually one of these: adjust purchase price, restructure debt, improve credit, or document additional qualifying income correctly.


Types of FHA Loans Kentucky Buyers Use Most

FHA 203(b) Standard Purchase

The most common FHA loan for buying a primary residence in Kentucky.

FHA 203(k) Renovation Loan

Combines purchase plus renovation costs into one loan for qualifying homes that need repairs or updates.

FHA Streamline Refinance

For existing FHA borrowers looking to reduce payment with simplified documentation (when eligible).

FHA Cash-Out Refinance

For homeowners who want to access equity (subject to FHA rules and underwriting).

Internal links (recommended):
• VA Loans: Kentucky VA Home Loans
• USDA Loans: Kentucky USDA Zero Down Loans
• KHC Programs: Kentucky Housing (KHC) Loan Programs


KHC Down Payment Assistance (Pairs Well with FHA)

Kentucky Housing Corporation (KHC) offers down payment assistance for eligible borrowers using a KHC first mortgage. KHC’s Regular DAP has been listed as assistance up to $12,500, repayable over 15 years at 4.75% (subject to program terms, eligibility, and availability). Confirm current options here: KHC Down Payment Assistance.

If you want a straight answer on eligibility (income limits, purchase price limits, and which first mortgage fits), call or text me: 502-905-3708.


How to Apply for an FHA Loan in Kentucky (Simple Process)

  1. Quick consult (10 minutes): goals, county, price range, and down payment plan.
  2. Document review: paystubs, W-2s, bank statements, and ID.
  3. Run automated underwriting and issue a clean pre-approval.
  4. Home shopping + contract.
  5. Appraisal, underwriting, and final approval.
  6. Closing and keys.

Primary CTA:
Call or Text 502-905-3708 for FHA Pre-Approval
Email: kentuckyloan@gmail.com

Secondary CTA (site):
Start here: mylouisvillekentuckymortgage.com


FHA FAQ (Kentucky)

Do FHA loans have income limits?

FHA itself does not set income limits. However, down payment assistance programs (like KHC) typically do.

How long does an FHA loan take to close?

Many FHA purchases close in the 30–45 day range, depending on appraisal timing, documentation, and underwriting conditions.

Can the seller pay my closing costs on FHA?

Seller concessions are allowed up to 6% of the sales price toward certain costs when structured correctly. Reference: HUD guidance.

Where can I verify FHA loan limits for my Kentucky county?

Use HUD’s official lookup tool: FHA Mortgage Limits.


About

Joel Lobb — Kentucky Mortgage Loan Officer
NMLS Personal ID: 57916 | Company NMLS: 1738461
Call/Text: 502-905-3708 | Email: kentuckyloan@gmail.com
NMLS Consumer Access: nmlsconsumeraccess.org


Equal Housing Lender
Joel Lobb | NMLS 57916 | Company NMLS 1738461
10602 Timberwood Circle, Louisville, KY 40223
This is an advertisement. Not a commitment to lend. All loan approvals are subject to underwriting guidelines and program eligibility. Terms and conditions apply. Programs, rates, and guidelines are subject to change without notice.
This website is not endorsed by or affiliated with the FHA, VA, USDA, KHC, or any government agency.

Your Guide to Kentucky FHA Loans

Kentucky FHA loans can be an excellent option for first-time homebuyers and borrowers with lower incomes or less-than-perfect credit. They can also be an easy way to refinance. .

Features and benefits:

  • Low down payment from borrower or other approved source1
  • 580 credit score with 96.5 Financing and down to 500 score with 500 score on case by case
  • Streamline option refinance with no appraisal
  • Up to 6% seller contributions to pay your closing costs and prepaids
  • AUS with FHA TOTAL Mortgage Scorecard
  • Waivers for some ratio and documentation

Purchase, rate/term, or cash-out refinance of a primary residence. Program terms available may vary based on the state or county in which the financed
property is located. Mortgage insurance is required.
CONSIDERATIONS: Important information will be provided to you in the disclosures you receive after we have received your application and the loan
documents you are provided at loan closing. Please consult your tax advisor regarding the deductibility of interest.
Contributions may have limitations based upon occupancy and loan to value ratios and cannot be used for purposes of down payment, reserve
requirement or meet minimum contribution requirements
Programs for qualified borrowers. All borrowers are subject to credit approval, underwriting approval and product requirements, including loan to
value, credit score limits and other lender terms and conditions. Fees and charges may vary by state and are subject to change without notice. Some
restrictions may apply. Not a commitment to lend. 11/22

Getting An FHA Loan

In order to get an FHA loan to buy your next house, it’s a good idea to first check your credit score. That way, you can see what your maximum LTV would be through the FHA and decide whether an FHA loan might be right for you.

Depending on which FHA lender you’re working with, it may also be a good idea to get pre-qualified for an FHA loan. This can help you establish how much you’ll likely be able to borrow and what your interest rate may be.

Application and Underwriting

Once you’ve identified a home you want to purchase and are ready to formally apply for your mortgage loan, you’ll need to choose an FHA-approved lender and work through its individual application and underwriting process. The application process will include completion of a Uniform Residential Loan Application.

As part of your application, you’ll also need to get an appraisal for the home you’re buying, so your lender can ensure your loan won’t violate FHA’s LTV limits. From there, you’ll need to work through your individual lender’s underwriting process, which will include showing proof of income, running credit checks and demonstrating that you can afford your down payment.

Some of the documentation you’ll likely need to supply for underwriting include:

  • A credit report
  • Employment history for two years
  • Income verification with recent pay stubs, bank statements and/or three years of tax returns
  • Proof that you are using the loan for a primary residence
  • An FHA-approved appraisal

After you complete your lender’s application process and underwriting, your lender can formally approve your loan and you can close on your home.

Who Should Consider FHA Loans

FHA loans don’t have stated income maximums or minimums, but are generally designed to benefit low- to moderate-income Americans who would have trouble qualifying for conventional financing or affording the down payment required by other loans.

Some potential cases when FHA loans can be particularly helpful include:

  • First-time homebuyers who can’t afford a large down payment
  • People who are rebuilding their credit
  • Seniors who need to convert equity in their homes to cash

Types Of FHA Loans

There are more than a dozen home loan programs available through the FHA. Many of these programs are ideal for different borrowers in a variety of circumstances, offering everything from 30-year fixed-rate mortgages to adjustable rates, improvement loans, refinancing solutions and even reverse mortgages.

Some of the most popular FHA loan programs are:

  • FHA Section 203(b) loan. The FHA’s most popular home loan program, offering fixed rates on properties from one to four units.
  • FHA Section 203(k) loan. FHA mortgages designed to help homebuyers finance up to $35,000 in improvements to their new homes.
  • Streamline Refinancing. An option for existing FHA borrowers to refinance their loans with streamlined underwriting.

FHA Loans Vs. Conventional Mortgages

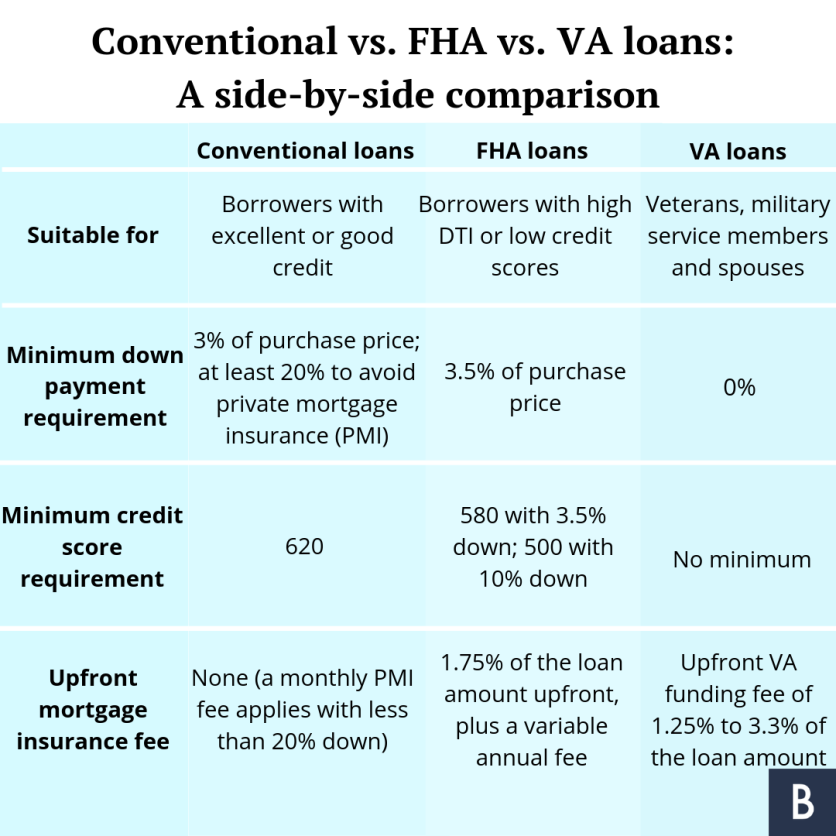
Most conventional mortgages require down payments of at least 20% of a home’s purchase price in order to avoid paying private mortgage insurance, along with minimum credit scores of 620 to 640 in order to qualify. With private mortgage insurance (PMI) that helps homeowners pay their mortgage if they lose their jobs, some lenders require lower down payments.

FHA loans have two types of built-in mortgage insurance that allow borrowers to buy homes with as little as 3.5% down—or 10% if they have bad credit. In addition, these loans allow homebuyers to qualify for lower interest rates than they would get with conventional mortgages, all because their loans are federally insured.

FHA LoanConventional Mortgage
Minimum credit score500620
Minimum down payment3.5% if your credit score is 580 or higher; 10% for scores under 58020% to avoid mortgage insurance
Maximum loan term30 years30 years
Mortgage insurance requirementTwo types of mortgage insurance requiredRequired if down payment is under 20%

Pros of FHA Loans

  • High maximum loan-to-value
  • Competitive interest rates
  • Multiple programs available
  • Can qualify with bad credit
  • Closing costs are sometimes paid by lenders

Cons of FHA Loans

  • Mortgage insurance is required for extra cost
  • Only available for a primary residence
  • Must show proof of income
  • Debt-to-income ratio must be under 43% (slightly lower than a conventional loan requires)

Bottom Line

The Federal Housing Administration (FHA) was created in the 1930s in response to the Great Depression to help Americans who couldn’t otherwise afford the dream of homeownership.

Today, the FHA continues to help Americans through more than a dozen loan programs that help Americans with low incomes or bad credit qualify for lower interest rates than they would otherwise get, and buy homes with much smaller down payments than those required by conventional lending tools. The FHA does this by working with approved lenders to insure loans across the country and by building two types of mortgage insurance into all of the loans that it insures.

So, if you have poor credit or are struggling to save for a down payment, you may want to consider using an FHA loan for your next home purchase.

https://www.mylouisvillekentuckymortgage.com/

Options for Bad Credit Home Buyers in Kentucky

Bad Credit Home Loans in Kentucky

Many Kentucky homebuyers assume a low credit score automatically disqualifies them from buying a home. That assumption is incorrect. Several mortgage programs are specifically designed to help buyers with past credit issues qualify for financing sooner than expected.

In Kentucky, the most common loan options for buyers with bad or fair credit include FHA, VA, USDA, and select conventional loan programs. Each option has different credit score thresholds, down payment requirements, and underwriting flexibility.

Minimum Credit Score Requirements by Loan Type

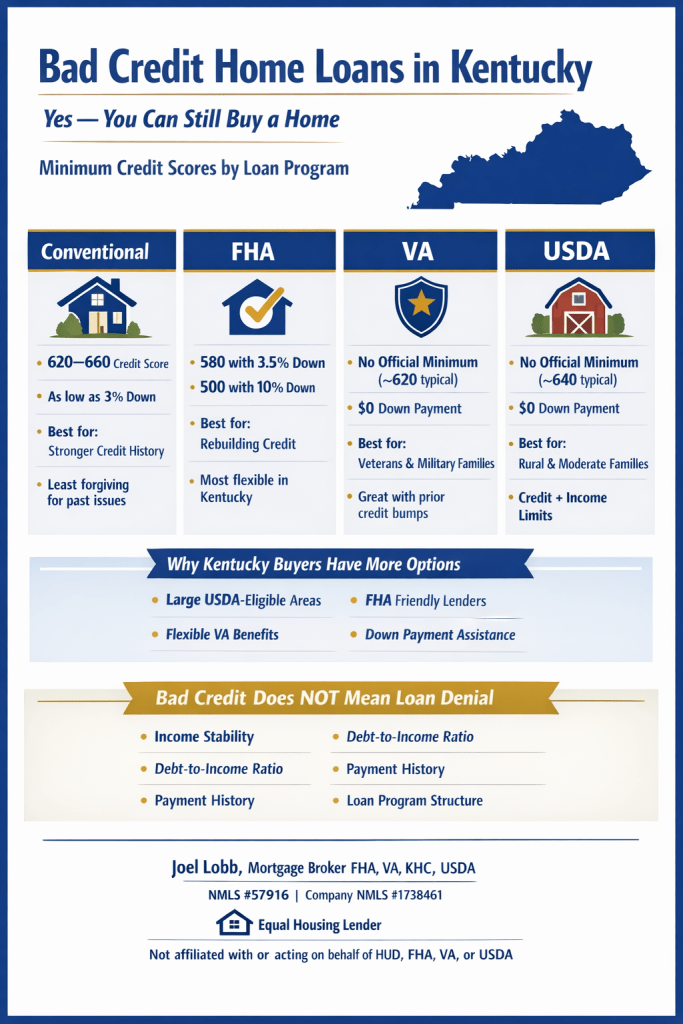
Conventional loans typically require a minimum credit score between 620 and 660, depending on the program and automated underwriting results. While down payments can be as low as 3 percent, conventional loans are generally the least forgiving when it comes to recent late payments, collections, or limited credit history.

FHA loans in Kentucky are the most common solution for buyers rebuilding credit. FHA financing allows approvals with credit scores as low as 580 with only 3.5 percent down. In limited cases, buyers with scores down to 500 may qualify with a 10 percent down payment, provided the overall risk profile is strong.

Eligible service members and veterans may benefit from VA loans in Kentucky, which do not have an official minimum credit score requirement set by the agency. Most lenders look for scores around 620, but VA loans remain one of the most flexible options available, offering zero down payment and no monthly mortgage insurance.

For buyers purchasing outside major metro areas, USDA loans in Kentucky can provide 100 percent financing with competitive interest rates. While there is no official minimum credit score, most USDA lenders require a 640 score for automated approval, along with meeting income and household eligibility guidelines.

Why Kentucky Buyers Often Qualify With Lower Credit Scores

  • Large portions of Kentucky qualify for USDA rural housing loans
  • FHA loans are widely accepted by Kentucky lenders
  • VA loans provide exceptional flexibility for eligible veterans
  • Down payment assistance programs can be layered correctly with the right loan structure

What Mortgage Underwriters Actually Review

Mortgage approval is based on the full financial picture, not just the credit score. Underwriters evaluate income stability, work history, debt-to-income ratio, recent payment behavior, available assets, and how the loan is structured.

In many cases, a borrower with a lower credit score but strong income stability and clean recent payment history can be a stronger approval than someone with a higher score and excessive debt.

Bottom Line for Kentucky Homebuyers

Bad credit does not automatically mean loan denial. The right loan program, structured correctly from the start, often matters more than the credit score alone. Many Kentucky buyers qualify months or even years sooner than they expect once their options are reviewed properly.

NMLS #57916 | Company NMLS #1738461
Equal Housing Lender.
This is not a commitment to lend. All loans are subject to credit approval and program requirements.

Bad Credit Home Loans in Kentucky