How to Get A Kentucky FHA Upfront Mortgage Insurance Premium (UFMIP) Refund

Kentucky FHA Refinance Guide (HUD-Compliant)

FHA UFMIP Refund: Official HUD Rules Kentucky Homeowners Need to Know

If you refinance an existing FHA loan into a new FHA loan, HUD may provide a partial refund of your upfront mortgage insurance premium.

What is an FHA UFMIP Refund?

FHA requires an upfront mortgage insurance premium (UFMIP), typically 1.75% of the base loan amount. According to HUD guidance, borrowers who refinance an FHA-insured loan into another FHA-insured loan may be eligible for a partial refund of the previously paid UFMIP.

The refund is not paid in cash. It is applied as a credit toward the new upfront mortgage insurance premium on the new FHA loan.

HUD Requirements for Eligibility

  • Existing loan must be FHA-insured
  • New loan must also be FHA-insured
  • Loan must not be delinquent beyond HUD allowable limits
  • Refinance must meet FHA net tangible benefit requirements

How the FHA UFMIP Refund is Calculated

HUD does not use a flat percentage schedule for public guidance. Instead, the refund is calculated using FHA’s official insurance amortization method based on:

  • Time elapsed since loan endorsement
  • Original upfront premium paid
  • Remaining insurance exposure

The refund amount declines monthly and is administered through FHA Connection at the time of refinance.

Critical HUD Rule

No refund is due after the third year (36 months) of insurance.

Example (HUD-Based Explanation)

Example scenario based on FHA structure:

  • Loan Amount: $200,000
  • UFMIP Paid: $3,500
  • Refinance within first 12–24 months

A portion of the $3,500 may be credited toward the new FHA upfront premium, depending on the exact month of refinance and HUD’s internal calculation.

What This Means Strategically

From a lending strategy standpoint, this creates a limited-time refinance window where:

  • You may recover part of your upfront cost
  • You may reduce your interest rate
  • You may lower your monthly payment

However, the benefit declines every month and disappears after 36 months. Timing is critical.

Common Misconceptions

  • There is no guaranteed refund percentage
  • Refunds are not issued as cash payments
  • This does not apply to conventional, VA, or USDA refinancing

When Should Kentucky Homeowners Review This?

If your FHA loan closed within the last 36 months, it is worth evaluating your refinance options immediately. Waiting reduces or eliminates your refund eligibility.

Free FHA Refinance Review

Find out if you qualify for a UFMIP refund and lower payment.

Call/Text: 502-905-3708

Joel Lobb, Mortgage Broker FHA, VA, KHC, USDA


Joel Lobb | Mortgage Loan Officer | NMLS #57916 | Company NMLS #1738461 | Equal Housing Lender

This is not a commitment to lend. All loans are subject to credit approval and program requirements.

This website is not affiliated with or endorsed by FHA, VA, USDA, KHC, or any government agency.

How to Get A Kentucky FHA Upfront Mortgage Insurance Premium (UFMIP) Refund

Kentucky FHA Refinance Guide (HUD-Compliant)

FHA UFMIP Refund: Official HUD Rules Kentucky Homeowners Need to Know

If you refinance an existing FHA loan into a new FHA loan, HUD may provide a partial refund of your upfront mortgage insurance premium.

FHA borrowers in Kentucky often overlook one major refinance benefit: if you refinance from one FHA-insured loan into another FHA-insured loan, part of the upfront mortgage insurance premium you previously paid may be credited toward the new loan.

Timing matters. The longer you wait, the smaller the benefit becomes. After 36 months, the refund opportunity is generally gone.

FHA UFMIP Refund Schedule infographic Kentucky FHA refinance

Refinance timing directly impacts how much FHA UFMIP may be credited toward your new loan.

What is an FHA UFMIP Refund?

FHA requires an upfront mortgage insurance premium (UFMIP), typically 1.75% of the base loan amount. If you refinance your existing FHA loan into another FHA-insured loan, part of that previously paid premium may be credited toward the new upfront mortgage insurance premium.

HUD Requirements for Eligibility

  • Existing loan must be FHA-insured
  • New loan must also be FHA-insured
  • Loan must meet FHA payment history guidelines
  • Refinance must meet net tangible benefit requirements

Critical HUD Rule

No refund is due after 36 months.
Kentucky FHA refinance UFMIP refund ad with call to action

Free FHA Refinance Review

Find out if you qualify for a UFMIP refund and lower your payment.

Call/Text: 502-905-3708

Joel Lobb, Mortgage Broker FHA, VA, KHC, USDA


Joel Lobb | Mortgage Loan Officer | NMLS #57916 | Company NMLS #1738461 | Equal Housing Lender

This is not a commitment to lend. All loans are subject to credit approval and program requirements.

This website is not affiliated with or endorsed by FHA, VA, USDA, KHC, or any government agency.

1 –  Email – kentuckyloan@gmail.com 

2.   Call/Text – 502-905-3708

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans


🌐 Website: www.mylouisvillekentuckymortgage.com
🏢 Address: 911 Barret Ave., Louisville, KY 40204


Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.

Kentucky Local Home Loan Lender Services

✅ First-Time Home Buyers Welcome
✅ FHA, Rural Housing (USDA), VA, and Kentucky Housing Corporation (KHC) Loans
✅ Conventional Loan Options Available
✅ Fast Local Decision-Making
✅ Experienced Guidance Through the Home Buying Process

If you are an individual with disabilities who needs accommodation, please contact us at 502-905-3708. If you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

FHA Loans in Kentucky: A Complete Guide for First-Time Buyers

Kentucky FHA Loan Guide — Updated for 2026

2026 Kentucky FHA Loan Limits & Complete Requirements Guide

Kentucky FHA loans remain one of the most accessible paths to homeownership for first-time buyers in Louisville, Lexington, Bowling Green, and all 120 counties statewide. Backed by the Federal Housing Administration (HUD), FHA loans offer low down payments, flexible credit requirements, and competitive interest rates — making them ideal for buyers who may not qualify for a conventional mortgage.

Effective January 1, 2026, FHA loan limits increased by 3.26% across all Kentucky counties. The new single-family limit is $541,288 — up $17,063 from 2025. This guide covers everything you need to know: updated loan limits, credit requirements, down payment assistance, mortgage insurance, and answers to the most common questions Kentucky homebuyers ask.

2026 Loan Limit
$541,288
Single-Family · All 120 KY Counties
Min Down Payment
3.5%
With 580+ Credit Score
Minimum Credit Score
500
580+ for 3.5% Down
Max Debt-to-Income
57%
With Compensating Factors
2026 Kentucky FHA Loan Limits — All 120 Counties Bar chart showing 2026 FHA loan limits for Kentucky by property type: 1-unit $541,288, 2-unit $693,050, 3-unit $837,700, 4-unit $1,041,125. Source: HUD Mortgagee Letter 2025-23. 2026 Kentucky FHA Loan Limits All 120 Counties · Effective January 1, 2026 · HUD ML 2025-23 LOAN LIMITS BY PROPERTY TYPE $300K $600K $900K $541K $693K $837K $1.04M 1-Unit Single-Family 2-Unit Duplex 3-Unit Triplex 4-Unit Fourplex CREDIT SCORE 580+ for 3.5% down MIN DOWN PAYMENT $18,945 3.5% of $541,288 UPFRONT MIP 1.75% rolled into loan Source: HUD Mortgagee Letter 2025-23 · Limits up +3.26% from 2025 · Joel Lobb NMLS #57916 · 502-905-3708
2026 Kentucky FHA Loan Limits — All 120 Counties · Source: HUD Official Loan Limit Tool

2026 FHA Loan Limits — All 120 Kentucky Counties

Kentucky is a standard-cost state. All 120 counties use the same national floor limits as published in HUD Mortgagee Letter 2025-23. Verify your county limit with the official HUD loan limit lookup tool.

Property Type 2025 Limit 2026 Limit Increase
1-Unit — Single-Family Home $524,225 $541,288 +$17,063
2-Unit — Duplex $671,200 $693,050 +$21,850
3-Unit — Triplex $811,275 $837,700 +$26,425
4-Unit — Fourplex $1,008,300 $1,041,125 +$32,825

* Limits apply to the base loan amount only. Loan approval depends on credit, income, and property eligibility. The 3.26% increase reflects continued home price appreciation per the FHFA House Price Index.

Advantages

Why Kentucky Buyers Choose FHA

  • Low 3.5% down payment (580+ credit)
  • Credit scores as low as 500 considered
  • Competitive rates vs. conventional loans
  • Down payment can be a gift from family
  • Higher debt-to-income ratios accepted
  • Available after bankruptcy (2 yrs) or foreclosure (3 yrs)
  • Pairs with KHC down payment assistance
  • Seller can pay up to 6% in closing costs
  • FHA Streamline refinance available later
Requirements

Basic Eligibility Requirements

  • Must be a primary residence (not investment)
  • Property must meet FHA minimum property standards
  • 2-year employment history (same line of work)
  • Valid Social Security number
  • Lawful U.S. residency
  • Mortgage insurance premium (MIP) required
  • Loan within 2026 FHA county loan limits
  • No delinquent federal debt or tax liens
  • Must intend to occupy within 60 days of closing

FHA Mortgage Insurance (MIP) — What to Expect

Upfront MIP
1.75% of the loan amount — typically rolled into the loan balance at closing
Annual MIP (paid monthly)
0.55% per year for 30-year loans with less than 10% down
MIP Duration — Less Than 10% Down
MIP remains for the life of the loan
MIP Duration — 10%+ Down
MIP cancels automatically after 11 years
Pro Tip: Once you’ve built 20% equity in your home, you may be able to refinance into a conventional loan and eliminate MIP entirely — potentially saving hundreds per month. Ask me about Kentucky refinance options.

Other Kentucky Mortgage Programs to Compare

FHA is not the only option. Depending on your credit, income, and location, one of these programs may save you even more money:

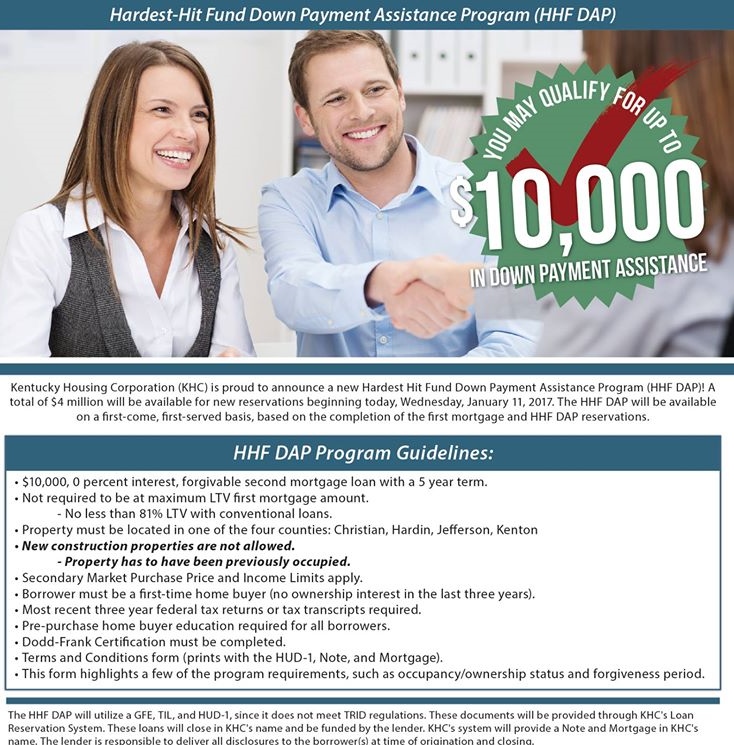
Up to $10,000–$12,500 available. Stacks on top of FHA to eliminate your down payment. Income and purchase price limits apply. Available through Kentucky Housing Corporation.
Zero down payment for eligible rural and suburban Kentucky areas. No monthly MIP like FHA — just a small guarantee fee. Income limits apply. Great alternative for buyers outside Louisville and Lexington.
Zero down payment, no MIP for eligible veterans and active duty military. The best mortgage program available if you qualify. No loan limits for veterans with full entitlement.
Better option for buyers with 620+ credit and 3-5% down. PMI cancels at 20% equity (unlike FHA MIP). 2026 conforming limit: $806,500 for most Kentucky counties.

Not sure which program is right for you? I’ll compare all your options at no cost. See the full Kentucky mortgage program comparison guide on my blog.


Frequently Asked Questions — FHA Loans in Kentucky (2026)

What is the FHA loan limit in Kentucky for 2026?

The 2026 FHA loan limit for all 120 Kentucky counties is $541,288 for a single-family home — up from $524,225 in 2025, a 3.26% increase. Multi-unit limits are $693,050 (duplex), $837,700 (triplex), and $1,041,125 (fourplex). Kentucky is a standard-cost state, meaning all counties use the same national floor limit with no high-cost county adjustments. Source: HUD Mortgagee Letter 2025-23.

What credit score do I need for an FHA loan in Kentucky?

The FHA minimum is 500. With a score of 500–579, you’ll need a 10% down payment. With 580 or higher, you qualify for the 3.5% down payment option. Most lenders — including our programs — work with scores in the 580–620 range where conventional loans are typically unavailable. If your score needs work, I can help with a credit improvement plan at no cost before you apply. Call or text 502-905-3708.

Can I get an FHA loan after a bankruptcy or foreclosure in Kentucky?

Yes. FHA waiting periods are: Chapter 7 bankruptcy — 2 years from discharge date. Chapter 13 bankruptcy — 12 months of on-time trustee payments with court approval. Foreclosure — 3 years from the completed foreclosure date. You must have re-established good credit since the event. This flexibility is one of the biggest reasons Kentucky first-time homebuyers choose FHA over conventional loans.

Can I combine a 2026 FHA loan with KHC down payment assistance?

Absolutely — this is one of the most powerful combinations available to Kentucky homebuyers. Kentucky Housing Corporation (KHC) offers up to $10,000–$12,500 in down payment assistance that can be layered on top of an FHA loan, potentially covering your entire 3.5% down payment. The KHC purchase price limit for 2026 is $544,232. Income limits vary by county. Learn more about KHC programs or call me to check your eligibility.

What is the difference between FHA and a conventional loan in 2026?

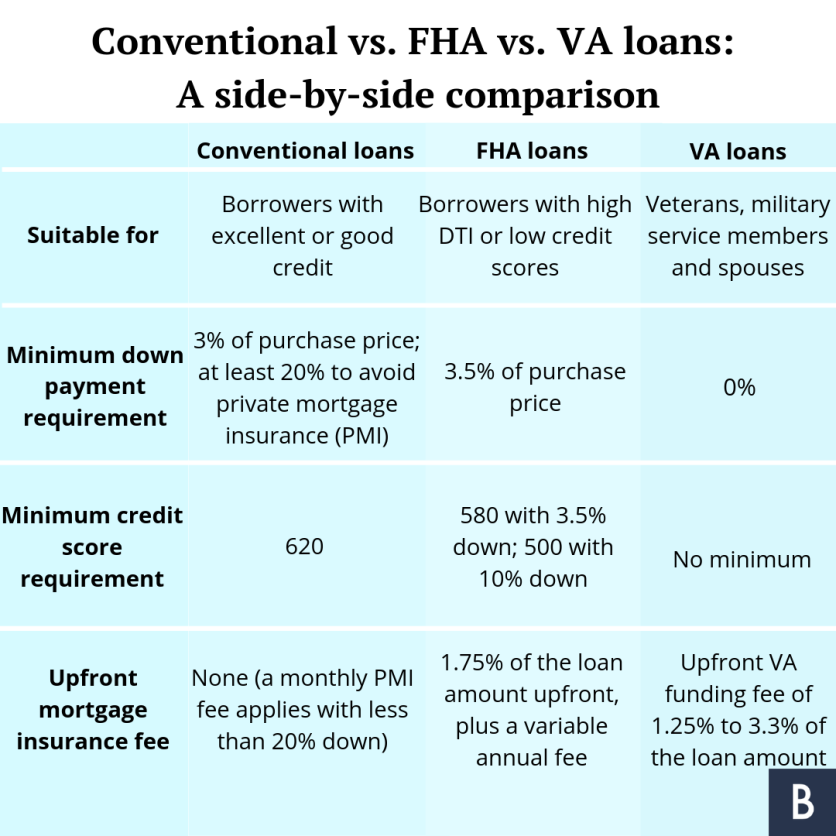
FHA loans are government-backed and more forgiving on credit scores, down payments, and debt-to-income ratios. Conventional loans typically require 620+ credit and stronger finances, but private mortgage insurance (PMI) can be canceled once you reach 20% equity — unlike FHA MIP, which stays for the life of the loan if you put less than 10% down. The 2026 conventional conforming limit is $806,500 (higher than FHA’s $541,288 floor). FHA is better for buyers with credit challenges or limited savings. Conventional may be a better choice once you have 620+ credit. See my Kentucky mortgage program comparison for more detail.

How long does FHA loan approval take in Kentucky?

I offer free applications with same-day pre-approvals. Having your documents ready upfront (last 30 days of pay stubs, 2 years of W-2s and tax returns, 2–3 months of bank statements) speeds the process. Full loan closing from an accepted contract typically takes 30–45 days. Email me or call 502-905-3708 to start your free pre-approval today.

Can I buy a duplex or multi-unit property with a 2026 FHA loan?

Yes — FHA loans can finance 1 to 4 unit properties as long as you live in one unit as your primary residence. The 2026 limits are: Duplex $693,050 · Triplex $837,700 · Fourplex $1,041,125. Rental income from other units can often be used to help you qualify. This “house hacking” strategy is a popular way for Kentucky buyers to start building wealth while keeping monthly costs low. A standard 3.5% down payment applies.

Is there an income limit for FHA loans in Kentucky?

No — FHA loans have no maximum income limit. Anyone who meets the credit, down payment, and debt-to-income requirements can apply regardless of income. This differs from programs like USDA Rural Housing and some KHC programs, which do have household income caps.

Can my down payment be a gift from a family member?

Yes — FHA allows 100% of your down payment to come from a gift from a family member, employer, or approved nonprofit. The donor must provide a signed gift letter stating no repayment is expected. This is one of FHA’s biggest advantages over most conventional programs. When combined with KHC down payment assistance, many Kentucky buyers close with very little out of pocket.

What documents do I need to apply for a Kentucky FHA loan?

You’ll typically need: last 30 days of pay stubs, 2 years of W-2s and federal tax returns, 2–3 months of bank statements, a valid government-issued photo ID, and your Social Security number. Self-employed borrowers also need 2 years of business returns and a year-to-date profit & loss statement. I’ll walk you through exactly what’s needed during our free pre-approval call — no obligation. Call/text 502-905-3708 or email kentuckyloan@gmail.com.

Ready to Get Pre-Approved for a 2026 Kentucky FHA Loan?

Free application  ·  Same-day pre-approval  ·  No obligation  ·  All 120 Kentucky counties  ·  NMLS #57916

With over 20 years of experience and more than 1,300 Kentucky families helped, I specialize exclusively in Kentucky mortgage loans — FHA, VA, USDA, KHC, and Conventional. I know how to structure your loan to maximize your benefits and minimize your out-of-pocket costs at closing.

📞 Call/Text 502-905-3708 ✉ kentuckyloan@gmail.com

Joel Lobb  ·  Mortgage Loan Officer  ·  NMLS Personal ID #57916  ·  Company NMLS #1738461  ·  Equal Housing Lender  ·  www.nmlsconsumeraccess.org
This website is not endorsed by or affiliated with the FHA, VA, USDA, or any government agency. All loan programs are subject to credit approval, income verification, and property eligibility. Loan limits and program availability subject to change without notice. Rates are not guaranteed and subject to change daily. Information provided is for educational purposes only and does not constitute a commitment to lend.

Kentucky FHA Loan Essentials for New Homebuyers

Louisville Kentucky Mortgage Lender for FHA, VA, KHC, USDA and Rural  Housing Kentucky Mortgages: What is the difference between Conventional, FHA  and VA Mortgage loans in Kentucky?


<!– WordPress.com-friendly page content (no , no , no ) –>

Kentucky FHA Loans (2026): Requirements, Down Payment, Credit Scores, and How to Get Approved

If you are buying a home in Kentucky and want a low down payment option with more flexible credit guidelines, an FHA loan is often the most practical path. This guide covers the FHA rules that matter in 2026, the common underwriting issues that slow people down, and the fastest way to get a clean pre-approval.

Want a same-day pre-approval review? Call or text 502-905-3708 or email kentuckyloan@gmail.com.

Helpful links (official + Kentucky-specific):
• FHA loan limits lookup (by Kentucky county): HUD FHA Mortgage Limits
• FHA underwriting rules source document: HUD Handbook 4000.1
• Kentucky Housing down payment assistance overview: KHC Down Payment Assistance


Quick FHA Requirements Snapshot (Kentucky)

  • Minimum down payment: 3.5% with 580+ credit score; 10% with 500–579 (case-by-case).
  • Primary residence only (no investment property).
  • FHA appraisal required and the home must meet FHA property standards.
  • Seller concessions allowed up to 6% of the sales price toward certain closing costs and fees.
  • Mortgage insurance is required (upfront + monthly/annual).

Want me to price your payment and cash-to-close fast? Text “FHA” to 502-905-3708 and I will reply with a document checklist.


Credit Score Guidelines for Kentucky FHA Loans

FHA guidelines allow:

  • 580+ credit score: eligible for the 3.5% minimum down payment option.
  • 500–579 credit score: may be eligible with 10% down (approval depends on the full file).
  • Below 500: generally not eligible for FHA financing.

Important: lenders can add “overlays” (stricter requirements than FHA). That is why two lenders can give two different answers on the same borrower. If you want a straight answer, I will review your scenario and tell you what is realistically approvable.

Next step: Call or text 502-905-3708 for a quick credit-and-income review.


Down Payment and Closing Costs (What Kentucky Buyers Actually Pay)

FHA requires a minimum down payment based on credit score. Closing costs are separate and typically include lender fees, title, escrow, and prepaid items like taxes and homeowners insurance.

3 ways Kentucky FHA buyers reduce cash-to-close

  • Seller concessions (up to 6% of the sales price, when allowed and properly structured).
  • KHC Down Payment Assistance (for eligible borrowers using a KHC first mortgage).
  • Lender credits (higher rate trade-off to reduce upfront costs, when it makes sense).

External reference on seller concessions: HUD guidance on interested party contributions


Kentucky FHA Loan Limits (2026)

FHA loan limits change by county and are updated periodically. The cleanest way to avoid outdated numbers is to pull your county limit directly from HUD.

Use this official lookup tool: HUD FHA Mortgage Limits by County

If you text me your county (or the property address), I will confirm the current FHA limit and your max purchase price: 502-905-3708.


Debt-to-Income Ratio (DTI): What FHA Looks At

FHA underwriting looks at housing expense compared to income and total monthly debts compared to income. A common baseline guideline you will see referenced is 31% for housing and 43% for total debt, with exceptions possible depending on automated underwriting results and compensating factors.

  • Housing ratio (front-end): proposed house payment compared to gross monthly income.
  • Total DTI (back-end): house payment plus monthly debts compared to gross monthly income.

If your DTI is tight, the fix is usually one of these: adjust purchase price, restructure debt, improve credit, or document additional qualifying income correctly.


Types of FHA Loans Kentucky Buyers Use Most

FHA 203(b) Standard Purchase

The most common FHA loan for buying a primary residence in Kentucky.

FHA 203(k) Renovation Loan

Combines purchase plus renovation costs into one loan for qualifying homes that need repairs or updates.

FHA Streamline Refinance

For existing FHA borrowers looking to reduce payment with simplified documentation (when eligible).

FHA Cash-Out Refinance

For homeowners who want to access equity (subject to FHA rules and underwriting).

Internal links (recommended):
• VA Loans: Kentucky VA Home Loans
• USDA Loans: Kentucky USDA Zero Down Loans
• KHC Programs: Kentucky Housing (KHC) Loan Programs


KHC Down Payment Assistance (Pairs Well with FHA)

Kentucky Housing Corporation (KHC) offers down payment assistance for eligible borrowers using a KHC first mortgage. KHC’s Regular DAP has been listed as assistance up to $12,500, repayable over 15 years at 4.75% (subject to program terms, eligibility, and availability). Confirm current options here: KHC Down Payment Assistance.

If you want a straight answer on eligibility (income limits, purchase price limits, and which first mortgage fits), call or text me: 502-905-3708.


How to Apply for an FHA Loan in Kentucky (Simple Process)

  1. Quick consult (10 minutes): goals, county, price range, and down payment plan.
  2. Document review: paystubs, W-2s, bank statements, and ID.
  3. Run automated underwriting and issue a clean pre-approval.
  4. Home shopping + contract.
  5. Appraisal, underwriting, and final approval.
  6. Closing and keys.

Primary CTA:
Call or Text 502-905-3708 for FHA Pre-Approval
Email: kentuckyloan@gmail.com

Secondary CTA (site):
Start here: mylouisvillekentuckymortgage.com


FHA FAQ (Kentucky)

Do FHA loans have income limits?

FHA itself does not set income limits. However, down payment assistance programs (like KHC) typically do.

How long does an FHA loan take to close?

Many FHA purchases close in the 30–45 day range, depending on appraisal timing, documentation, and underwriting conditions.

Can the seller pay my closing costs on FHA?

Seller concessions are allowed up to 6% of the sales price toward certain costs when structured correctly. Reference: HUD guidance.

Where can I verify FHA loan limits for my Kentucky county?

Use HUD’s official lookup tool: FHA Mortgage Limits.


About

Joel Lobb — Kentucky Mortgage Loan Officer
NMLS Personal ID: 57916 | Company NMLS: 1738461
Call/Text: 502-905-3708 | Email: kentuckyloan@gmail.com
NMLS Consumer Access: nmlsconsumeraccess.org


Equal Housing Lender
Joel Lobb | NMLS 57916 | Company NMLS 1738461
10602 Timberwood Circle, Louisville, KY 40223
This is an advertisement. Not a commitment to lend. All loan approvals are subject to underwriting guidelines and program eligibility. Terms and conditions apply. Programs, rates, and guidelines are subject to change without notice.
This website is not endorsed by or affiliated with the FHA, VA, USDA, KHC, or any government agency.

Understanding Kentucky FHA DTI Ratios for 2026


Kentucky Mortgage Guide · 2026

Debt-to-Income Ratio
for FHA Loans in Kentucky

How DTI works, what income qualifies & how to get approved — explained simply

1
What Is a Debt-to-Income (DTI) Ratio?

Your Monthly Debts
Car loan, credit cards,
student loans, future
mortgage payment
All recurring obligations
÷
Gross Monthly Income
Pre-tax wages, Social
Security, retirement,
self-employment
Before taxes are deducted

$1,500 monthly debts  ÷  $5,000 gross income  =  30% DTI ✓

2
Two Ratios Lenders Measure

Front-End / Housing Ratio
Housing Payment Only
31%
FHA guideline — AUS can approve higher
→ Principal & Interest
→ Property Taxes (escrow)
→ Homeowner’s Insurance
→ FHA MIP (mortgage insurance)
→ HOA fees (if applicable)
Back-End / Total Debt Ratio
Housing + All Other Debts
43%
Standard max — up to 56.9% with AUS approval
→ Everything in front-end PLUS:
→ Car loans & leases
→ Student loans (min. payment)
→ Credit card minimums
→ Child support paid

3
2026 DTI Limits by Kentucky Loan Program

Loan Program Front-End Back-End AUS Max
FHA
FHA Loan

Min. 3.5% down · 580+ credit
31% 43% 56.9%
VA
VA Loan

Veterans · No down payment required
No limit 41% Flexible
USDA
USDA Rural Housing

Rural Kentucky · No down payment
29% 41% 44%
KHC
KHC (Kentucky Housing Corp.)

Down payment assistance available
Follows Follows Matches underlying FHA/VA/USDA
CON
Conventional (Fannie/Freddie)

3–5% down · Stronger credit required
Flexible 45% 50%

4
Income That Counts Toward Qualifying

💼 
W-2 Wages (Base Salary)
📈 
Overtime & Bonus (2-yr avg)
🏠 
Self-Employment (2-yr returns)
🛡️ 
Social Security & SSI
⚖️ 
Pension & Retirement Income
🎖️ 
VA Disability Benefits
👶 
Child Support Received
🏡 
Rental Income (documented)
🚫 
Cash / Undocumented Income — Does NOT count

5
Real Kentucky Buyer Example — Louisville, KY

👤 Sarah — First-Time Buyer Using an FHA Loan in Louisville, KY
$185,000 purchase price · 3.5% FHA down payment

Income
Gross Monthly Income
$4,200
Monthly Debts
Housing Payment (PITI + MIP)$1,100
Car Loan$320
Student Loan (1% of $18k balance)$180
Credit Card Minimums$55
Total Monthly Debts$1,655

26.2%
Front-End DTI
✓ Under 31% FHA limit

39.4%
Back-End DTI
✓ Under 43% FHA limit — Approved!

6
4 Ways to Improve Your DTI Before Applying

1
Pay Down Small Debts
Eliminating a $75/month minimum directly lowers your back-end DTI. Target accounts with fewer than 10 months remaining — they may drop off entirely.

2
Document All Income Sources
Part-time work, freelance, rental income, and Social Security all count with proper documentation. Missing income = a higher apparent DTI.

3
Choose a Lower Purchase Price
A smaller loan means a smaller payment and better DTI. Many rural Kentucky areas qualify for USDA loans with zero down payment required.

4
Build Compensating Factors
A 620+ credit score, cash reserves, or a 10%+ down payment can unlock FHA automated underwriting approval up to 56.9% DTI.

Get Your Free DTI Analysis Today
Joel Lobb · Kentucky FHA Mortgage Expert · 20+ Years Experience
1,300+ Kentucky Families Helped · FHA · VA · USDA · KHC · Conventional
Down Payment Assistance Available
📞 502-905-3708
kentuckyloan@gmail.com · NMLS #57916
Equal Housing Lender

© 2026 Joel Lobb · Kentucky Mortgage Loans · NMLS #57916 · Company NMLS #1738461 · Not affiliated with FHA, VA, USDA, or any government agency

Kentucky Mortgage Broker Offering FHA, VA, USDA, Conventional, and KHC Down Payment Assistance Home Loans's avatarKentucky First-Time Home Buyer Programs | USDA, FHA, VA & KHC Loans


A debt to income ratio, commonly referred to as DTI, is the ratio of the amount of monthly expenses you have relative to your gross (before tax) income. 


The automated underwriter will look at two ratios when analyzing your DTI: your front end DTI ratio and your back end DTI ratio.


Front End DTI


The front end DTI is the ratio of your new housing payment including taxes and insurance relative to the amount of income you earn.  The front end DTI ratio excludes all other debts and simply analyzes your income relative to the payments on the new mortgage plus tax and insurance. 


So, if your mortgage payments including tax and insurance are $1,000 and you earn $4,000 per month in gross income, your front end DTI would be 25% ($1,000 / $4,000 = 25%). 


Generally, the automated underwriter likes to see front…

View original post 221 more words

Essential Tips for Qualifying for a Mortgage

What You Need To Know About A Mortgage… BEFORE You Get One!!!

Qualifying for a Mortgage

Mortgage companies are in business to make money by lending money that is secured by an asset large enough to sell and recover their capital if the borrower is no longer able or willing to pay the payments. They are not in the business of owning property and would rather not have to foreclose on a loan, repossess the property and sell it to recapture their capital. This does happen but it is not their primary business. They would rather have their borrowers make their payments so that they could collect the interest and move on down the road. To increase their odds of that happening, mortgage companies look at several areas of your financial history to determine if you will meet their standards. This is called Qualifying for a Mortgage.

What the mortgage company finds when they look at these areas will help determine the type of mortgage that is available to you and the interest rate you will pay on the money that you borrow.

The areas that they are interested in looking at are:

Job History

Lenders want to know if you have been in your current job and/or profession for at least two years. They also want to know if you are retired or self-employed.

Income
TaxesMortgage lenders want to know how much your monthly income is before taxes are taken out (Gross Monthly Income). Typically you will be asked to provide check stubs for the last 30 days and Federal Tax Returns or W-2’s for the last two years to prove your income.

If you are self-employed and it is difficult for you to prove your gross income to the lender you may be able to get a “stated income” loan. If that is the route that you take, your income must be “reasonable” for your profession. Since stated income loans are riskier for the lender you will generally have a higher interest rate.

Credit History

Mortgage lenders really like it if you have a history of paying your bills on time. This is reflected in your credit report and FICO score. If you have “bad credit”, you are NOT automatically disqualified from getting a mortgage. Lower credit scores will increase the interest rate that you will be required to pay and sometimes that increase will be quite significant.

Debt Load

You can have an awesome job with an income to make Bill Gates jealous and a great credit score but if you have already acquired too much long term debt you may not qualify for the loan you want.

Assets

Mortgage lenders will want to check your bank accounts to make sure that you have the cash necessary to pay the down payment and closing costs and that you have “reserves” available to make the loan payment. Often, the lender will require 3-6 months reserves. (Reserves can be in a 401K or other retirement account that you can pull the money out of)

Requested Loan Amount

The loan you are requesting will need to be proportional to your ability to make the payments. Be reasonable with your house buying expectations – don’t expect to buy a lot more house than you can afford. The recent housing bust defined the term “house poor” and got a lot of people into financial trouble. Again, mortgage lenders would much rather you make your monthly house payments because everyone loses if they have to foreclose.

Determining YOUR Mortgage Interest Rate

The market place determines the range of interest rates available for any mortgage and the lending rates change daily. The specific interest rate you will pay is based on how well qualified you are and the type of loan you want.

Interest rates are typically based on the answers to these questions:

How Good Is Your Credit Score? 

FICO ScoreThe most widely used score is the FICO score, the credit score created by Fair Isaac Corporation. Lenders use the FICO Score to help them make billions of credit decisions every day. Fair Isaac calculates the FICO Score based solely on information in consumer credit reports maintained by the credit reporting agencies.

FICO credit scores range from 300 to 850. That FICO Score is calculated by a mathematical equation that evaluates many types of information from your credit report, at that agency. By comparing this information to the patterns in hundreds of thousands of past credit reports, the FICO Score estimates your level of future credit risk.

With the top end of the credit score being 850, anything above about 720 is considered excellent. Some local lenders set 740 as the benchmark for their preferred interest rates. Having a lower credit score DOES NOT mean you will not get a loan. You may qualify BUT your interest rate will be higher than someone with better credit.

How Big Is Your Down-Payment?
The Down-Payment is the amount of your own money you are going to put into buying the property. The more money you put into the property on the front end, the lower the risk of you not paying the payments. The amount of your down payment also directly affects the amount of your loan (purchase price – down payment = loan amount). This is called the Loan to Value Ratio (LTV).

The LTV is the percentage of the value of the house that the mortgage will cover (loan amount / purchase price x 100). For example, the property you are interested in buying is selling for $100,000. You have $20,000 for the down-payment and want a mortgage for the other $80,000. The LTV for this mortgage is 80%.

Similar to the LTV is the Combined Loan to Value Ratio (CLTV). The CLTV is used when 2 loans are used to finance the home purchase. You may see or hear terms like “80-20” or “80-15-5”. This refers to the 1st lien percentage (80), the 2nd lien percentage (20 or 15) and the down payment percentage (5).

How Much Debt Do You Currently Have?

It only makes sense that the more debt you have the riskier the loan is for the lender. There is a finite amount of income in all of our households and it all gets allocated every month. Lenders use a “debt-to-income” ratio to determine how qualified you are for the loan based on how much debt you already have.

Your Debt to Income Ratio (DTI) is the percentage of your income that you owe in debt on a monthly basis. For example, if you make $5,000 per month, and have debt payments (car loans, credit cards, student loans, etc.) of $2,000, your DTI ratio is 40%. The higher this ratio is, the less likely you will be to qualify for a low interest rate.

Conventional loans typically have a qualifying ratio of 28/36. FHA loans will sometimes allow for a higher debt load of 29/41 qualifying ratio.

The first number in a qualifying ratio is the maximum percentage of your gross monthly income that can be applied to your mortgage. That includes the loan principal and interest, private mortgage insurance, property taxes, homeowners insurance, and homeowner’s association dues.

The second number is the maximum percentage of your gross monthly income that can be applied to housing expenses and recurring debt. Recurring debt includes monthly payments for cars, boats, motorcycles, child support payments and monthly credit card payments.

 Example:  of a 28/36 qualifying ratio:

Gross monthly income of $5,000 x .28 = $1400 can be applied to housing.

Gross monthly income of $5,000 x .36 = $1,800 can be applied to recurring debt plus housing expenses

Example: of a 29/41 qualifying ratio:

Gross monthly income of $5,000 x .29 = $1,450 can be applied to housing.

Gross monthly income of $5,000 x .41 = $2,050 can be applied to recurring debt plus housing expenses

These are just general guidelines and everyone’s personal finances are unique.
 

Here is a KEY point to remember…

Your credit score is one of the most vital piece of information when qualifying for a loan and you can greatly affect it too. 

Below are the important items I will discuss:

  • What is a credit report?
  • What do mortgage lenders use to determine my credit score?
  • What does FICO stand for?
  • What determines my FICO score?
  • What’s a good FICO score?
  • What if my FICO score is below 620?
  • Can I get a copy of my credit report?
  • Ah Ha! Now I understand all things credit and I’m this much closer to owning my home!

What is a credit report?

A credit report record’s your credit history including information about:

  • Your identity: name, social security number, date of birth and possibly employment information.
  • Your existing credit: credit card accounts, mortgages, car loans, students loans etc.including credit terms, how much you owe, and your payment history.
  • Your public record: Judgments against you, tax liens or bankruptcies.
  • Recent Credit Inquiries: Requests for your information from companies extending credit such as credit card companies, auto loans, etc.

Be aware, credit card companies, car companies and mortgage lenders use slightly different models to determine credit risk. Today we are focusing on Mortgage related credit.

How do lenders calculate my credit score?

Your credit score is the key to your castle. Your home is most likely the most expensive purchase you will ever make. Therefore, when buying a home, lenders use a different system for assessing risk than credit card companies or even auto loan companies use.

Mortgage lenders use a comprehensive system of checking credit called a Residential Mortgage Credit Report (RMCR), commonly called a “Tri-Merge” report. The RMCR report combines your three credit reports from the three national credit bureaus, Equifax, Experian, and TransUnion. Each credit reporting agency calculates your credit score or FICO Score differently. Therefore, pulling from all three bureaus gives lenders a more complete picture of your credit behavior.

Once pulled, lenders use the average of these three scores, usually the middle score, to determine loan qualification and interest rate. For example, if Equifax gives you a 720, Experian a 730 and TransUnion a 740, the lender will use the 730 FICO Score to help determine the terms of your mortgage. If you are applying for a loan jointly, your partner’s three reports will also be pulled.

What does FICO stand for?

FICO stands Fair, Isaac and Company. Over 25 years ago, lenders began using FICO’s scoring model, or algorithm, to fairly and more accurately determine a person’s credit risk. Since it’s inception, FICO’s continually updates its’ algorithms to reflect more current lending trends and consumer behaviors. Today, FICO Scores are used by over 90% of enders. Importantly, your FICO score can impact your loan interest rates, terms, approvals and more.

What determines my FICO score?

A Mortgage FICO score is determined by an algorithm that generally looks at five credit factors including payment history, current level of indebtedness, types of credit used, length of credit history and new credit accounts.

What’s a good FICO score?

To qualify for a conventional loan, most Mortgage lenders require a FICO score of 620+. The best interest rates go to borrowers with a 740+ FICO score. For each 40 point drop, borrowers can expect to see a slightly higher interest rates by about 0.2 percentage points.  If a borrower drops below 660, the increase is likely to be twice as big, a 0.43 percentage point increase. If your credit score is below 620, it is very difficult to get a conventional loan in today’s marketplace. However, don’t be discouraged. You may still be able to buy a home.
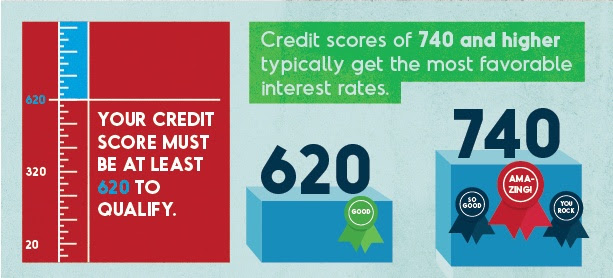
Qualifying Credit Scores for a Kentucky Mortgage Loan

What if my FICO or credit score is below 620?

If your score is below 620, you may still be able to buy a home. There are several options:

  • Put more money down. Some lenders offset a weak credit score with a higher down payment. A higher down payment gives you more equity in your home, lowering the lender’s risk.
  • You may qualify for a non conventional government issued loan such as an FHA, Veterans Affairs and/or U.S. Department of Agriculture loan which have less stringent lending requirements.
  • You may work to get that credit score up!
    • Correct any errors on your report. Analyze your credit items line by line. If you notice a mistake, dispute it right away with either the credit bureau providing the report or the company that providing the incorrect information to the credit bureau.
    • Make all your payments on time. Late payments are the No. 1 way to lower  your credit score.
    • Pay down revolving debt. Keeping your credit balances low helps to raise your score.
    • Sit back and relax. As long as you’re paying down debt and making payments on time, your credit score will eventually rise on its own.

Can I get a copy of my credit report after a lender has pulled it?

Yes! In fact, you can get one free credit report every twelve months from each of the nationwide credit bureaus—Equifax, Experian, and TransUnion. You may also purchase your credit score at any time from any of the credit bureaus. Some Mortgage lenders will tell you your score when you apply for a loan or even give you a copy of your report but they are not required to do so. However, if a lender denies you credit, under the Fair Credit Reporting Act (FCRA) you are entitled to a free copy of your personal credit report if you have received notice that in the past 60 days you have been declined credit.

You ALWAYS get a free copy of your credit report from me.

If you’re ready to buy a new home and want to shop around for the best deal on a mortgage…

Looking for a mortgage, auto or student loan may cause multiple lenders to request your credit report, even though you are only looking for one loan. To compensate for this, the score ignores mortgage, auto, and student loan inquiries made in the 30 days prior to scoring. So, if you find a loan within 30 days, the inquiries won’t affect your score while you’re rate shopping. In addition, the score looks on your credit report for mortgage, auto, and student loan inquiries older than 30 days. If it finds some, it counts those inquiries that fall in a typical shopping period as just one inquiry when determining your score. For FICO scores calculated from older versions of the scoring formula, this shopping period is any 14 day span. For FICO scores calculated from the newest versions of the scoring formula, this shopping period is any 45 day span. Each lender chooses which version of the FICO scoring formula it wants the credit reporting agency to use to calculate your FICO score.

What Type of Loan Are You Looking For?

40 year fixed, 30 year fixed, 20 year fixed, 15 year fixed, 10 Year Fixed, Adjustable Rate, etc. All of these loan types have different interest rate ranges.

Locking Your Interest Rate

Once you have completed a loan application, determined what type of loan you want and qualified for that loan you can “lock” the interest rate for that loan. Locking the Interest Rate means, for the period of the “lock” you are guaranteed that interest rate. Lock periods are typically 15, 30 or 60 days, although you may be able to get an extended lock period.

Once you lock your interest rate:

If you do not close on the loan before the lock period expires, you will NOT have a guaranteed interest rate anymore. And, the longer the lock period, the higher the rate will be. For example, a 15 day lock may be at 5.125%, a 30 day lock at 5.25%, and a 60 day lock at 5.375%. So, before locking your loan, be sure you are not locking for too long a time or for too short a time.

Interest rates fluctuate daily and may go up or down. By locking your rate, you are betting that rates will go up in the future.

 What does “Buying Down” the Interest Rate Mean?

You can reduce the interest rate on your mortgage by paying “points” at closing. A point is 1% of the value of the loan, so a point on a $200,000 loan is $2,000. If you “buy down” you loan to a lower interest rate you will have lower monthly payments and pay less interest over the life of the loan. However, “buying down” you loan to a lower interest rate means more money out of your pocket on the front end when you close the loan. You should do the math and weigh each side of the equation before making a decision about buying down the interest rate or not.
http://www.emailmeform.com/builder/form/0bfJs9b6bK8TGoc6mQk9hIu


What Are The Closing Costs and Fees?

There are four types of closing costs and fees…

Those charged by the mortgage company and/or mortgage broker, those charged by 3rd party vendors, those charged by the Title Company, Escrow Company or Escrow Attorney and Pre-Paid Charges.

Lender Fees

These can include loan origination fees and Broker fees which are usually a percentage of the loan amount; administrative fees and application fees, processing fees and underwriting fees. These last fees usually run from $100 to $500, and ALL of them are negotiable.

3rd Party Vendor charges

These are charges collected by the lender and paid to outside companies that provide a service. These are not usually negotiable and can include appraisal charges, flood certification fees, courier charges, document prep fees, mortgage lender attorney fees, etc.

Title Company charges

These are the fees charged by the Title Company, Escrow Company or Escrow Attorney. They are usually set by the state and are not negotiable. These charges include title insurance, attorney fees, state/county/city registration fees, etc.

Pre-Paid Charges

If the lender will be establishing an escrow account to pay taxes and insurance, the buyer will pre-pay taxes and insurance to establish an escrow account and will pre-pay the interest on the loan until the end of the month in which the loan closes.

 Does The Closing Date Really Matter?

The day you choose to close determines the amount of pre-paid interest you will have to pay. Closing at the end of the month means that you will pay less pre-paid interest. For example, if you close on October 1st you will pay 31 days of pre-paid interest. If you close on October 31st you will pay 1 day of pre-paid interest.

When Is My First Payment Due?

It doesn’t matter what day of the month you close on, you will not have your first loan payment due until a month has passed. So, if you close in October, your first payment is due in December – you get November for free!

What Is PMI?

Private Mortgage Insurance (PMI) is required on all loans that have a LTV greater than 80%. PMI is an insurance premium that you pay every month as part of your monthly payment. However, PMI is not intended to protect you. PMI is insurance coverage that protects the mortgage lender against default on the loan. If you stop making your payments, the mortgage lender is paid a percentage of the loan amount (usually 25% to 35%) by the insurance company.

We suggest that our clients use a local mortgage lender and avoid the big banks. Local lenders provide excellent service, you talk to the same person throughout the loan process, if something is (or isn’t) happening with the loan they can easily check on it with someone right there in their office.

What Other Questions Do You Have?

http://www.emailmeform.com/builder/form/0bfJs9b6bK8TGoc6mQk9hIu

If you have mortgage questions, ask them in the comments section so others will get the answer too.

If you want a personalized answer for your unique situation call, text, or email me.


The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people. NMLS ID# 57916, (http://www.nmlsconsumeraccess.org). Mortgage loans only offered in Kentucky.



Unknown's avatarKentucky First-Time Home Buyer Programs | USDA, FHA, VA & KHC Loans

Financial expert Mark Lamkin explains the best way get your finances in order and start your search.

Source: Five strategies for first time home buyers

kmnj10kdap2017 00% Financing Zero Down Payment Mortgage Loans for Kentucky Home Buyers. For the first First Time Homebuyer, I hope you find this website educational and informative, giving you the confidence when buying your first Kentucky Home. USDA, VA, KHC, and FHA loans all offer $0 Down Home Loan Options-Text or Call for your free application 502-905-3708- Email Kentuckyloan@gmail.com Equal Housing Lender NMLS#57916. This website is not affiliated with any government agency.

unnamed-2 Joel Lobb Senior Loan Officer (NMLS#57916) American Mortgage Solutions, Inc. 10602 Timberwood Circle, Suite 3 Louisville, KY 40223 text or call my phone: (502) 905-3708 email me at kentuckyloan@gmail.com The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not…

View original post 164 more words