MINIMUM CREDIT SCORES REQUIRED FOR KENTUCKY FHA, VA, USDA MORTGAGE LOANS

  1. Kentucky FHA Loans: Kentucky FHA loans are known for their lenient credit score requirements, making them accessible to borrowers with lower credit scores. However, a minimum score of 500 to 580 is typically required, depending on the down payment.

  2. Kentucky VA Loans: VA loans offer flexible credit score requirements, while on paper VA states they don’t require a minimum score to insure the mortgage loan,  most lenders preferring a FICO score of 620 or higher. Veterans, active-duty service members, and eligible spouses can benefit from VA loan options.

  3. Kentucky USDA Loans: USDA loans are designed for rural homebuyers and require no minimum FICO score , but most lenders will want a credit score of 640 or higher. These loans offer zero down payment options for eligible properties.

  4. KHC Mortgage Loans: Kentucky Housing Corporation (KHC) mortgage loans may vary in credit score requirements depending on the lender. It’s essential to work with a knowledgeable mortgage broker like Joel Lobb to understand specific lender guidelines. KHC requires a minimum 620 credit score for FHA, VA, USDA and 660 for Conventional loan programs 


Text/call: 502-905-3708

email:
 kentuckyloan@gmail.com

http://www.mylouisvillekentuckymortgage.com/

Credit Score Requirements for Kentucky Home Buyers

What Credit Score Do You Need to Buy a House in Kentucky?

There is no single “magic number.” The credit score needed depends on the loan program (Conventional, USDA, FHA, VA, or Kentucky Housing Corporation down payment assistance). Here’s how it works in the real world for Kentucky buyers.

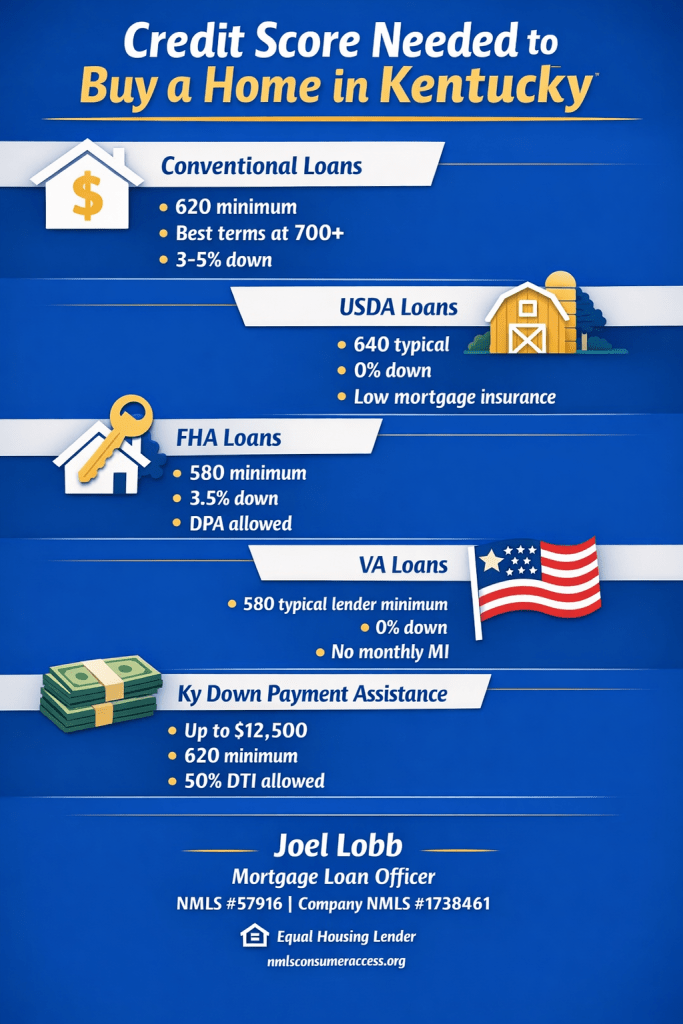
Credit Score Needed to Buy a Home in Kentucky infographic showing Conventional 620+, USDA 640 typical, FHA 580+, VA 580 typical lender minimum, and KY down payment assistance up to $12,500.
Quick guide: typical credit score ranges and key highlights by Kentucky mortgage program.

Conventional Loans in Kentucky

  • Minimum credit score generally starts at 620.
  • Most lenders prefer higher scores for 3%–5% down options.
  • Best pricing and easier approvals are typically with strong credit (often 700+).
  • Mortgage insurance (PMI) usually improves as scores increase.

USDA Rural Housing Loans in Kentucky

  • Many lenders target around 640 for automated approval through GUS (Guaranteed Underwriting System).
  • Manual underwriting may be possible when automated approval is not available.
  • 0% down payment required (eligible rural/suburban areas).
  • Typical fees include a 1% upfront guarantee fee and 0.35% annual fee (paid monthly).

USDA can be one of the best value options for Kentucky buyers with limited cash, provided the property is in an eligible area and the file meets income and underwriting requirements.

Kentucky FHA Loans

  • As low as 580 credit score with 3.5% down (typical baseline).
  • Gift funds, grants, and down payment assistance may be allowed.
  • Mortgage insurance is generally higher than USDA or VA, but rates can still be competitive.
  • Common waiting periods: 2 years after bankruptcy and 3 years after foreclosure (standard guideline).

Kentucky VA Loans

  • VA does not set a minimum credit score in its guidelines, but most lenders do.
  • Many VA lenders target around 580+ (lender overlay varies).
  • 0% down and no monthly mortgage insurance.
  • Clear CAIVRS is required (for federal delinquency screening).

Kentucky Down Payment Assistance (KHC)

  • Kentucky Housing Corporation (KHC) often offers up to $12,500 down payment assistance (program terms and funding can change).
  • Typically structured as a second mortgage paid back over 15 years.
  • Minimum credit score is commonly 620 across many KHC options; KHC conventional often requires 660.
  • Maximum debt-to-income ratios are commonly around 50/50 (program and investor rules apply).

Next step: get a clear pre-approval target

If you share your approximate credit score range, income type, and whether you’re looking in Louisville, Lexington, or rural Kentucky, I can point you to the most realistic program and the exact score threshold that will matter for approval.

Get Preapproved See $12,500 KHC Options


Joel Lobb, Mortgage Loan Officer

NMLS #57916 | Company NMLS #1738461

Equal Housing Lender | Verify at nmlsconsumeraccess.org

{ “@context”: “https://schema.org”, “@type”: “FAQPage”, “mainEntity”: [ { “@type”: “Question”, “name”: “What credit score do I need to buy a house in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “It depends on the loan program. Conventional financing often starts around 620, USDA lenders commonly target about 640 for automated approval, FHA can allow down to 580 with 3.5% down, and many VA lenders look for around 580 even though VA does not publish a minimum score. Kentucky Housing Corporation down payment assistance commonly requires around 620 (and KHC conventional often around 660). Final approval also depends on income, debt-to-income ratio, and underwriting findings.” } }, { “@type”: “Question”, “name”: “Can I buy a home in Kentucky with a 580 credit score?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “Often yes, depending on the full file. FHA commonly allows 580 with 3.5% down and can work well when you have limited savings or are using gift funds or down payment assistance. Lender overlays and underwriting results still apply.” } }, { “@type”: “Question”, “name”: “Is 640 a good credit score for a Kentucky mortgage?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “A 640 score can be workable for several programs. USDA lenders often target around 640 for automated approvals, and conventional approvals may be possible starting at 620, though terms improve as scores rise. Your debt-to-income ratio, income stability, and cash to close will strongly influence results.” } }, { “@type”: “Question”, “name”: “What credit score do I need for a USDA loan in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “Many lenders prefer around 640 to obtain an automated approval through the USDA Guaranteed Underwriting System (GUS). Manual underwriting may be possible in some cases, but it is typically more restrictive on ratios and documentation.” } }, { “@type”: “Question”, “name”: “Does the VA require a minimum credit score in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “VA guidelines do not publish a minimum credit score, but lenders usually do. Many VA lenders commonly target around 580 or higher, depending on the overall file and lender overlays.” } }, { “@type”: “Question”, “name”: “What credit score is needed for Kentucky Housing Corporation (KHC) down payment assistance?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “KHC program requirements vary, but a common minimum is around 620 for many options. KHC conventional commonly requires around 660. Eligibility also depends on income limits, purchase price limits, and underwriting findings.” } } ] }
What Credit Score Do You Need to Buy a House in Kentucky?

Kentucky FHA Loan Employment History Requirements

  • No matter what you must provide a 2 year employment history. Conventional or Kentucky FHA Mortgage Loan.  Conventional does not always need to be verified with a written work verification form
    • if you do not have a complete 2 year history you must explain any large gaps.  Typically I have seen this to be greater than 30 days.
    • you must have a 2 year history prior to the gap as well.  (two underwriters from two different lenders have recently told me the same thing)
    • also check your AUS-Automated Underwriting Findings  because that can help when speaking with your potential borrower.
    •  
  • Exception to the 2 year history is college or HS graduation
    • need official college transcripts or they can be unofficial if you get them with the web URL just like bank activity.
    • good idea to snag their diploma as well.
    •  
    • you probably don’t even need to use this exception if the person was a student but also worked and had a 2 year job history.
  •  Kentucky FHA Case Number Assignment
    • if there are any job gaps greater than 6 months in their two year history the borrower must be on their current job for at least 6 months before the FHA case number can be assigned.
    • again you must then get a 2 year employment history prior to the 6 month or more gap.  however far you must go back.
    •  
  •  
  • W2s / 1099s
    • even if you are not using the income to qualify from a part time job please get every single w2 / 1099 from your borrowers.  

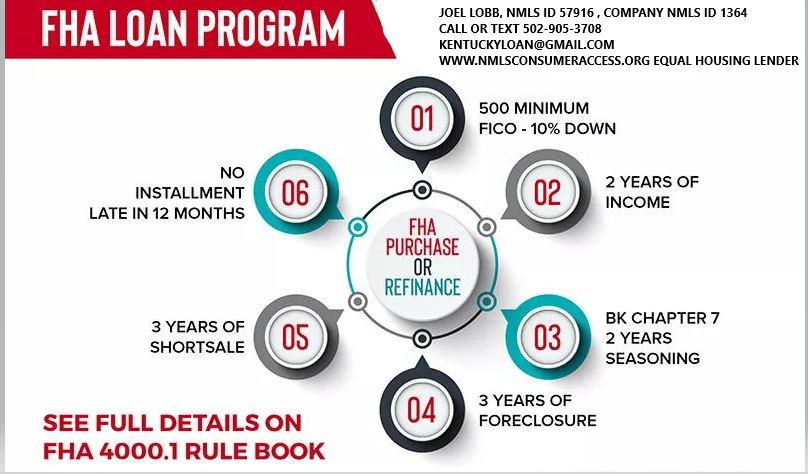
fha pic

 
Kentucky FHA Mortgage Work History and Income Requirements.

1 –  Email – kentuckyloan@gmail.com 2.   Call/Text – 502-905-3708

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans


🌐 Websitewww.mylouisvillekentuckymortgage.com
🏢 Address911 Barret Ave., Louisville, KY 40204


Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.

Best Mortgage Options: Kentucky VA, FHA, USDA, and Fannie Mae

Comparing Kentucky VA loans to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky

Kentucky VA loans Compared to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky

When comparing Kentucky VA loans to Kentucky USDA, FHA, and Fannie Mae loans in Kentucky, several factors come into play. These factors include credit score requirements, income considerations, work history, and debt ratios. They also involve how each loan type treats bankruptcy and foreclosure. Let’s delve into the benefits and differences of each loan type:

Kentucky Mortgage Credit Score Requirements:

  • Kentucky VA Loan: VA loans typically have more flexible credit score requirements compared to conventional loans. While there’s no specific minimum score set by VA , most Kentucky VA lenders often look for a credit score of 620 or higher. I can do VA loans down to a 580 credit score.
  • Kentucky USDA Loan: USDA loans also offer flexibility, with no minimum score required per USDA guidelines, but most Kentucky USDA lenders will want a 640 score or higher. I Can do Kentucky USDA loans down to a 580 credit score on a manual underwrite.
  • Kentucky FHA Loan: FHA loans are known for accommodating borrowers with lower credit scores, often accepting scores as low as 500 with a 10% down payment or 580 with a 3.5% down payment.
  • Kentucky Fannie Mae Loan: Fannie Mae loans usually require a minimum credit score of 620 or higher, although some lenders may have slightly different requirements.

Kentucky Mortgage Income and Work History:

  • Kentucky VA Loan: VA loans consider your stable income and employment history but may be more lenient if you have a history of military service or steady employment. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky USDA Loan: USDA loans often have income limits based on the area’s median income, and you need a stable income source. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky FHA Loan: FHA loans consider your income stability and work history, with guidelines that vary by lender. 2 years of employment needed for loan application-minimal job gaps
  • Kentucky Fannie Mae Loan: Fannie Mae loans typically require a stable income and employment history, similar to conventional loans. 2 years of employment needed for loan application-minimal job gaps

Kentucky Mortgage Debt Ratio Requirements:

  • Kentucky VA Loan: VA loans generally have more lenient debt-to-income (DTI) ratio requirements, often allowing for a higher DTI compared to conventional loans. VA loans can get approved on much higher debt to income ratios vs FHA, USDA and Fannie Mae loans. 65% or higher in some situations but if manual underwrite, will want the ratios closer to 41% with good residual income for VA loan. VA loans are the only type of loans that require a residual income…FHA, Fannie Mae, USDA does not have residual income requirements
  • Kentucky USDA Loan: USDA loans have very strict DTI ratio limits, typically around 41% to 45% max on the backend ratio and 33% or less on the front end. By far the most restrictive on debt ratios vs FHA, VA, and Fannie Mae loans
  • Kentucky FHA Loan: FHA loans also have relatively flexible DTI ratio limits (56% back end ratio possible on a AUS approval), making them accessible to borrowers with moderate levels of debt. Front end ratio max 45%
  • Fannie Mae Loan: Fannie Mae loans follow standard DTI ratio guidelines similar to conventional loans. TYpically the second most restrictive on debt ratios right behind USDA loans on tighter debt to income ratio requirements, with the max back-end ratio no more than 50% –Front end ratio max 45%

Kentucky Mortgage Bankruptcy and Foreclosure Requirements:

  • Kentucky VA Loan: VA loans are more forgiving of past bankruptcy or foreclosure, often requiring a waiting period of 2 years for Chapter 7 bankruptcy and 1-2 years for foreclosure.
  • Kentucky USDA Loan: USDA loans have specific waiting periods after bankruptcy (3 years for Chapter 7) and foreclosure (3 years).
  • Kentucky FHA Loan: FHA loans have shorter waiting periods after bankruptcy (2 years for Chapter 7) and foreclosure (3 years).
  • Kentucky Fannie Mae Loan: Fannie Mae loans typically require longer waiting periods after bankruptcy (4-7 years) and foreclosure (7 years).

Advantages and Disadvantages of Kentucky VA loans, USDA, Fannie Mae and FHA:

  • Kentucky VA Loan Advantages: Zero down payment, competitive interest rates, no private mortgage insurance (PMI) requirement, lenient credit and DTI ratios, and flexible eligibility criteria for veterans and active-duty service members.
  • Kentucky VA Loan Disadvantages: Funding fee (although it can be rolled into the loan), limited to eligible veterans, service members, and some spouses.
  • Kentucky USDA Loan Advantages: Zero down payment, lower interest rates, flexible credit requirements, and available in eligible rural areas.
  • Kentucky USDA Loan Disadvantages: Limited to rural properties, income limits, and property eligibility criteria.
  • Kentucky FHA Loan Advantages: Low down payment (3.5%), flexible credit requirements, competitive interest rates, and accessible to first-time homebuyers.
  • Kentucky FHA Loan Disadvantages: Mortgage insurance premiums (MIP), stricter property standards, and limits on loan amounts.
  • Kentucky Fannie Mae Loan Advantages: Available for a wide range of properties, competitive interest rates, and options for low down payments.
  • Kentucky Fannie Mae Loan Disadvantages: Stricter credit and DTI requirements, potential for private mortgage insurance (PMI), and limited flexibility for borrowers with past financial challenges.

In summary, choosing the right loan type depends on your specific financial situation, eligibility criteria, and property location. VA loans offer excellent benefits for eligible veterans and service members, while USDA, FHA, and Fannie Mae loans provide alternatives with their own advantages and considerations.

Joel Lobb  Mortgage Loan Officer

Text/call: 502-905-3708
email: kentuckyloan@gmail.com

http://www.mylouisvillekentuckymortgage.com/

Kentucky FHA Manual Underwriting Explained

KENTUCKY FHA MORTGAGE MANUAL UNDERWRITING GUIDELINES FOR VA RESIDUAL INCOME

Kentucky FHA Mortgage  Manual Undewriting Guidelines for FHA Mortgage Refer Eligible or Manual Downgrades

Continue reading “Kentucky FHA Manual Underwriting Explained”