
How to qualify for a Kentucky FHA Home Loan ?

How to qualify for a Kentucky FHA Home Loan ?

Image result for fha loans ky


FHA stands for the Federal Housing Administration which is a government agency created to increase home-ownership across the United States all the way back in 1934. The agency itself doesn’t offer home loans but insures loan that are offered by private lenders (i.e. mortgage companies).

It’s important to understand the different types of loan programs available to you and what benefits and drawbacks there are to each type.

For example, if you’re looking to find a fixer upper this may not be the right loan program for you. But an FHA loan may be a better fit for you if you have little cash saved up for a down payment or if you don’t have a high credit score.

Kentucky FHA loan requirements:

  • At least 18 years old to apply
  • No age limit. just must be 18 years of age to apply.
  • Must occupy the home as a primary residence, no rental homes or investment property
  • An appraisal must be done by an FHA-approved appraiser.Typically FHA appraisal in Kentucky costs anywhere from low-end $325 to $525 with most FHA lenders in KY.
  • Home inspection is not required
  • Termite inspection not required
  • 2 years removed from Chapter 7 bankruptcy, and 1 year in Chapter 13 bankruptcy is possible to get a loan while in bankruptcy
  • Foreclosure or short sale on previous home mortgage requires 3 years removal from those dates.
  • Mortgage insurance (MIP) is required
  • Upfront Mortgage Insurance Premium is 1.75% and monthly mortgage insurance is .85% or .80% depending on loan term and loan to value.
  • Mortgage insurance is for life of loan.
  • No matter your credit scores, everyone pays the same mortgage insurance premiums.
  • Must have 2 years of employment history proving a reliable source of income
  • 500 FICO score requirement with at least 10% down payment
  • 580 FICO score requirement with at least 3.5% down payment
  • Gifts and down payment assistance programs are allowed to meet your down payment requirements. Cannot come from seller, but seller can contribute up to 6% of the sales price toward buyer’s closing costs and prepaids.
  • Student loan payments are factored into the debt-to-income ratio when applying. Typically if loans are deferred, or in an income=based repayment plan, the FHA underwriters will use 1% of the outstanding balance, which sometimes can make it difficult to qualify.
  • Your debt-to-income ratio must not be higher than 31% or total debt obligation cannot be higher than 43% of your current income. This is for a manual underwriter, meaning that if the AUS underwriting system by mortgage lenders will approve you for a higher debt to income ratio, that is fine.


Joel Lobb (NMLS#57916)
Senior  Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346

Text/call 502-905-3708kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.
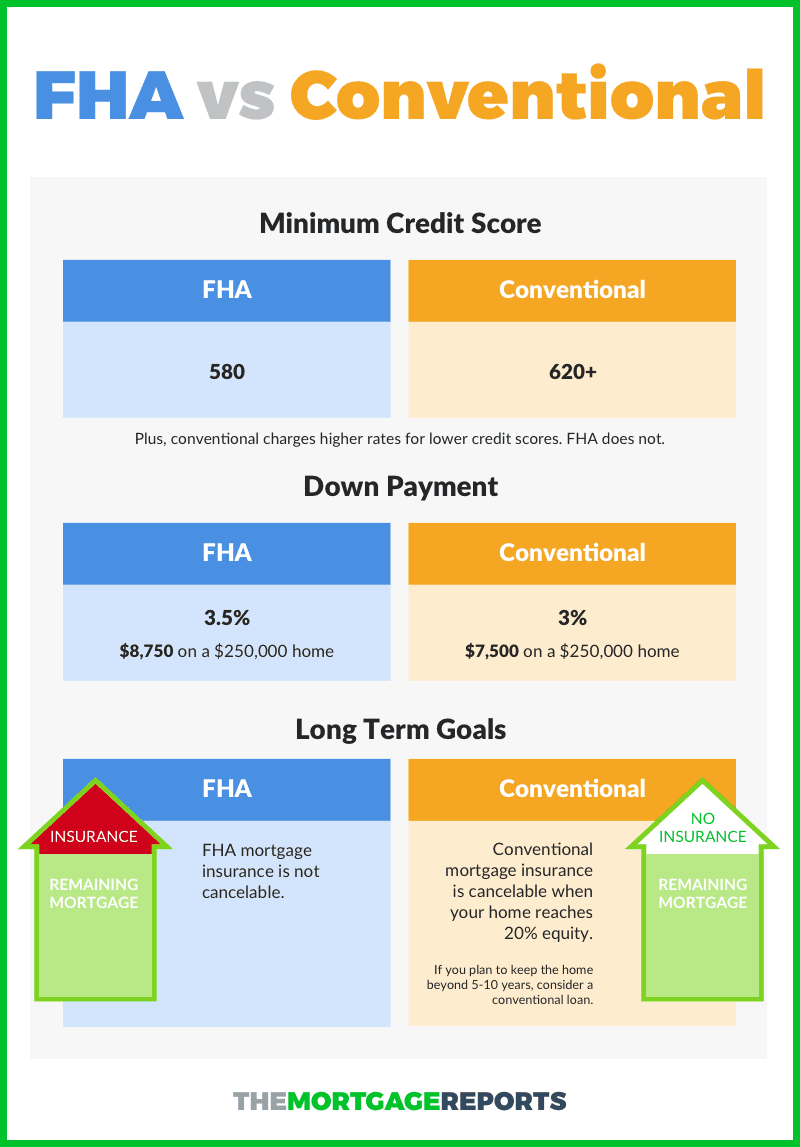
FHA vs Conventional Infograhic

How long do you have to wait to get approved for a mortgage loan after a bankruptcy in Kentucky?

GETTING A MORTGAGE LOAN IN KENTUCKY WHEN YOU HAVE HAD A BANKRU
ARE YOU CURRENTLY IN A CHAPTER 13 BANKRUPTCY OR HAD A CHAPTER 7 BANKRUPTCY IN THE PAST?

Qualifying For A Kentucky Mortgage After Bankruptcy

Home Buyers can qualify for a Kentucky mortgage after bankruptcy:

  • 2 year waiting period to qualify for FHA Loan to qualify for a FHA Loans after discharge of Chapter 7.
  • One year into a Chapter 7 Bankruptcy to qualify for a Chapter Loan into a Chapter 13 Bankruptcy repayment plan.
  • No waiting period after a Chapter 13 Bankruptcy discharge date.
  • 4 year waiting period to qualify for a Chapter 7 Bankruptcy discharge date to qualify for a Conventional Loan.
  • Two year waiting period to qualify for a Chapter 13 after Chatper 13 discharged date to qualify for a Conventional Loan.
  • Four year waiting period to qualify for a Conventional Loan if you had a mortgage part of bankruptcy but the foreclosure needs to be be finalized

Bankruptcy Chart for FHA, VA, USDA and Fannie Mae Guidelines for Chapter 7, Chapter 13 and Foreclosure and Short Sale

Joel Lobb (NMLS#57916)
Senior  Loan Officer
 
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708
kentuckyloan@gmail.com

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender.

Kentucky FHA loans after a bankruptcies, foreclosures, deeds-in-lieu of foreclosure, pre-foreclosures, short sales, and mortgage charge-offs.

Kentucky FHA loans after a significant derogatory credit events which include bankruptcies, foreclosures, deeds-in-lieu of foreclosure, pre-foreclosures, short sales, and mortgage charge-offs.

A Chapter 7 bankruptcy – MUST be discharged at least 2 years from Case Number Assignment Date. Requirements
include:
1. Complete Copy of Bankruptcy paperwork MUST be provided
2. Borrower must write a detailed explanation explaining the reason for the Bankruptcy
3. The Borrower must have re-established good credit; or chosen not to incur new credit obligations.
4. An elapsed period of less than two years, but not less than 12 months, may be acceptable, if the Borrower:
– Can show that the bankruptcy was caused by extenuating circumstances beyond the Borrower’s control; and
– Has since exhibited a documented ability to manage their financial affairs in a responsible manner.
– If a Chapter 7 is discharged less than 2 years from the date of Case Number Assignment Date the loan must be downgraded to Manual Underwriting and meet all requirements listed in HUD 4000.1 Handbook


Chapter 13 must be discharged ** Requirements include:
1. Complete Copy of Bankruptcy paperwork MUST be provided
2. Borrower must write a detailed explanation explaining the reason for the Bankruptcy
3. The Borrower must have re-established good credit; or chosen not to incur new credit obligations.
4. An elapsed period of less than two years, but not less than 12 months, may be acceptable, if the Borrower:
‐ Can show that the bankruptcy was caused by extenuating circumstances beyond the Borrower’scontrol; and
‐ Has since exhibited a documented ability to manage their financial affairs in a responsible manner.

5. If a Chapter 13 is discharged less than 2 years from the date of Case Number Assignment Date the loan must be downgraded to Manual Underwriting and meet all requirements listed in HUD 4000.1 Handbook

Foreclosure/Deed-in-Lieu
1. A Borrower is generally not eligible for a new FHA-insured Mortgage if the Borrower had a foreclosure or a DIL of foreclosure in the three-year period prior to the date of Case Number Assignment.
2. This three-year period begins on the date of the DIL or the date that the Borrower transferred ownership of the Property to the foreclosing Entity/designee.

Short Sale

1. A Borrower is generally not eligible for a new FHA-insured Mortgage if they relinquished a Property through a Short Sale within three years from the date of Case Number Assignment.
2. The three-year period begins on the date of transfer of title by Short Sale.

Inline image 2


Inline image 1

Kentucky FHA Loan

FHA loans are good for home buyers with lower credit scores and no much down, or with down payment assistance grants. FHA will allow for grants, gifts, for their 3.5% minimum investment and will go down to a 580 credit score.

The current mortgage insurance requirements are kinda steep when compared to USDA, VA , but the rates are usually good so it can counteract the high mi premiums. As I tell borrowers, you will not have the loan for 30 years, so don’t worry too much about the mi premiums.

The mi premiums are for life of loan like USDA.

FHA requires 2 years removed from bankruptcy and 3 years removed from foreclosure.

Maximum FHA loan limits in Kentucky are set around $285,000 -$299,000 depending on the county in Kentucky

Joel Lobb
Senior Loan Officer
(NMLS#57916)

American Mortgage Solutions, Inc.
10602 Timberwood Circle, Suite 3
Louisville, KY 40223

text or call my phone: (502) 905-3708
email me at kentuckyloan@gmail.com

The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people. NMLS ID# 57916, (www.nmlsconsumeraccess.org). Mortgage loans only offered in Kentucky.
All loans and lines are subject to credit approval, verification, and collateral evaluation and are originated by lender. Products and interest rates are subject to change without notice.

Joel E Lobb
American Mortgage
5029053708
email us here

Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

Kentucky FHA, VA, USDA & Rural Housing, KHC and Fannie Mae mortgage loans.

Kentucky FHA Loan Guidelines for Foreclosure and Short Sale

Kentucky FHA Loan Guidelines After Bankruptcy, Foreclosure, or Short Sale

If you’ve experienced a bankruptcy, foreclosure, or short sale in the past, you may still be able to qualify for a Kentucky FHA loan. Here are the current waiting period guidelines you need to know:

  • Foreclosure: 3-year waiting period from the foreclosure completion date (when the property is transferred back to the lender) as reported on your credit report.
  • Short Sale: 3-year waiting period from the title transfer date.
  • Chapter 7 Bankruptcy: 2-year waiting period from the discharge date. Note: If a property was surrendered in the Chapter 7 bankruptcy, it may be treated as a foreclosure, which could extend the waiting period.
  • Chapter 13 Bankruptcy: 1-year wait with a scheduled payment plan, provided the liabilities are factored into your debt-to-income ratio and bankruptcy court approval is obtained — OR 2 years from the discharge date.

Don’t let past financial hardships stop you from achieving the dream of homeownership. I’ve helped hundreds of Kentucky families in similar situations successfully get approved for FHA loans. Reach out today — let’s talk about your options.


Joel Lobb
Mortgage Loan Officer — Kentucky FHA Loan Expert
NMLS #57916 | Company NMLS #1738461

📞 (502) 905-3708 — Call or Text
📧 kentuckyloan@gmail.com
🌐 www.mylouisvillekentuckymortgage.com

Equal Housing Lender. Kentucky Mortgage Loans Only.

FHA Back to Work Extenuating Circumstances Works!

FHA Back to Work Extenuating Circumstances Works, FHA Back to Work Program, Success Story, FHA Loans

via FHA Back to Work Extenuating Circumstances Works!.