MINIMUM CREDIT SCORES REQUIRED FOR KENTUCKY FHA, VA, USDA MORTGAGE LOANS

  1. Kentucky FHA Loans: Kentucky FHA loans are known for their lenient credit score requirements, making them accessible to borrowers with lower credit scores. However, a minimum score of 500 to 580 is typically required, depending on the down payment.

  2. Kentucky VA Loans: VA loans offer flexible credit score requirements, while on paper VA states they don’t require a minimum score to insure the mortgage loan,  most lenders preferring a FICO score of 620 or higher. Veterans, active-duty service members, and eligible spouses can benefit from VA loan options.

  3. Kentucky USDA Loans: USDA loans are designed for rural homebuyers and require no minimum FICO score , but most lenders will want a credit score of 640 or higher. These loans offer zero down payment options for eligible properties.

  4. KHC Mortgage Loans: Kentucky Housing Corporation (KHC) mortgage loans may vary in credit score requirements depending on the lender. It’s essential to work with a knowledgeable mortgage broker like Joel Lobb to understand specific lender guidelines. KHC requires a minimum 620 credit score for FHA, VA, USDA and 660 for Conventional loan programs 


Text/call: 502-905-3708

email:
 kentuckyloan@gmail.com

http://www.mylouisvillekentuckymortgage.com/

Credit Score Requirements for Kentucky Home Buyers

What Credit Score Do You Need to Buy a House in Kentucky?

There is no single “magic number.” The credit score needed depends on the loan program (Conventional, USDA, FHA, VA, or Kentucky Housing Corporation down payment assistance). Here’s how it works in the real world for Kentucky buyers.

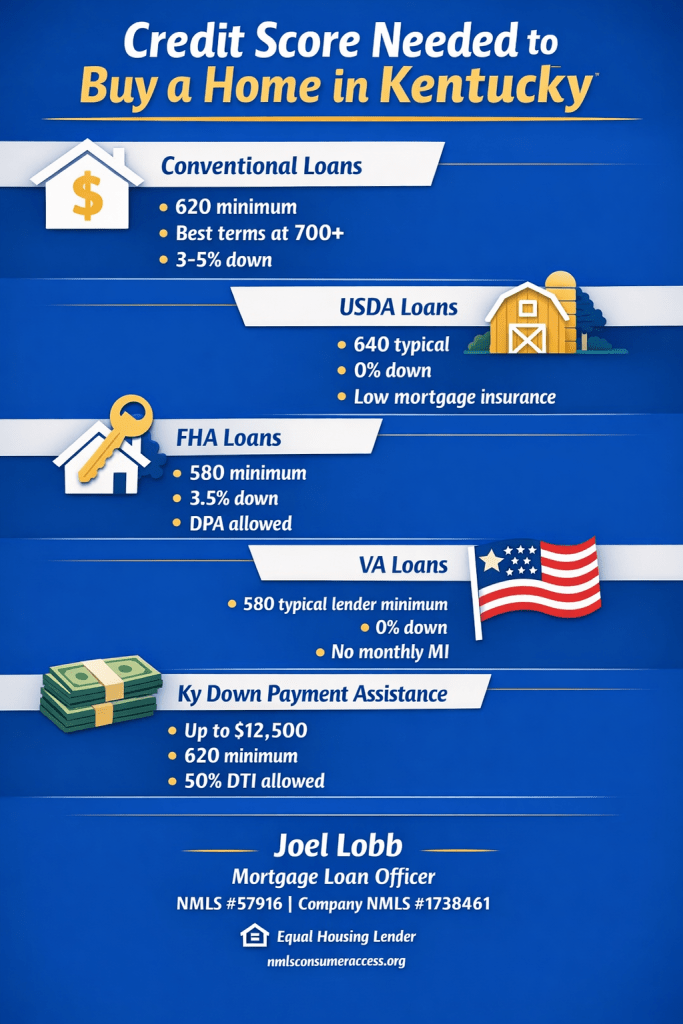
Credit Score Needed to Buy a Home in Kentucky infographic showing Conventional 620+, USDA 640 typical, FHA 580+, VA 580 typical lender minimum, and KY down payment assistance up to $12,500.
Quick guide: typical credit score ranges and key highlights by Kentucky mortgage program.

Conventional Loans in Kentucky

  • Minimum credit score generally starts at 620.
  • Most lenders prefer higher scores for 3%–5% down options.
  • Best pricing and easier approvals are typically with strong credit (often 700+).
  • Mortgage insurance (PMI) usually improves as scores increase.

USDA Rural Housing Loans in Kentucky

  • Many lenders target around 640 for automated approval through GUS (Guaranteed Underwriting System).
  • Manual underwriting may be possible when automated approval is not available.
  • 0% down payment required (eligible rural/suburban areas).
  • Typical fees include a 1% upfront guarantee fee and 0.35% annual fee (paid monthly).

USDA can be one of the best value options for Kentucky buyers with limited cash, provided the property is in an eligible area and the file meets income and underwriting requirements.

Kentucky FHA Loans

  • As low as 580 credit score with 3.5% down (typical baseline).
  • Gift funds, grants, and down payment assistance may be allowed.
  • Mortgage insurance is generally higher than USDA or VA, but rates can still be competitive.
  • Common waiting periods: 2 years after bankruptcy and 3 years after foreclosure (standard guideline).

Kentucky VA Loans

  • VA does not set a minimum credit score in its guidelines, but most lenders do.
  • Many VA lenders target around 580+ (lender overlay varies).
  • 0% down and no monthly mortgage insurance.
  • Clear CAIVRS is required (for federal delinquency screening).

Kentucky Down Payment Assistance (KHC)

  • Kentucky Housing Corporation (KHC) often offers up to $12,500 down payment assistance (program terms and funding can change).
  • Typically structured as a second mortgage paid back over 15 years.
  • Minimum credit score is commonly 620 across many KHC options; KHC conventional often requires 660.
  • Maximum debt-to-income ratios are commonly around 50/50 (program and investor rules apply).

Next step: get a clear pre-approval target

If you share your approximate credit score range, income type, and whether you’re looking in Louisville, Lexington, or rural Kentucky, I can point you to the most realistic program and the exact score threshold that will matter for approval.

Get Preapproved See $12,500 KHC Options


Joel Lobb, Mortgage Loan Officer

NMLS #57916 | Company NMLS #1738461

Equal Housing Lender | Verify at nmlsconsumeraccess.org

{ “@context”: “https://schema.org”, “@type”: “FAQPage”, “mainEntity”: [ { “@type”: “Question”, “name”: “What credit score do I need to buy a house in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “It depends on the loan program. Conventional financing often starts around 620, USDA lenders commonly target about 640 for automated approval, FHA can allow down to 580 with 3.5% down, and many VA lenders look for around 580 even though VA does not publish a minimum score. Kentucky Housing Corporation down payment assistance commonly requires around 620 (and KHC conventional often around 660). Final approval also depends on income, debt-to-income ratio, and underwriting findings.” } }, { “@type”: “Question”, “name”: “Can I buy a home in Kentucky with a 580 credit score?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “Often yes, depending on the full file. FHA commonly allows 580 with 3.5% down and can work well when you have limited savings or are using gift funds or down payment assistance. Lender overlays and underwriting results still apply.” } }, { “@type”: “Question”, “name”: “Is 640 a good credit score for a Kentucky mortgage?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “A 640 score can be workable for several programs. USDA lenders often target around 640 for automated approvals, and conventional approvals may be possible starting at 620, though terms improve as scores rise. Your debt-to-income ratio, income stability, and cash to close will strongly influence results.” } }, { “@type”: “Question”, “name”: “What credit score do I need for a USDA loan in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “Many lenders prefer around 640 to obtain an automated approval through the USDA Guaranteed Underwriting System (GUS). Manual underwriting may be possible in some cases, but it is typically more restrictive on ratios and documentation.” } }, { “@type”: “Question”, “name”: “Does the VA require a minimum credit score in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “VA guidelines do not publish a minimum credit score, but lenders usually do. Many VA lenders commonly target around 580 or higher, depending on the overall file and lender overlays.” } }, { “@type”: “Question”, “name”: “What credit score is needed for Kentucky Housing Corporation (KHC) down payment assistance?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “KHC program requirements vary, but a common minimum is around 620 for many options. KHC conventional commonly requires around 660. Eligibility also depends on income limits, purchase price limits, and underwriting findings.” } } ] }
What Credit Score Do You Need to Buy a House in Kentucky?

FHA, VA, USDA, and Kentucky Housing Corporation (KHC) down payment assistance programs with Joel Lobb’s expertise

Credit score requirements for FHA, VA, USDA, and Fannie Mae loans in Kentucky

Understanding Credit Score Requirements for Mortgage Loans in Kentucky

Are you considering buying a home in the beautiful state of Kentucky? Securing a mortgage loan is a crucial step in the homebuying process, and one of the key factors lenders evaluate is your credit score. Understanding the credit score requirements for mortgage loan approval in Kentucky can help you prepare and improve your chances of securing financing for your dream home.

Importance of Credit Scores

Your credit score is a numerical representation of your creditworthiness based on your credit history. Lenders use this score to assess the risk of lending to you. A higher credit score typically indicates lower risk to lenders, making you more likely to qualify for a mortgage loan and secure better terms and interest rates.

Credit Score Requirements in Kentucky

While specific credit score requirements can vary among lenders and mortgage programs, there are some general guidelines to consider when applying for a mortgage loan in Kentucky.

  1. Conventional Loans: Conventional mortgage loans are not insured or guaranteed by the government. Many lenders prefer borrowers to have a credit score of at least 620 to qualify for a conventional loan. However, some lenders may require higher scores, especially for competitive interest rates.
  2. FHA Loans: The Federal Housing Administration (FHA) offers loans with more lenient credit score requirements compared to conventional loans. In Kentucky, borrowers may be eligible for an FHA loan with a credit score as low as 500, provided they can make a 10% down payment. A credit score of 580 or higher may qualify for a lower down payment option of 3.5%.
  3. VA Loans: If you’re a veteran, active-duty service member, or eligible spouse, you may qualify for a VA loan guaranteed by the Department of Veterans Affairs. VA loans typically have more flexible credit score requirements, and some lenders may consider borrowers with credit scores below 620.
  4. USDA Loans: The U.S. Department of Agriculture (USDA) offers loans to eligible rural and suburban homebuyers with low to moderate incomes. Credit score requirements for USDA loans in Kentucky can vary, but many lenders prefer scores of 640 or higher.

Tips for Improving Your Credit Score

If your credit score is below the desired threshold for a mortgage loan, don’t despair. There are steps you can take to improve your creditworthiness over time:

  • Check Your Credit Report: Obtain a free copy of your credit report from each of the three major credit bureaus—Equifax, Experian, and TransUnion—and review them for errors or discrepancies.
  • Pay Bills on Time: Your payment history is one of the most significant factors affecting your credit score. Make sure to pay all your bills, including credit cards, loans, and utilities, on time.
  • Reduce Credit Card Balances: Aim to keep your credit card balances low relative to your credit limits. High credit utilization can negatively impact your credit score.
  • Avoid Opening New Credit Accounts: While having a mix of credit accounts can be beneficial, opening multiple new accounts within a short period can lower your credit score.

Conclusion

In Kentucky, credit score requirements for mortgage loans can vary depending on the type of loan and lender you choose. While higher credit scores generally improve your chances of loan approval and favorable terms, there are loan programs available for borrowers with less-than-perfect credit.

Before applying for a mortgage loan, it’s essential to review your credit report, understand your credit score, and take steps to improve it if necessary. By demonstrating responsible financial behavior and maintaining a good credit history, you can increase your likelihood of securing a mortgage loan and achieving your homeownership goals in Kentucky.