Kentucky FHA Loans in the State of Kentucky for 2022

Advantages of Kentucky FHA Mortgage Loans

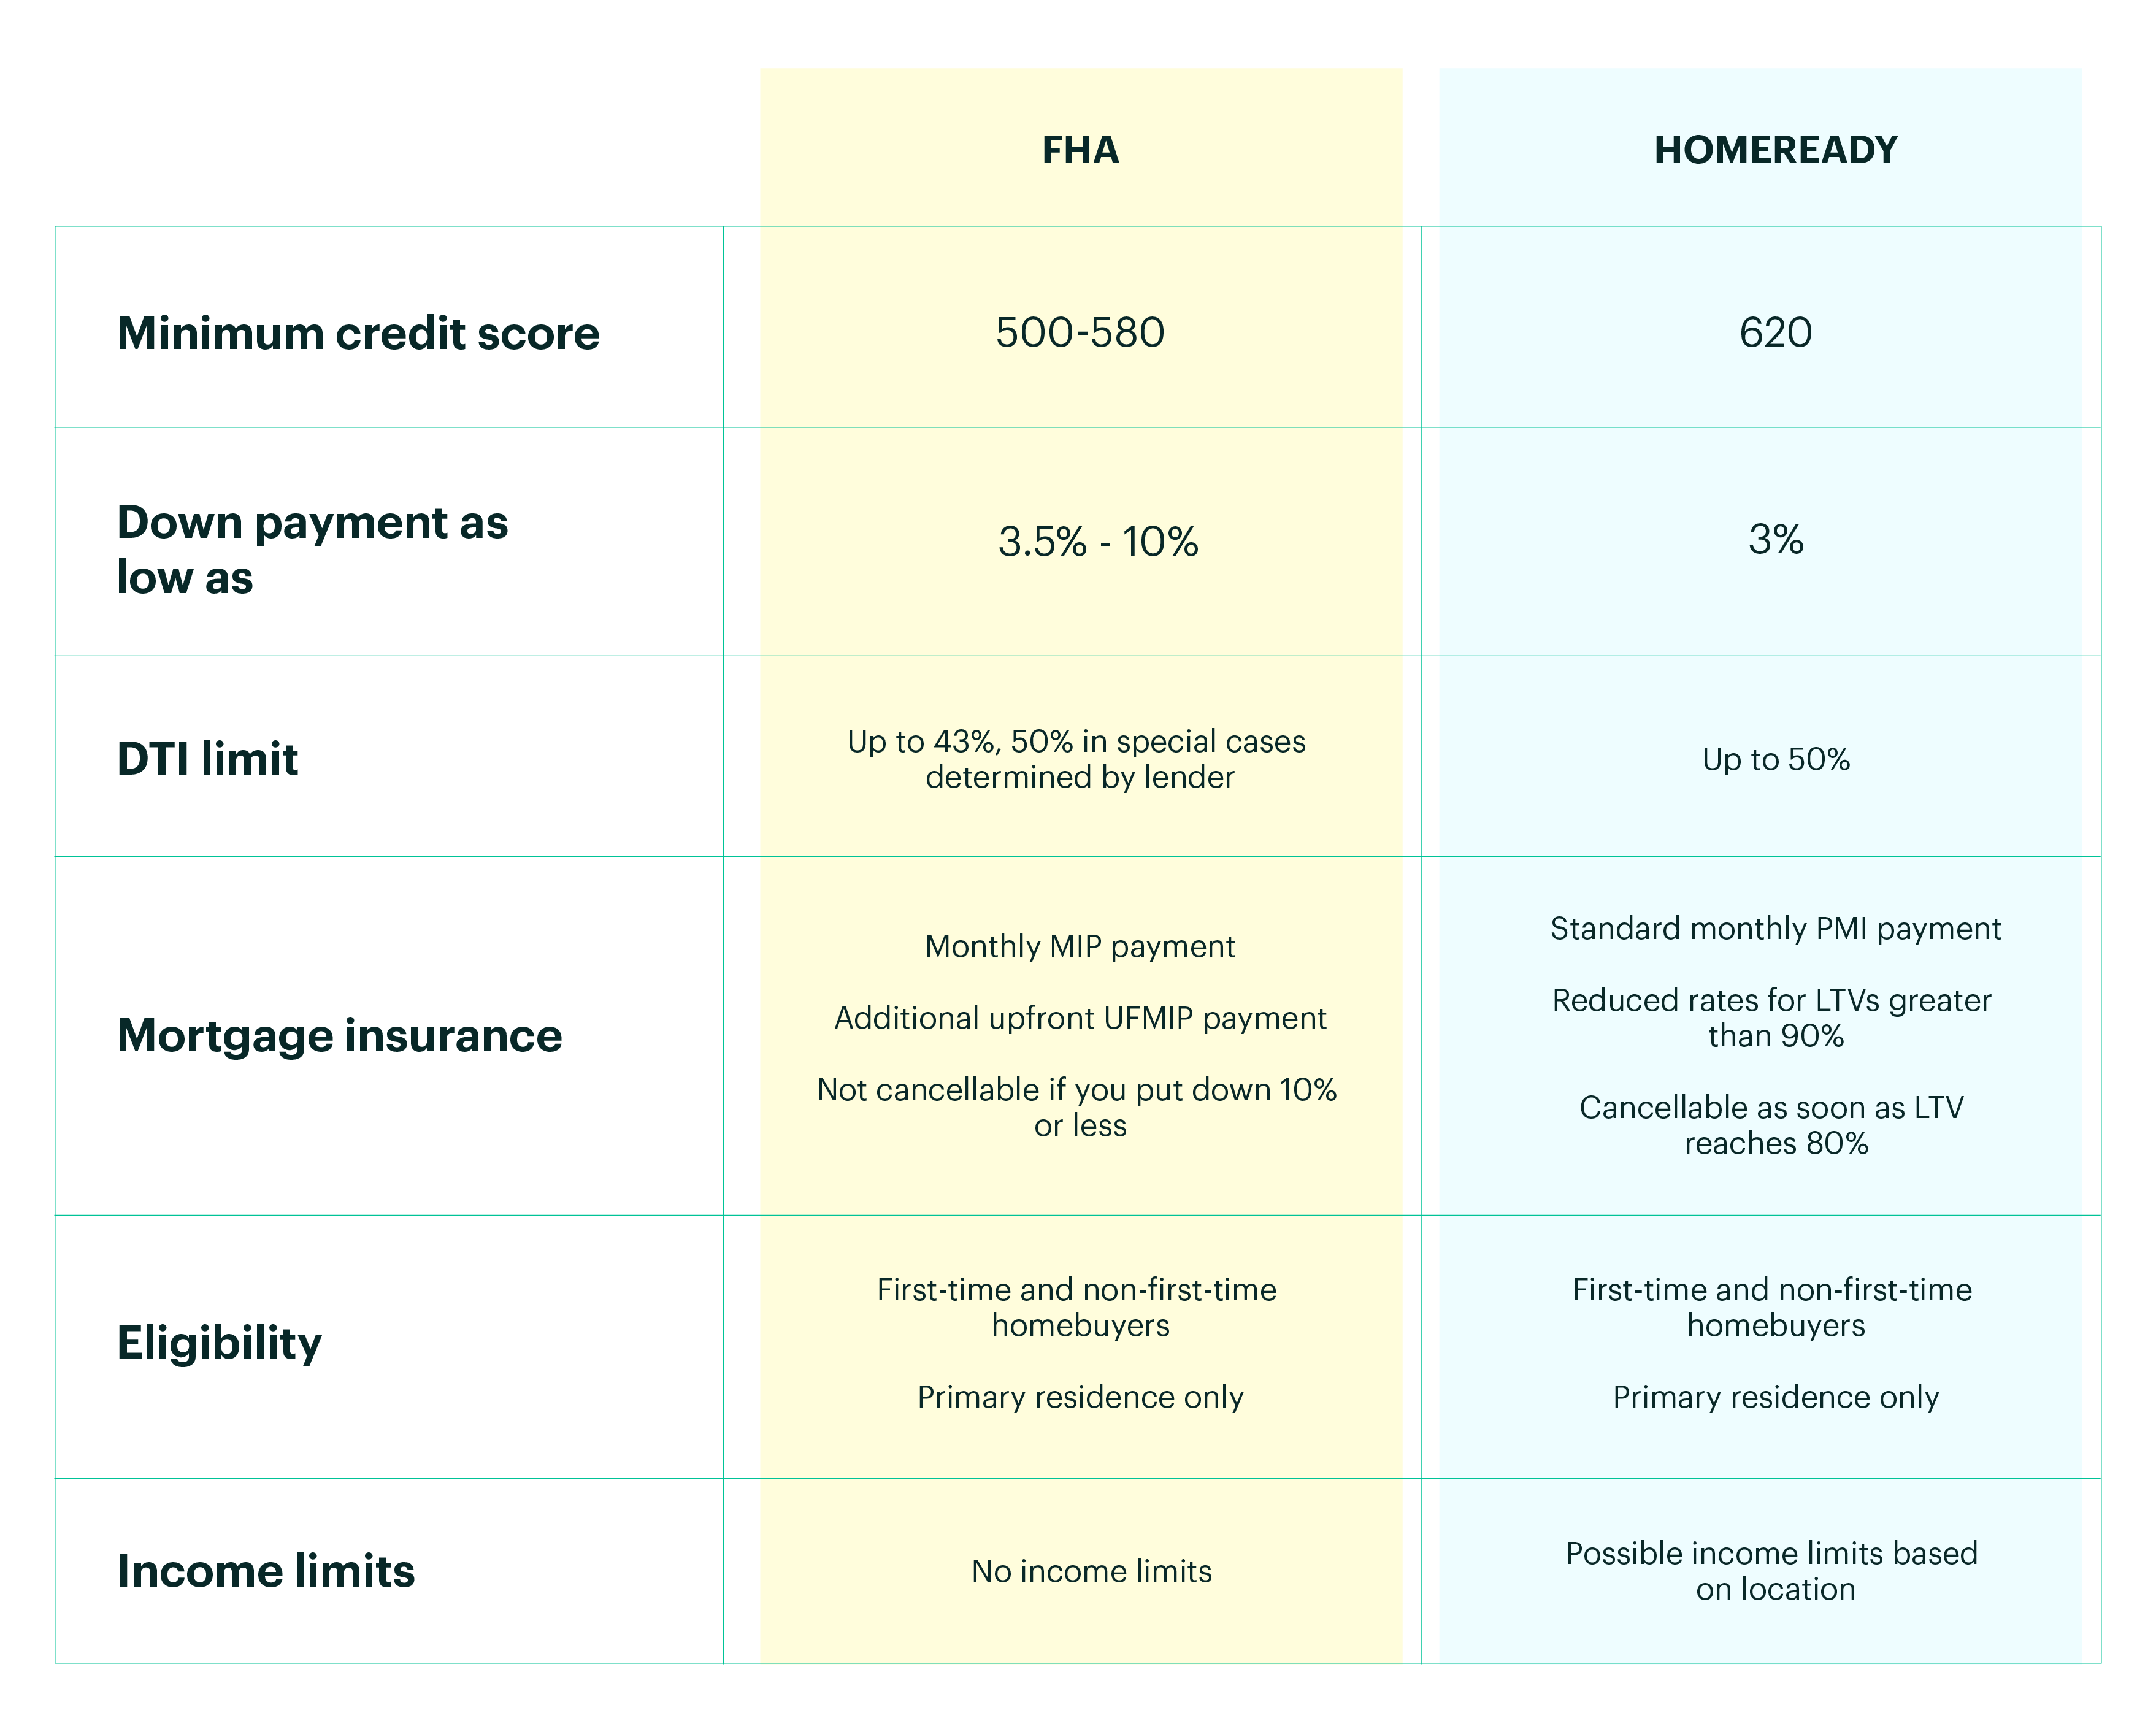
  • You can often make a down payment as low as 3.5 percent down to a 580 credit score
  • You can finance a home with a 500 credit score with 10% down payment.
  •  Kentucky FHA loans are assumable meaning that if you have a good rate on your current mortgage and the potential buyer of your home meets FHA guidelines, then he can assume your low rate mortgage
  • Kentucky FHA loans offer streamline refinancing without credit score minimums, verification of income, and no appraisals to refinance to a lower rate making it easier to qualify.
  • Kentucky FHA loans offer flexible terms when it comes to previous bankruptcy or foreclosures. 2 years removed from Chapter 7 with reestablished
  •  credit, or if a Chapter 13, one year in the payment plan is eligible for FHA financing.
  • Foreclosures on a past home. FHA will finance a home 3 years removed from the sale date of your foreclosure property
  • 30 year fixed rate mortgage with usually the best going rates on government insured loans like FHA, VA, USDA etc.
  • No prepayment penalty on Kentucky FHA loans.
  • Higher debt to income ratio requirements when compared to Conventional loans because most Fannie Mae Conventional loans cannot have a higher debt to income ratio than 45% on the back-end
  • You can make an FHA loan anywhere in the state of Kentucky with no geographical restrictions.
  • Will allow for down payment assistance and grants for borrowers minimum down payments in the State of Kentucky through the likes of KHC, Welcome Home Grant, and Kentucky Housing Down Payment Second Mortgage loans.
  • Kentucky FHA loans allow for unoccupied cosigner. For example, lets say you have a daughter that is getting ready to graduate college and does not have the income or credit history established yet to buy a home. FHA allows a family-member to co-sign for them to buy a home and you don’t have to occupy as primary residence. Note, FHA co-singers are not allowed to makeup for some that has bad credit, because they will take the lowest credit scores of both applicants. FHA usually allows for co-singers lack of income purposes only.
  • Can usually close within 30 days just like a regular conventional mortgage. No extra time to close an FHA loan in Kentucky versus other secondary market loans like VA, USDA, Fannie Mae.
  • You can use the FHA loan over and over. You can actually have two FHA loans open at the same time, but it gets tricky on this. Call or text me with more info if you have an FHA loan currently and would like to use FHA Financing again.
  • FHA loans aren’t just for first time home buyers in Kentucky.


Disadvantages of Kentucky FHA Mortgage Loans

  • There are loan limits in the State of Kentucky on FHA Mortgage loans. The maximum FHA loan in the state of Kentucky is $$420,680 for 2022.  So if you were needing to finance a loan over this amount, you would need to look at doing a Conventional loan with the updated 2021 Kentucky State Loan Limits for a Fannie Mae loan being $647,250
  • If buying a condo in Kentucky, FHA requires the condo development be FHA approved. There is a >>>list here of Kentucky FHA approved condos here.
  • Seller must have own the home for 90 days before you can make an offer on the home. This comes into play where the seller bought the home as an investor and rehabbed the property and wants to sell for a quick profit. FHA mandates seller must maintain for 90 days before you can write up an offer on it. Also called FHA Flipping Policy. Read more here  
  • There is mortgage insurance. This is one of the biggest disadvantages for FHA loans. But as I tell most people, nobody rarely has a loan for 30 years, so if it meets your payment and your cash to close requirement, I tell people to go with it because it can be refinanced down the road and you are getting one of the lowers 30 year fixed rates out there. Both upfront and monthly mortgage insurance premiums you have to pay HUD/FHA. These premiums change whenever FHA/HUD replenish their insurance pool to pay claims from defaults, but currently the FHA upfront mortgage insurance premium is 1.75% and monthly is .85% and .80% of the loan amount. If you happen do a 15 year term or shorter, the mortgage insurance is cheaper monthly with .45 and .70 respectively  each month. The upfront mortgage insurance is the same for a 30 year and 15 year at 1.75%
  • FHA Mortgage insurance can be on the loan for life of loan. This is a recent change made in 2016 when FHA lowered there premiums for upfront and monthly mi premiums, but made the mortgage insurance for life of loan for some FHA loans. 
  • If you put down more than 10% on the loan, or have at least 10% equity in the home for a refinance, you only have to pay mortgage insurance for 11 years before it automatically falls off.
  • Obviously you can refinance out of an FHA loan at anytime, since it does not a prepayment penalty, and you can potentially get a refund of your upfront mortgage insurance if paid off within 3 years on sliding scale.
  • I have incorporated some charts below to illustrate the different Kentucky FHA Mortgage Insurance premiums to explain it better.
  • The upfront mortgage insurance is usually financed into the loan, so it will look like you are borrowing more than the standard 3.5% down payment because this is financed into the loan. Some borrowers elect to pay it out of pocket upfront, but I have never seen this done in my 20 years of doing FHA loans in the State of Kentucky
  • Kentucky FHA Loans Greater Than 15 Years MIP Chart
  • 👇
    Base Loan Amt. LTV Annual MIP
    ≤$625,500 ≤95.00% 80 bps (0.80%)
    ≤$625,500 >95.00% 85 bps (0.85%)
    >$625,500 ≤95.00% 100 bps (1.00%)
    >$625,500 >95.00% 105 bps (1.05%)

    Kentucky FHA Loans Less Than or Equal to 15 Years MIP Chart👇

    Base Loan Amt. LTV Annual MIP
    ≤$625,500 ≤90.00% 45 bps (0.45%)
    ≤$625,500 >90.00% 70 bps (0.70%)
    >$625,500 ≤78.00% 45 bps (0.45%)
    >$625,500 78.01% – 90.00% 70 bps (0.70%)
    >$625,500 >90.00% 95 bps (0.95%)

    When can I get the FHA mortgage insurance off my Mortgage Loan? See chart below 👇👇

Image result for fha cancellation of mortgage insurance chart kentucky

  • Appraisals. On an FHA appraisal, the FHA appraiser has to turn on the utilities to make sure they are in worked order when he gets there. This is different that Conventional loan appraisals. A lot of realtors or buyers think that FHA loans are harder due to appraisals, but honestly, they’re really not. FHA puts these minimum HUD standards in place to make sure the home is in good working order and SAFE to live in. I.e.is there any lead based paint or chipping paint that could lead to poisoning  It is all about Safety with FHA and HUD on these appraisals. The value is determined just like a regular Conventional, USDA, VA appraisals whereas they compare the house to 3 recent homes sold in the area to get a value.
  • Some lenders don’t offer FHA loans due to their complexity and sale on the secondary market, so if you call a local lender in Kentucky and they don’t offer FHA loans, the reason is usually they don’t have the team in place to do them or don’t want to do them due to lack of experience on the secondary government market.
  • Government Liens. FHA will not be an option for you usually if you have unpaid federal tax liens, delinquency  on federal backed-government loans, or a claim with social security etc. FHA loans are ran through aCAVIRS alert system to check to see if you are delinquent on any federal oblation. If so, this swill stop you until you can clear the CAVIRS alert system. For example, I did a loan for a buyer that had a delinquent federal debt with his student loan that happened over 14 years old. It was off the credit report and title search, so I had to switch to a conventional loan to make the home loan work.
  • FHA loans are not good for second homes or investment properties. FHA loans are mainly for single family residence 1-4 unit, that are going to occupied primarily as main home.

In summary, FHA loans have few drawbacks other than the mortgage insurance in my opinion. It is a great first time home buyer program or borrowers with past credit problems to get into a house of their own with very little out of pocket, at a low 30 year fixed rate, and no prepayment penalty

Questions about qualifying for a FHA loan in Kentucky . Give me text, call or email below. Love to help you out on your next home or refinance in Kentucky
Read more below about specific FHA Loans in Kentucky.👇👇👇
Joel Lobb (NMLS#57916)
Senior  Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708

kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

Louisville Kentucky Mortgage Broker Offering FHA, VA, USDA, Conventional, and KHC Zero Down Payment Home Loans | October 17, 2018 at 3:54 pm | Tags: fha gift funds, fha loan kentucky, FHA Loans Kentucky Housing First time home buyer, fha mortgage, fha mortgage loan, gift funds for fha mortgage, kentucky fha loans |

How to qualify for a Kentucky FHA Home Loan ?

How to qualify for a Kentucky FHA Home Loan ?

Image result for fha loans ky


FHA stands for the Federal Housing Administration which is a government agency created to increase home-ownership across the United States all the way back in 1934. The agency itself doesn’t offer home loans but insures loan that are offered by private lenders (i.e. mortgage companies).

It’s important to understand the different types of loan programs available to you and what benefits and drawbacks there are to each type.

For example, if you’re looking to find a fixer upper this may not be the right loan program for you. But an FHA loan may be a better fit for you if you have little cash saved up for a down payment or if you don’t have a high credit score.

Kentucky FHA loan requirements:

  • At least 18 years old to apply
  • No age limit. just must be 18 years of age to apply.
  • Must occupy the home as a primary residence, no rental homes or investment property
  • An appraisal must be done by an FHA-approved appraiser.Typically FHA appraisal in Kentucky costs anywhere from low-end $325 to $525 with most FHA lenders in KY.
  • Home inspection is not required
  • Termite inspection not required
  • 2 years removed from Chapter 7 bankruptcy, and 1 year in Chapter 13 bankruptcy is possible to get a loan while in bankruptcy
  • Foreclosure or short sale on previous home mortgage requires 3 years removal from those dates.
  • Mortgage insurance (MIP) is required
  • Upfront Mortgage Insurance Premium is 1.75% and monthly mortgage insurance is .85% or .80% depending on loan term and loan to value.
  • Mortgage insurance is for life of loan.
  • No matter your credit scores, everyone pays the same mortgage insurance premiums.
  • Must have 2 years of employment history proving a reliable source of income
  • 500 FICO score requirement with at least 10% down payment
  • 580 FICO score requirement with at least 3.5% down payment
  • Gifts and down payment assistance programs are allowed to meet your down payment requirements. Cannot come from seller, but seller can contribute up to 6% of the sales price toward buyer’s closing costs and prepaids.
  • Student loan payments are factored into the debt-to-income ratio when applying. Typically if loans are deferred, or in an income=based repayment plan, the FHA underwriters will use 1% of the outstanding balance, which sometimes can make it difficult to qualify.
  • Your debt-to-income ratio must not be higher than 31% or total debt obligation cannot be higher than 43% of your current income. This is for a manual underwriter, meaning that if the AUS underwriting system by mortgage lenders will approve you for a higher debt to income ratio, that is fine.


Joel Lobb (NMLS#57916)
Senior  Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346

Text/call 502-905-3708kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

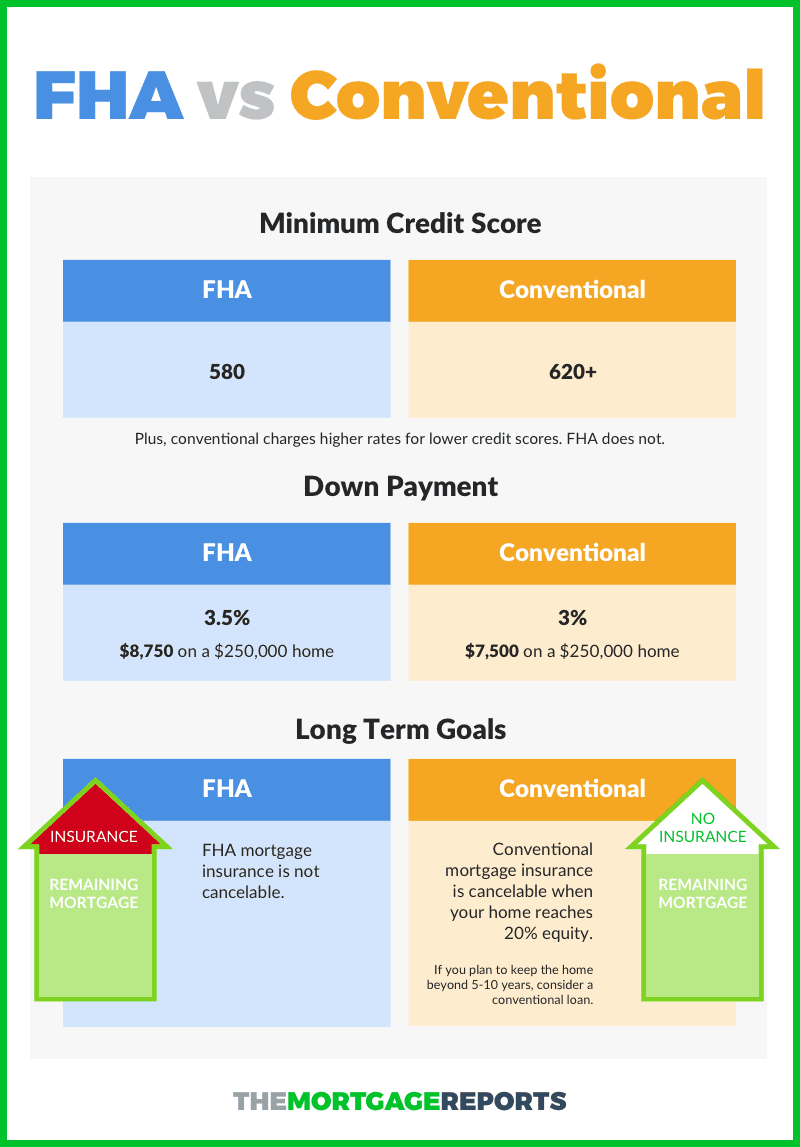
FHA vs Conventional Infograhic

Student Loans In Collections, What Can I Do to get Approved For A Kentucky Mortgage ?

Student Loans In Collections, What Can I Do?
If you have public student loans in collections, you really have three options to resolve it so it is not a CAIVRS issue.
1.      Pay it off in full – Not typically an option because very rarely do the clients have the funds to do so.
2.      Consolidation – Only takes about 90 days to consolidate and resolve CAIVRS issues. However, you push forward the last activity dates, DLA, and also introduce a new credit trade line that dilutes the length of the credit history. So you will normally see a drop in credit score.
3.      Rehabilitation – It is the slowest of all the options, but is the best thing for the clients’ credit scores. It is a 9 month commitment and once the client makes 9 consecutive payments, they will change the collection status to a good standing status. This will typically net a 40-100 point boost in the score depending on how many other collections are on the credit report.
If your client does not know who is servicing the student loan, they can contact the Student Loan Default Resolution Team at 1-800-621-3115 or visit the website at myeddebt.ed.gov
Bonus Tip: Private student loans do not adhere to consolidation or rehabilitation rules. If the client has private student loans in collections they will need to pay them off in full, or they will need to set up a payment plan on them. They will still remain in collections with a payment, but if you can get a qualified credit score you can push forward the loan including the liability payment towards the debt to income ratio.
As always, we bring you the best content so you can do what you do best, CLOSE LOANS! If you aren’t already sending us every credit challenged borrower you have, what is stopping you?
Guidelines for KY FHA, VA, USDA and VA Mortgage loans with Student Loans on A Credit Report:
Kentucky Fannie Mae or Conventional Guidelines for Student Loans:
  • If a monthly payment is on the credit report, the lender may use that amount for qualifying purposes.
  • If a monthly payment is on the credit report is incorrect, the lender may use the monthly payment on the most recent student loan statement
  • If the monthly payment on the credit report is zero, the lender must use one of the following options to calculate the payment for qualifying purposes
  1. Document the borrower is on an income driven payment plan and the actual monthly payment is zero
  2.  Use 1% of the outstanding student loan balance as the monthly payment
  3. Calculate a fully amortized payment using documented loan repayment terms
Kentucky FHA Mortgage Loans Guidelines:
Regardless of the payment status (currently in payment or deferred), the lender must use either:
  • The greater of:
  1. 1% of the outstanding balance; or
  2. The monthly payment reported on the credit; or
  •  Calculate a fully amortized payment using documented loan repayment terms
Kentucky USDA or Rural Housing Guidelines:
 
 
Regardless of the payment amount reporting on the credit, the lender must include the payment as follows:
  • A permanent amortized, fixed payment may be used in the debt ratio when the lender retains documentation to verify the payment is fixed, the interest rate is fixed, and the repayment term is fixed.
  • Payments for deferred loans, Income Based Repayment (IBR), Graduated, Adjustable, and other types of repayment agreements which are not fixed cannot be used in the total debt ratio calculation. One percent of the loan balance reflected on the credit report must be used as the monthly payment. No additional documentation is required.
Kentucky  VA Mortgage Guidelines for Student Loan:
  • If the borrower can document the student loan will be deferred 12 months from the closing date, the monthly payment does not need to be considered
  • If a student loan is in repayment or scheduled to begin repayment within 12 months from the closing date, the threshold payment amount must be calculated by  using 5% of the loan balance divided by 12 months
  • If the payment reporting on the credit report is greater than the threshold payment calculation amount, then the credit report payment must be used for ratios.
  • If the payment reporting on the credit report is less than the threshold payment calculation and the lender is using the lower payment to qualify the borrower then:
  1. A statement from the student loan servicer reflecting the actual loan terms and payment information must be included in the file.
  2. The statement must be dated within 60 days of closing
  3. It is the underwriter’s discretion to use the lower payment

As you can see, Fannie Mae or Conventional loans is the most lenient when it comes to qualifying for a mortgage loan with someone that has a lot of student loans on their credit report.


 FHA Mortgage Loans- Gifts to Pay off Debt to Qualify for a FHA Home Loan.


FHA Loans in Kentucky  – Gifts to Pay off Debt

Do you know that a gift can be used to pay off Borrower’s debts to qualify on an Kentucky FHA Loan?

A regular gift (this does not include a gift of equity) may be used to pay off a Borrower’s debt(s) for qualifying purposes as long as both the gift funds and the debt(s) being paid off with the gift funds are accurately disclosed and assessed by AUS TOTAL Scorecard. Whenever a gift is received on an Kentucky FHA loan, regardless of what it is being used for, it carries certain risks that must be assessed by TOTAL Scorecard for qualifying purposes.

When a gift is received to pay off debt(s), follow the steps below to ensure that TOTAL Scorecard accurately assesses the risk of using gift funds in paying off debt for qualifying:

  • Verify that evidence of the debt(s) having a zero balance has been obtained,
  • Enter the gift funds received separate from any account balances and check “will be paid off” for debts in loan origination system (not “paid off”), and
  • Submit the loan to TOTAL Scorecard
 
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708
kentuckyloan@gmail.com

http://www.nmlsconsumeraccess.org/
If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

Kentucky $15,000 Down payment Assistance Grant For Kentucky Home Buyers in 2016


New Income Limits for Jefferson County Kentucky and Louisville Home Buyers lacking a down payment.

The new income limits for Kentucky Housing loans are based on annual borrower income, and vary by county. Here’s how they break down for Central Kentucky and the Louisville area:

  • Purchase price up to $294,000 with Secondary Market and max household income is limited to $112,000 with MRB for Jefferson County Kentucky. No homeownership in last 3 years and a minimum credit score of 640. Max debt to income ratios of 40 an 45%

khcdapmarhta


—

 
Joel Lobb
Senior  Loan Officer
(NMLS#57916)
 

phone: (502) 905-370