Kentucky FHA Mortgage Insurance Requirements and Down Payments

FHA mortgage insurance, typically referred to as MIP, is the one closing cost that is unique to FHA mortgage programs. 

**Every FHA mortgage must have mortgage insurance regardless

of the amount of the down payment.**


There are two types of mortgage insurance for FHA insured loans – Up-front Mortgage Insurance Premiums and Monthly Mortgage Insurance Premiums.

Up-front Mortgage Insurance Premium (UFMIP)


UFMIP is calculated at 1.75% of the base loan amount on all loans, regardless of the down payment amount.  This insurance protects the lender against losses in the event that the borrower defaults on the loan. 

**The entire amount of the UFMIP can be financed into the loan amount!**


For example:

  • If the FHA loan amount is $100,000 (base loan amount)
  • The mortgage insurance premium would be $1,750 ($100,000 x 1.75%)
  • The mortgage amount including MIP would be $101,750 ($100,000 + $1,750)

What really happens during an FHA mortgage transaction is that the borrower owes FHA a lump sum mortgage insurance premium.  The lender making the FHA loan will actually lend the money for the premium to the borrower and send the money to FHA so that the mortgage will be insured. 

Monthly Mortgage Insurance Premium


In addition to the UFMIP, there may be a monthly premium due as well.  The monthly premium is .80% of the base loan amount if the loan amount is less than or equal to 95% of the value of the home.  If the loan amount is over 95% of the value of the home, the monthly premium is .85% of the base loan amount..


On a 30 year fixed loan, the monthly payment would be calculated as follows:


$100,000 x .80% = $800 / 12 months = $66.67 per month

FHA Minimum Down Payment

Effective January 1, 2009, the minimum down payment required on an FHA loan is 3.5% of the purchase price. 


Any deposit (usually called earnest money) that you are required to give to your realtor at the time of an accepted purchase contract will count towards your 3.5% down payment. The appraisal fee collected at the time of inspection will also count towards your 3.5% down payment. 

 
If, for example, you are purchasing a $100,000 house, your minimum down payment required would be $3,500.  If your seller/realtor required you to put down $500 in earnest money on top of the $300 for your appraisal, your down payment would be lowered to $2,700 ($3,500 – $500 – $300 = $2,700). 


Down Payment As A Gift


If a borrower does not have 3.5% of his or her own money to put down towards the home purchase, FHA allows that amount to be in the form of a gift to the borrower. The gift must be from a qualified source, such as a family member, employer or significant other. The source of the gift must be able to provide proof that they have the money in an account registered in their name prior to transfer to the borrower.


In some areas, this gift may also be grant money from a state or local municipality, if such funds are available.

Kentucky FHA Mortgage Qualifying Guidelines

Kentucky FHA Loans

The FHA is actually not the lender. They insure the loans that are issued by FHA-approved lenders. FHA loans are gear more toward borrower’s with less than 20% down payment and credit issues in the past.

Qualifying for a FHA Loan Mortgage In Kentucky

Credit Scores and Down Payment Percentages – Each year, the rules for qualifying for these loans changes. For 2020, applicants need a minimum credit score of 580 in order to get the low down payment, which is 3.5 percent.

For those whose credit score is less than 580, they will have to come up with 10 percent for their down payment. This does not guaranteed a mortgage loan approval if you have the certain credit scores, just a the minimum required.

Compensating Factors for FHA loan Approval

The credit score is just one part of the story. The FHA will also evaluate the borrower’s bankruptcies, foreclosures, prior payment history on other debts. They will also want information on difficulties that kept the borrower from making payments on other debts in the past.

Negative strikes against qualifying for the loan include not having any credit history or a bankruptcy.

Someone with a bankruptcy will have to wait for two or more years after their bankruptcy before applying for an FHA-insured loan.

If you have late payments on debt obligations, it is best to wait until you have had a full year of on-time payments before you apply for a FHA-insured loan.

If you have had a foreclosure in the past, you may still be able to get a FHA-insured loan three years after your foreclosure. The lender will be looking at the circumstances behind the foreclosure.

If you have had any civil judgement against you for money owed, collections actions or unpaid/unresolved federal debt, the FHA-approved lender will be required by the FHA to establish that all of these outstanding issues are resolved or paid before you can go through closing.

Watch out for student loans if they are delinquent because sometime this can cause a lien against you in the form of a CAVIRS Alert with HUD

As you can see, many types of borrowers who would not be eligible for a traditional mortgage, or who would face exorbitant interest rates, will be able to qualify for a FHA-insured loan at attractive interest rates.

Employment and Income for a Kentucky FHA Loan

You must have an employment history that is steady for the last two years. Does not have to be same employer.

Your income has to be verifiable in some way, whether that be through pay stubs, your income tax returns. No bank statements or cash deposits , or undocumented income can be used for income qualifying purposes.

Image result for Employment and Income for a Kentucky FHA Loan

Debt-to-Income Ratio Requirements –

Depending on the automated underwriting system from Desktop Originator, your Debt-to-income ratio is the percentage of your income before taxes that you spend on monthly debt.

Taking into account the proposed mortgage payment as well as the other debts, the FHA requires that these debts all total less than 43 percent of your pretax income in order to qualify for the loan.

If your debt load is too high, you will struggle to pay all of your bills and mortgage expenses and care for yourself and your family.

55488026_2283733755207645_6787062571322048512_n (1)

Property Requirements for a Kentucky FHA Loan

It must be the place where you intend to reside. You must move into the home within 60 days of closing the loan. The home cannot be an investment. There will be an inspection to ensure that the home is safe and habitable.

It is really not too hard to pass FHA loans and the appraisal process.

23444444

Pros of FHA Loans –

  • New homebuyers and those who have lower credit scores or who have other blemishes on their credit history will often qualify for FHA-insured loans.

  • Even though these borrowers are considered “subprime” to a traditional lender, they will receive attractive interest rates through the FHA-insured mortgage programs.

  • The down payments required from borrowers are lower than those required by traditional mortgage lenders.

  • These loans can be combined with other forms of public assistance for lower income or new borrowers so that the borrower will not need to come up with a down payment of any kind.

Cons of FHA Loans –

  • Since the FHA is not actually the lender, and you have to go through FHA-approved lenders, you may not qualify due to stricter standards that the lender has for the loan.

  • Because you are not paying 20 percent as a down payment, the FHA requires two mortgage insurance premiums to be paid. One is an upfront premium that is 1.75 percent of the loan amount. Lenders often will allow you to make that mortgage insurance premium a part of your loan. The second is an annual mortgage insurance premium that is .45 percent or 1.05 percent. This premium is paid monthly.

 FHA FINANCING

CREDIT REQUIREMENTS FOR KENTUCKY FHA FINANCING

What credit score do I need to qualify for a Kentucky FHA loan is one of the most common questions I hear from Kentucky homebuyers?

The short answer is you must have a minimum credit score of 500 to be eligible for an FHA loan in Kentucky.  Anything lower than 500 disqualifies you from consideration for an FHA loan.

There are two sets of credit score requirements for a Kentucky FHA Loan

One important thing to understand is that the Federal Housing Administration (FHA) does not lend money directly to home buyers. You will fill out an application with a regular lender just as you would if you were applying for any other type of mortgage. What the FHA does is ensure your loan to help protect the lender in case you default.

You will be required not only to meet the FHA guidelines to qualify for a loan but also meet any additional qualifications required by the lender. This means there are two sets of requirements you have to meet with your credit score.

1. The first set of requirements comes from the Department of Housing and Urban Development (HUD). HUD oversees the FHA and determines what a borrower’s minimum eligibility requirements will be to obtain an FHA loan.

2. The second set of requirements comes from the mortgage lender. The mortgage lender has the right to add its requirements to those mandated by HUD.

What HUD requires of borrowers to be eligible for an FHA loan

The HUD Handbook 4000.1 includes the official guidelines when it comes to the FHA mortgage insurance program.

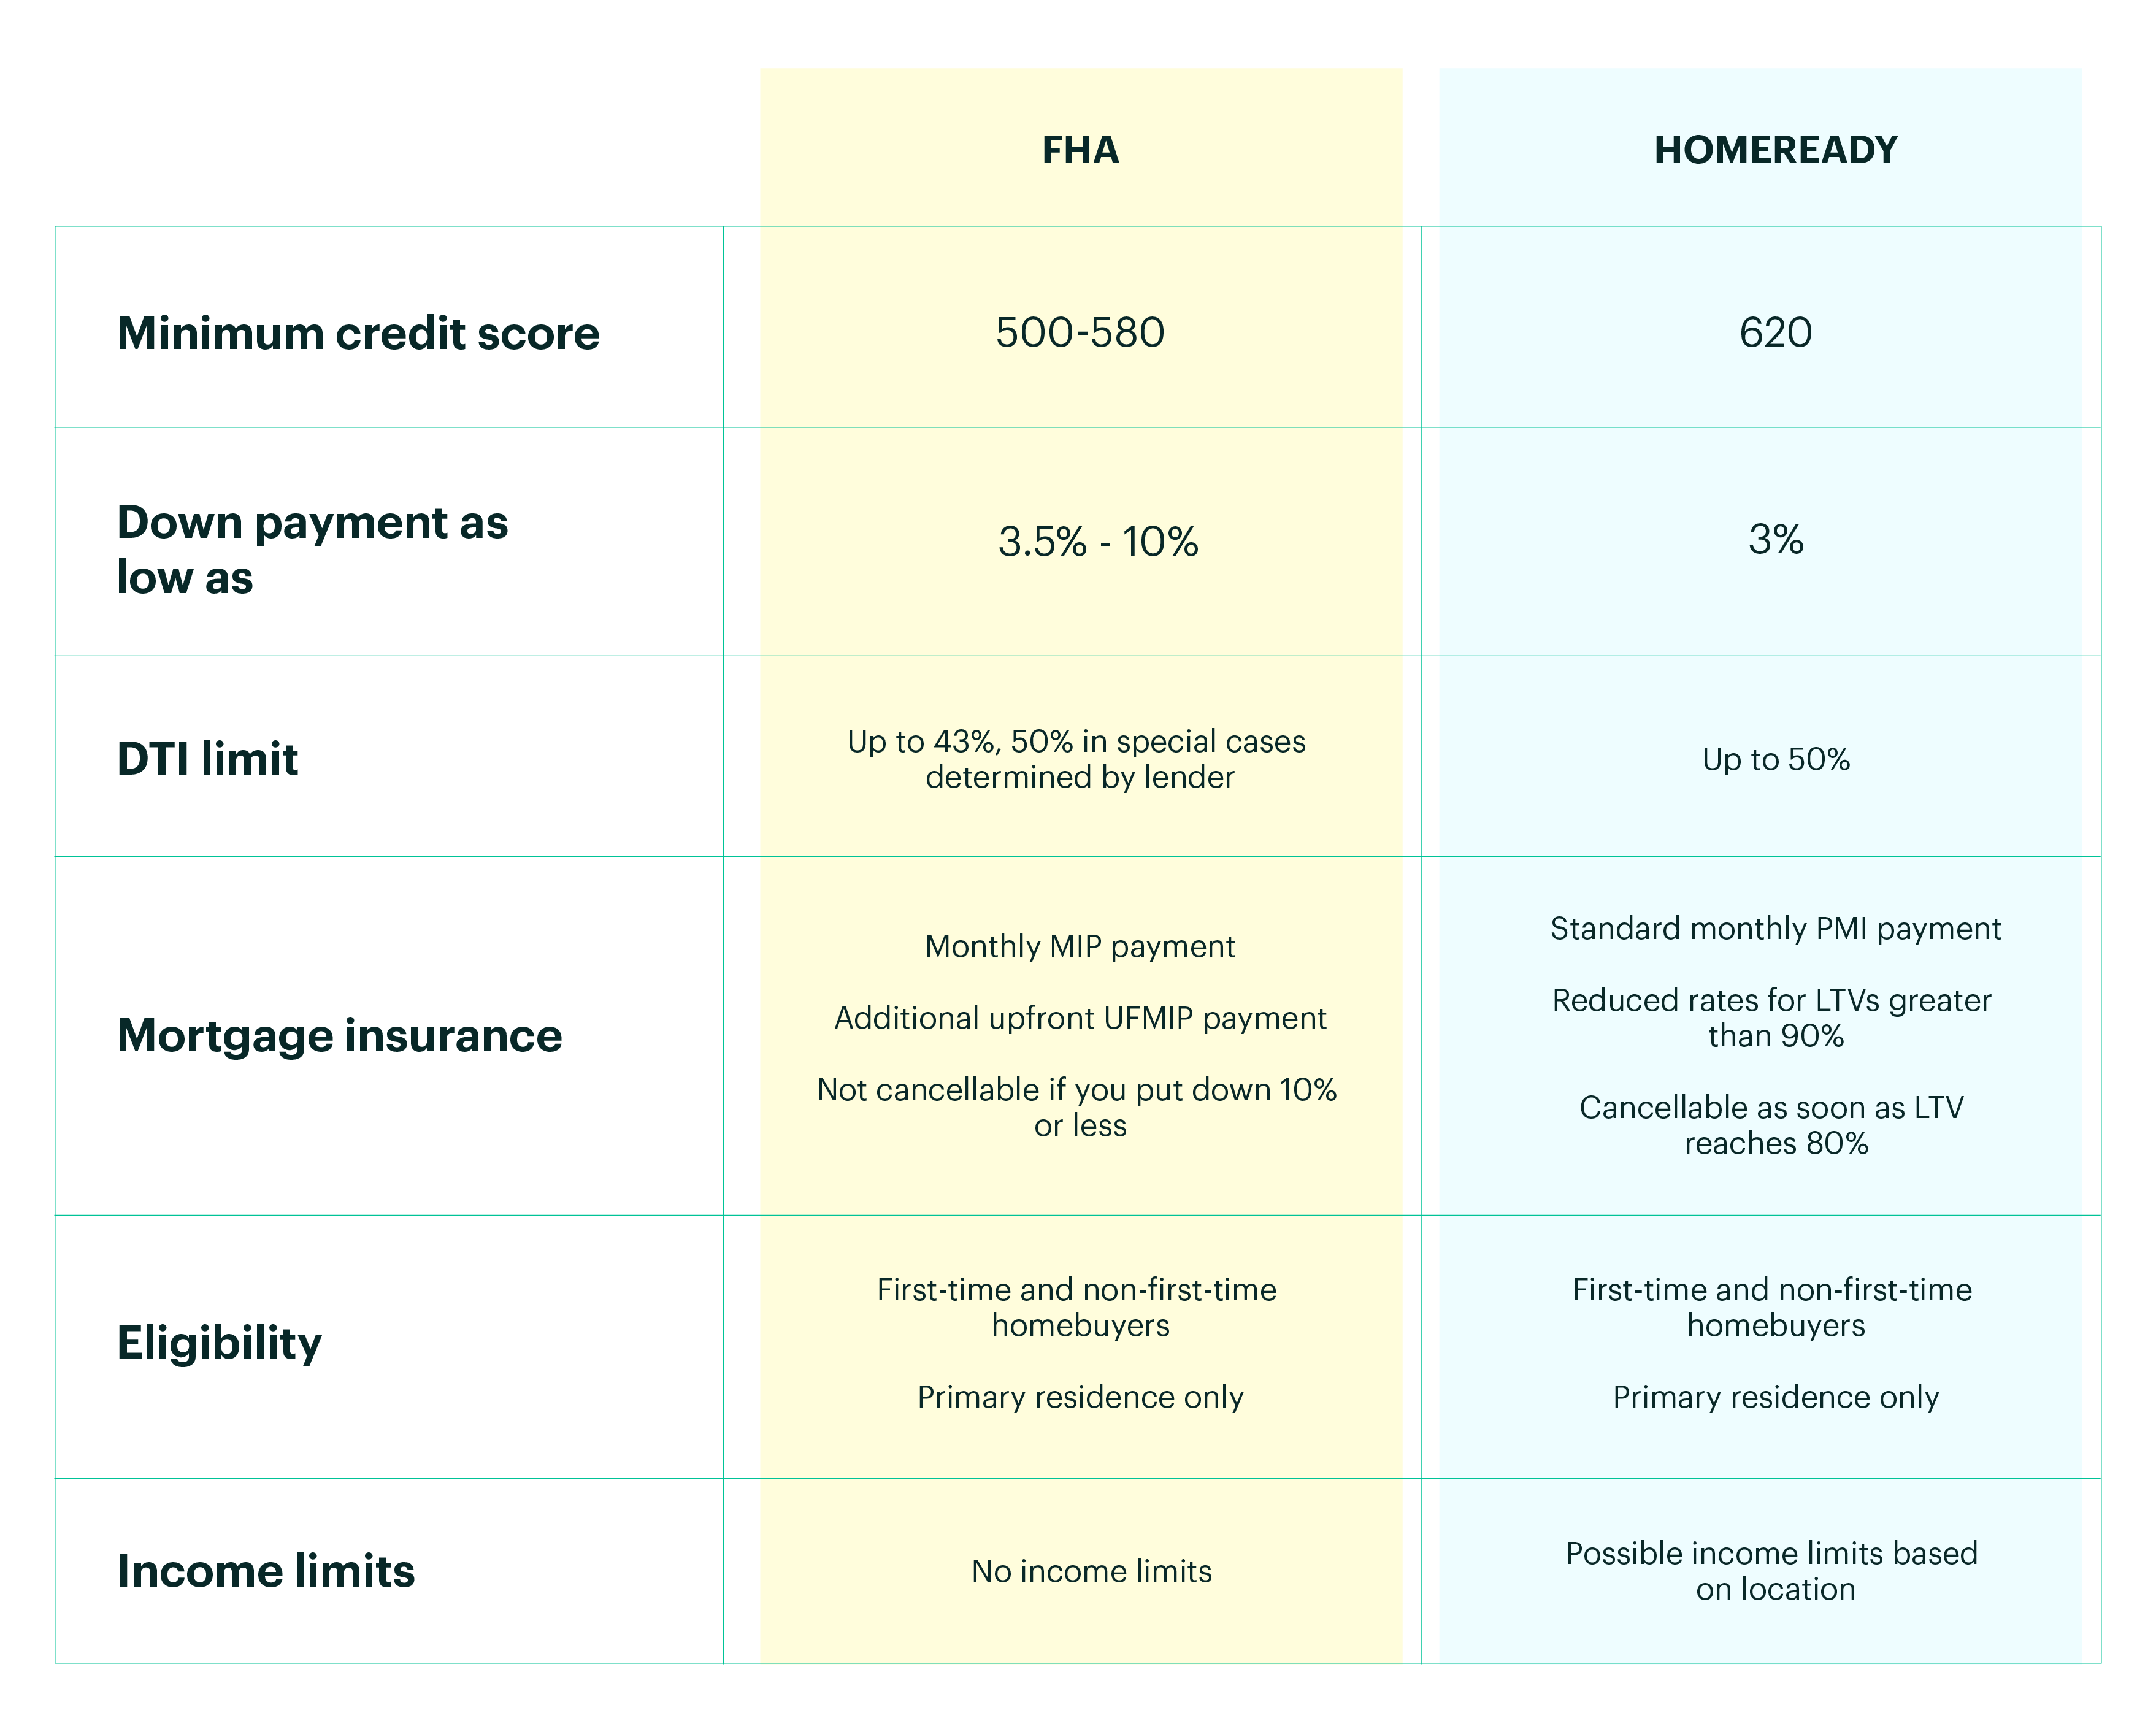
It states that in 2020 the Kentucky FHA borrowers with credit scores of 580 or higher are eligible for a 96.5% loan with 3.5% down.

Borrowers with credit scores from 500 to 579 are eligible for a 90% loan with 10% down.

Individuals with credit scores below 500 are not eligible for the FHA program.

What lenders may require of borrowers to be eligible for an Kentucky FHA loan

Lenders have the right to add requirements over and above the minimum requirements of HUD. These additional requirements are called overlays. Your lender may or may not require them.

This is not something that should come as a surprise to you, however. Requiring a credit score of 580 to 620 is not unusual. In addition to your credit score, you must have a manageable debt level that lenders are comfortable with and enough income to repay your loan.

What credit score do I need to qualify for FHA loan?

Each month Ellie Mae, the software company processing more than ⅓ of America’s mortgage loans, publishes an insight report for mortgage trends and standards. One of the things they track is average credit scores. The following is their report for November 2019 which shows what percentage of successful borrowers fall into what credit score ranges.

500 – 549    2.14%
550 – 599    5.20%
600 – 649    23.01%
650 – 699    34.74%
700 – 749    21.88%
750 – 799    10.87%
800+     1.89%

These percentages show that the majority of borrowers who successfully qualify for FHA loans fall into the 600 to 799 range. While it is true that some successfully qualify in the low range of 500 to 599, you have a much better chance of being approved for a loan with good terms and a low down payment if you fall into the higher range.


For your free credit report and analysis call us today at 502-905-3708 or email us at kentuckyloan@gmail.com


Joel Lobb (NMLS#57916)
Senior  Loan Officer
 
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
 
Company ID #1364 | MB73346


Text/call 502-905-3708
kentuckyloan@gmail.com


If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.


Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/


72875369_2600900606627287_6040534183682506752_n

How to qualify for a Kentucky FHA Home Loan ?

How to qualify for a Kentucky FHA Home Loan ?

Image result for fha loans ky


FHA stands for the Federal Housing Administration which is a government agency created to increase home-ownership across the United States all the way back in 1934. The agency itself doesn’t offer home loans but insures loan that are offered by private lenders (i.e. mortgage companies).

It’s important to understand the different types of loan programs available to you and what benefits and drawbacks there are to each type.

For example, if you’re looking to find a fixer upper this may not be the right loan program for you. But an FHA loan may be a better fit for you if you have little cash saved up for a down payment or if you don’t have a high credit score.

Kentucky FHA loan requirements:

  • At least 18 years old to apply
  • No age limit. just must be 18 years of age to apply.
  • Must occupy the home as a primary residence, no rental homes or investment property
  • An appraisal must be done by an FHA-approved appraiser.Typically FHA appraisal in Kentucky costs anywhere from low-end $325 to $525 with most FHA lenders in KY.
  • Home inspection is not required
  • Termite inspection not required
  • 2 years removed from Chapter 7 bankruptcy, and 1 year in Chapter 13 bankruptcy is possible to get a loan while in bankruptcy
  • Foreclosure or short sale on previous home mortgage requires 3 years removal from those dates.
  • Mortgage insurance (MIP) is required
  • Upfront Mortgage Insurance Premium is 1.75% and monthly mortgage insurance is .85% or .80% depending on loan term and loan to value.
  • Mortgage insurance is for life of loan.
  • No matter your credit scores, everyone pays the same mortgage insurance premiums.
  • Must have 2 years of employment history proving a reliable source of income
  • 500 FICO score requirement with at least 10% down payment
  • 580 FICO score requirement with at least 3.5% down payment
  • Gifts and down payment assistance programs are allowed to meet your down payment requirements. Cannot come from seller, but seller can contribute up to 6% of the sales price toward buyer’s closing costs and prepaids.
  • Student loan payments are factored into the debt-to-income ratio when applying. Typically if loans are deferred, or in an income=based repayment plan, the FHA underwriters will use 1% of the outstanding balance, which sometimes can make it difficult to qualify.
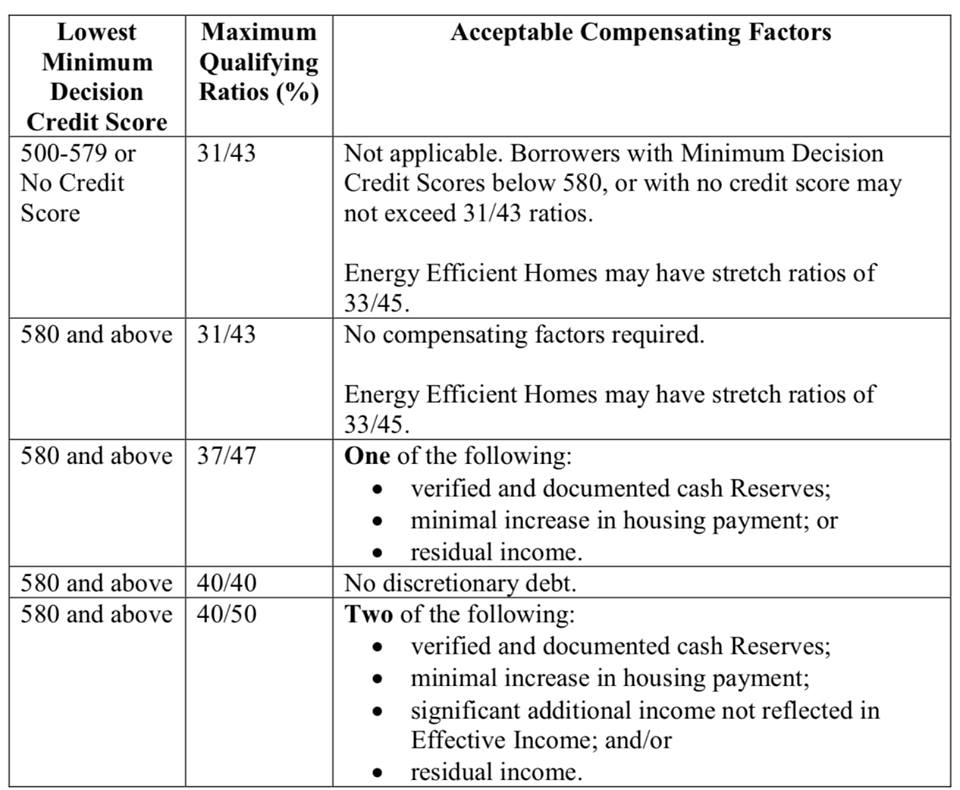
  • Your debt-to-income ratio must not be higher than 31% or total debt obligation cannot be higher than 43% of your current income. This is for a manual underwriter, meaning that if the AUS underwriting system by mortgage lenders will approve you for a higher debt to income ratio, that is fine.


Joel Lobb (NMLS#57916)
Senior  Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346

Text/call 502-905-3708kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

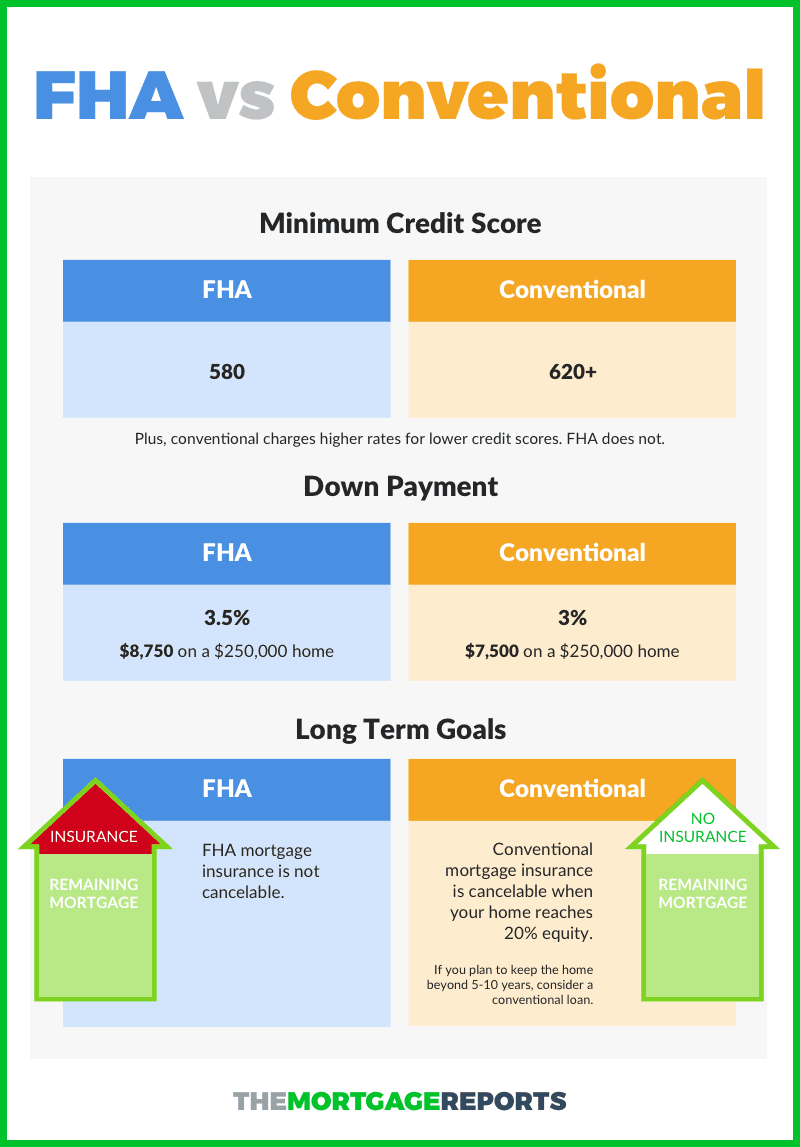
FHA vs Conventional Infograhic

Student Loans In Collections, What Can I Do to get Approved For A Kentucky Mortgage ?

Student Loans In Collections, What Can I Do?
If you have public student loans in collections, you really have three options to resolve it so it is not a CAIVRS issue.
1.      Pay it off in full – Not typically an option because very rarely do the clients have the funds to do so.
2.      Consolidation – Only takes about 90 days to consolidate and resolve CAIVRS issues. However, you push forward the last activity dates, DLA, and also introduce a new credit trade line that dilutes the length of the credit history. So you will normally see a drop in credit score.
3.      Rehabilitation – It is the slowest of all the options, but is the best thing for the clients’ credit scores. It is a 9 month commitment and once the client makes 9 consecutive payments, they will change the collection status to a good standing status. This will typically net a 40-100 point boost in the score depending on how many other collections are on the credit report.
If your client does not know who is servicing the student loan, they can contact the Student Loan Default Resolution Team at 1-800-621-3115 or visit the website at myeddebt.ed.gov
Bonus Tip: Private student loans do not adhere to consolidation or rehabilitation rules. If the client has private student loans in collections they will need to pay them off in full, or they will need to set up a payment plan on them. They will still remain in collections with a payment, but if you can get a qualified credit score you can push forward the loan including the liability payment towards the debt to income ratio.
As always, we bring you the best content so you can do what you do best, CLOSE LOANS! If you aren’t already sending us every credit challenged borrower you have, what is stopping you?
Guidelines for KY FHA, VA, USDA and VA Mortgage loans with Student Loans on A Credit Report:
Kentucky Fannie Mae or Conventional Guidelines for Student Loans:
  • If a monthly payment is on the credit report, the lender may use that amount for qualifying purposes.
  • If a monthly payment is on the credit report is incorrect, the lender may use the monthly payment on the most recent student loan statement
  • If the monthly payment on the credit report is zero, the lender must use one of the following options to calculate the payment for qualifying purposes
  1. Document the borrower is on an income driven payment plan and the actual monthly payment is zero
  2.  Use 1% of the outstanding student loan balance as the monthly payment
  3. Calculate a fully amortized payment using documented loan repayment terms
Kentucky FHA Mortgage Loans Guidelines:
Regardless of the payment status (currently in payment or deferred), the lender must use either:
  • The greater of:
  1. 1% of the outstanding balance; or
  2. The monthly payment reported on the credit; or
  •  Calculate a fully amortized payment using documented loan repayment terms
Kentucky USDA or Rural Housing Guidelines:
 
 
Regardless of the payment amount reporting on the credit, the lender must include the payment as follows:
  • A permanent amortized, fixed payment may be used in the debt ratio when the lender retains documentation to verify the payment is fixed, the interest rate is fixed, and the repayment term is fixed.
  • Payments for deferred loans, Income Based Repayment (IBR), Graduated, Adjustable, and other types of repayment agreements which are not fixed cannot be used in the total debt ratio calculation. One percent of the loan balance reflected on the credit report must be used as the monthly payment. No additional documentation is required.
Kentucky  VA Mortgage Guidelines for Student Loan:
  • If the borrower can document the student loan will be deferred 12 months from the closing date, the monthly payment does not need to be considered
  • If a student loan is in repayment or scheduled to begin repayment within 12 months from the closing date, the threshold payment amount must be calculated by  using 5% of the loan balance divided by 12 months
  • If the payment reporting on the credit report is greater than the threshold payment calculation amount, then the credit report payment must be used for ratios.
  • If the payment reporting on the credit report is less than the threshold payment calculation and the lender is using the lower payment to qualify the borrower then:
  1. A statement from the student loan servicer reflecting the actual loan terms and payment information must be included in the file.
  2. The statement must be dated within 60 days of closing
  3. It is the underwriter’s discretion to use the lower payment

As you can see, Fannie Mae or Conventional loans is the most lenient when it comes to qualifying for a mortgage loan with someone that has a lot of student loans on their credit report.


KENTUCKY HUD HOMES FOR SALE

KENTUCKY FHA $100 DOWN PROGRAM FOR HOMEBUYERS IN KENTUCKY​

Kiss-your-landlord-goodbye


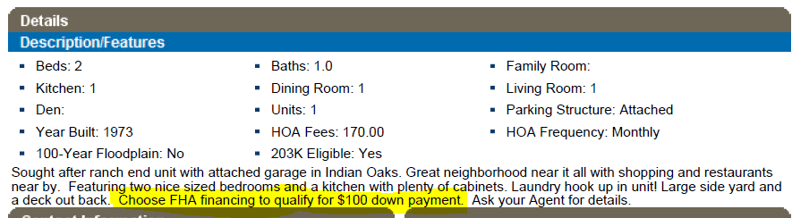
FHA’s $100 Down Program​ is allowed for Kentucky Home Buyers buying a home that is owned by HUD or FHA​. The $100 Down sales incentive permits a Borrower to purchase a HUD REO Property with FHA-insured financing with a minimum downpayment of $100.

This program can ONLY be used to purchase homes owned by HUD OR FHA.

Check the link below to see if any properties are offered in your area. If a property is eligible, the listing on the website will specify $100 Down Financing Incentivize.

You can find all current listings for sale by HUD here.

100 down payment

The main factors in qualifying for this​ Kentucky FHA ​ program are that the property must be a HUD REO property and purchased using FHA Financing, aside from these, the requirements include:

  1. Occupancy: The property must be purchased for use as your Primary Residence.
  1. Property Type: Eligible properties include 1 or 2 unit homes, manufactured homes, condos, and PUDs.
  1. Full Price Offer: You must submit an offer for the full listing price. Typically, when you purchase a home, you make an offer to the seller…. we all want to get the best deal so you may offer less than the asking price… or you may offer more if the home you want is being bid on by many buyers…. With HUD REO properties this is not allowed. The sales price HUD has on the listing is what you must offer.
  1. Sales Contract: The $100 down payment incentive must be included on the executed sales contract.
  1. Cannot have purchased a HUD home within the preceding 24 months
  1. Credit Score:​ ​580 is the minimum FICO score you must have to qualify for a FHA Kentucky Home Buyer using the HUD $100 Down loan program. 
  2. Usually takes about 30-45 days to close
  3. Earnest Money Deposit usually needs to be at least $500 to $1000
  4. This is a manual underwriter meaning that your debt to income ratio has to be 31 and 43% respectively
  5. No Chapter 7 Bankruptcies in last two years
  6. No Foreclosures in last 3 years
  7. Clear Cavirs on borrowers.
*Required field, except if Property Case # or Zip Code is entered

Search Results for HUD Homes in KY

1 | 2 | 3 | 
47 listings found
List Gallery
Save Search Email Search View Map Export to Display: 
5
10
20
Property Case Address Price Status Bed Bath Listing Period Bid Open Date Details 
201-271516 345 Concord Dr
White Plains, KY, 42464
Hopkins County
$13,600 3 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-278709 793 Highway 16
Glencoe, KY, 41046
Gallatin County
$24,000 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-339965 2750 Latonia Ave
Covington, KY, 41015
Kenton County
$33,600 2 1.10 Exclusive  12/03/2018 View Street
Map it
Email Info
201-340924 1309 Little Pigeon Ct
Lexington, KY, 40515
Fayette County
$63,000 3 1.00 Lottery  11/29/2018 View Street
Map it
Email Info
201-347762 307 Elkhorn Green Pl
Georgetown, KY, 40324
Scott County
$105,000 4 2.10 Exclusive  11/29/2018 View Street
Map it
Email Info
201-348170 820 Mars Dr
Verona, KY, 41092
Gallatin County
$48,000 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-362370 194 Batton Loop
Morehead, KY, 40351
Rowan County
$59,400 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-368065 199 Lake Trail Land
Russell Springs, KY, 42642
Russell County
$34,400 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-370012 112 Cherry Lane
Frankfort, KY, 40601
Franklin County
$50,000 2 2.00 Exclusive  12/03/2018 View Street
Map it
Email Info
201-372013 10057 Elizabethtown Rd
Big Clifty, KY, 42712
Grayson County
$32,000 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-386189 4701 Dohn Rd
Louisville, KY, 40216
Jefferson County
$51,000 3 1.00 Exclusive  12/10/2018 View Street
Map it
Email Info
201-387184 12804 Walnut Creek Dr
Alexandria, KY, 41001
Campbell County
$159,000 4 2.10 Extended  11/29/2018 View Street
Map it
Email Info
201-391357 38 Lovelaceville Rd
Lovelaceville, KY, 42060
Ballard County
$19,600 2 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-393499 620 Main Street
Uniontown, KY, 42461
Union County
$26,100 3 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-396375 119 Crane St
Somerset, KY, 42501
Pulaski County
$30,000 2 1.00 Exclusive  11/29/2018 View Street
Map it
Email Info
201-401444 151 Eastside Park Dr
Butler, KY, 41006
Pendleton County
$50,400 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-407845 824 Pike St
Sadieville, KY, 40370
Scott County
$27,000 1 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-411349 115 Jimmy Lovell Ro
Dawson Springs, KY, 42408
Hopkins County
$75,000 2 1.10 Exclusive  12/10/2018 View Street
Map it
Email Info
201-412276 386 W Elm St
Clay, KY, 42404
Webster County
$35,000 3 2.10 Exclusive  12/03/2018 View Street
Map it
Email Info
201-417838 147 Main Street
Newport, KY, 41071
Campbell County
$38,500 1 1.00 Extended  11/29/2018 View Street
Map it
Email Info
1 | 2 | 3 
 

Search Results for HUD Homes in KY

1 | 2 | 3 | 
47 listings found
List Gallery
Save Search Email Search View Map Export to Display: 
5
10
20
Property Case Address Price Status Bed Bath Listing Period Bid Open Date Details 
201-427873 229 Rosedale Ct
Covington, KY, 41015
Kenton County
$42,400 2 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-445853 902 Deer Haven Dr
Owensboro, KY, 42301
Daviess County
$63,000 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-448631 13302 Horncastle Ave
Louisville, KY, 40272
Jefferson County
$65,000 4 1.10 Exclusive  11/30/2018 View Street
Map it
Email Info
201-461769 511 1/2 Cleaver St
Elizabethtown, KY, 42701
Hardin County
$20,000 1 1.00 Exclusive  12/03/2018 View Street
Map it
Email Info
201-481525 216 10th St
Carrollton, KY, 41008
Carroll County
$117,000 4 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-483660 204 Village Dr
Frankfort, KY, 40601
Franklin County
$143,000 3 2.10 Exclusive  11/29/2018 View Street
Map it
Email Info
201-484750 3256 N Highway 259
Hardinsburg, KY, 40143
Breckinridge County
$45,000 3 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-503727 207 Canyon Ridge Rd
Wellington, KY, 40387
Menifee County
$76,000 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-510934 5685 Old State Rd
Guston, KY, 40142
Meade County
$60,000 3 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-513130 109 W Chestnut St
Carlisle, KY, 40311
Nicholas County
$73,000 3 2.00 Exclusive  11/29/2018 View Street
Map it
Email Info
201-528046 330 Brookside Dr
Danville, KY, 40422
Boyle County
$175,000 4 3.00 Extended  11/29/2018 View Street
Map it
Email Info
201-536556 1504 Robinson St
Grayson, KY, 41143
Carter County
$46,400 3 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-537032 307 Liberty St
Carlisle, KY, 40311
Nicholas County
$40,000 3 1.00 Exclusive  11/29/2018 View Street
Map it
Email Info
201-546596 38 Harrison Holw
Belfry, KY, 41514
Pike County
$7,000 0 0.00 Extended  11/29/2018 View Street
Map it
Email Info
201-547160 324 Malone Rd
Bradfordsville, KY, 40009
Marion County
$40,000 3 2.00 Exclusive  12/07/2018 View Street
Map it
Email Info
201-550376 3904 Taffy Rd
Whitesville, KY, 42378
Ohio County
$50,000 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-557096 237 Wright St
Frankfort, KY, 40601
Franklin County
$40,000 3 1.00 Extended  11/29/2018 View Street
Map it
Email Info
201-560972 5457 Ky Route 680
Grethel, KY, 41631
Floyd County
$76,000 4 2.10 Extended  11/29/2018 View Street
Map it
Email Info
201-576631 67 Snake Lick Rd
Berry, KY, 41003
Harrison County
$45,000 3 2.00 Exclusive  11/29/2018 View Street
Map it
Email Info
201-580027 255 Kingsway Dr
Frankfort, KY, 40601
Franklin County
$65,000 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
1 | 2 | 3 | 

Search Results for HUD Homes in KY

1 | 2 | 3 | 
47 listings found
List Gallery
Save Search Email Search View Map Export to Display: 
5
10
20
Property Case Address Price Status Bed Bath Listing Period Bid Open Date Details 
201-580611 2410 Paddock Ln
Louisville, KY, 40216
Jefferson County
$88,000 4 1.00 Exclusive  11/30/2018 View Street
Map it
Email Info
201-580733 2294 Josephine Rd
Stamping Ground, KY, 40379
Scott County
$108,000 4 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-583071 104 Jonathan Ct
Somerset, KY, 42503
Pulaski County
$108,900 4 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-590501 13255 Dawson Springs Rd
Crofton, KY, 42217
Christian County
$45,000 3 1.00 Exclusive  12/07/2018 View Street
Map it
Email Info
201-601254 1044 Scenic Dr
Radcliff, KY, 40160
Hardin County
$132,300 3 2.00 Extended  11/29/2018 View Street
Map it
Email Info
201-604473 8180 Georgetown Rd
Owenton, KY, 40359
Owen County
$69,000 3 2.00 Exclusive  12/07/2018 View Street
Map it
Email Info
202-019773 516 Wood Street
Maysville, KY, 41056
Mason County
$25,000 3 1.00 Extended  11/29/2018 View Street
Map it
Email Info
1 | 2 | 3 |