What is an FHA Loan and Is It Right for You?

Source: What is an FHA Loan and Is It Right for You?


What Is An FHA Loan And Is It Right For You?

Sponsored by:

The Federal Housing Administration insures what are called FHA loans. These mortgage loans provide opportunities for buyers with less-than-perfect credit or limited down payments to purchase homes, but they aren’t without potential pitfalls.

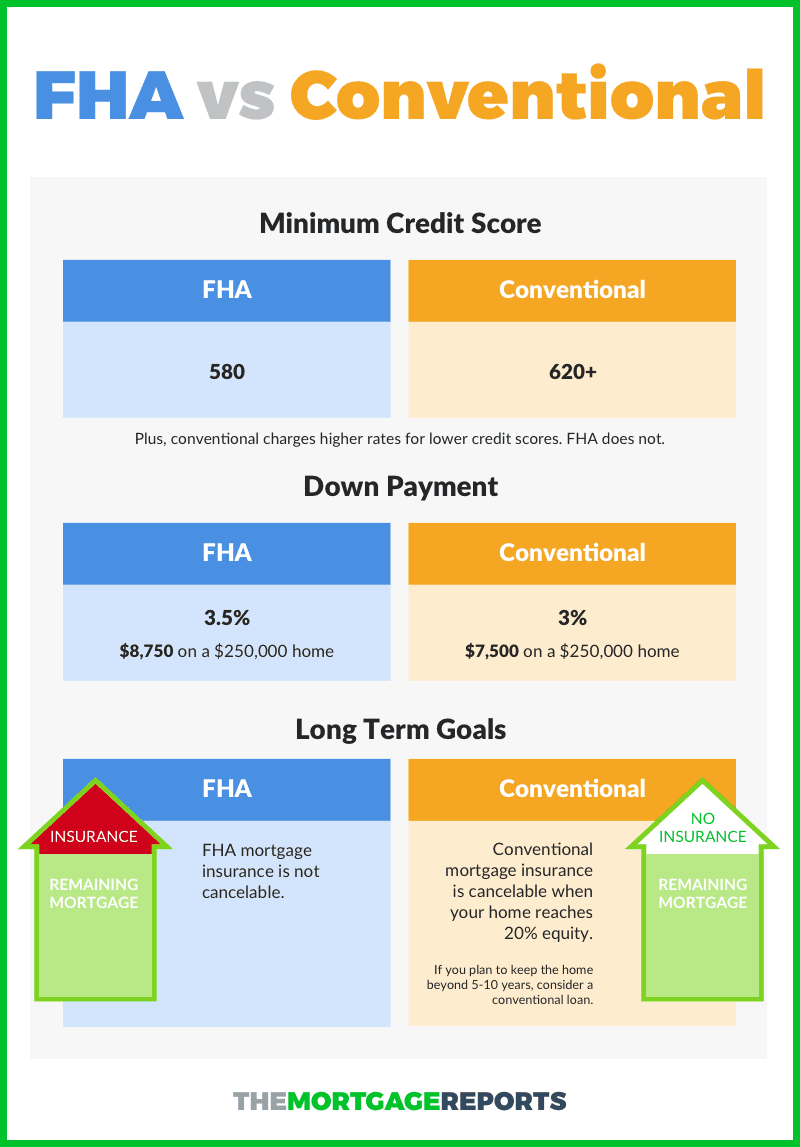
FHA loans are available to borrowers with a credit score of at least 580, and you have to make a minimum 3.5% down payment. They’re a popular option for first-time home buyers.

Lenders such as banks and credit unions issue the mortgages, which are insured by the FHA. That protects the lender if the borrower defaults, which is why the terms are more favorable than a traditional mortgage.

Around eight million single-family homes have loans insured by the FHA.

What Can an FHA Loan be Used For?

You can use an FHA loan to refinance single-family houses, to buy a single-family home, to buy some multifamily homes and condos and certain mobile and manufactured homes. There are particular types of FHA loans that can be used to renovate an existing property or for new construction.

How is an FHA Loan Different from a Conventional Mortgage Loan?

The biggest differentiator between an FHA loan and a conventional mortgage is that it’s easier to qualify for an FHA loan. You may get a loan with a lower credit score than you would otherwise, and your mortgage insurance payments may be lower too.

There are also fewer restrictions as far as using gifts from family or donations for your down payment.

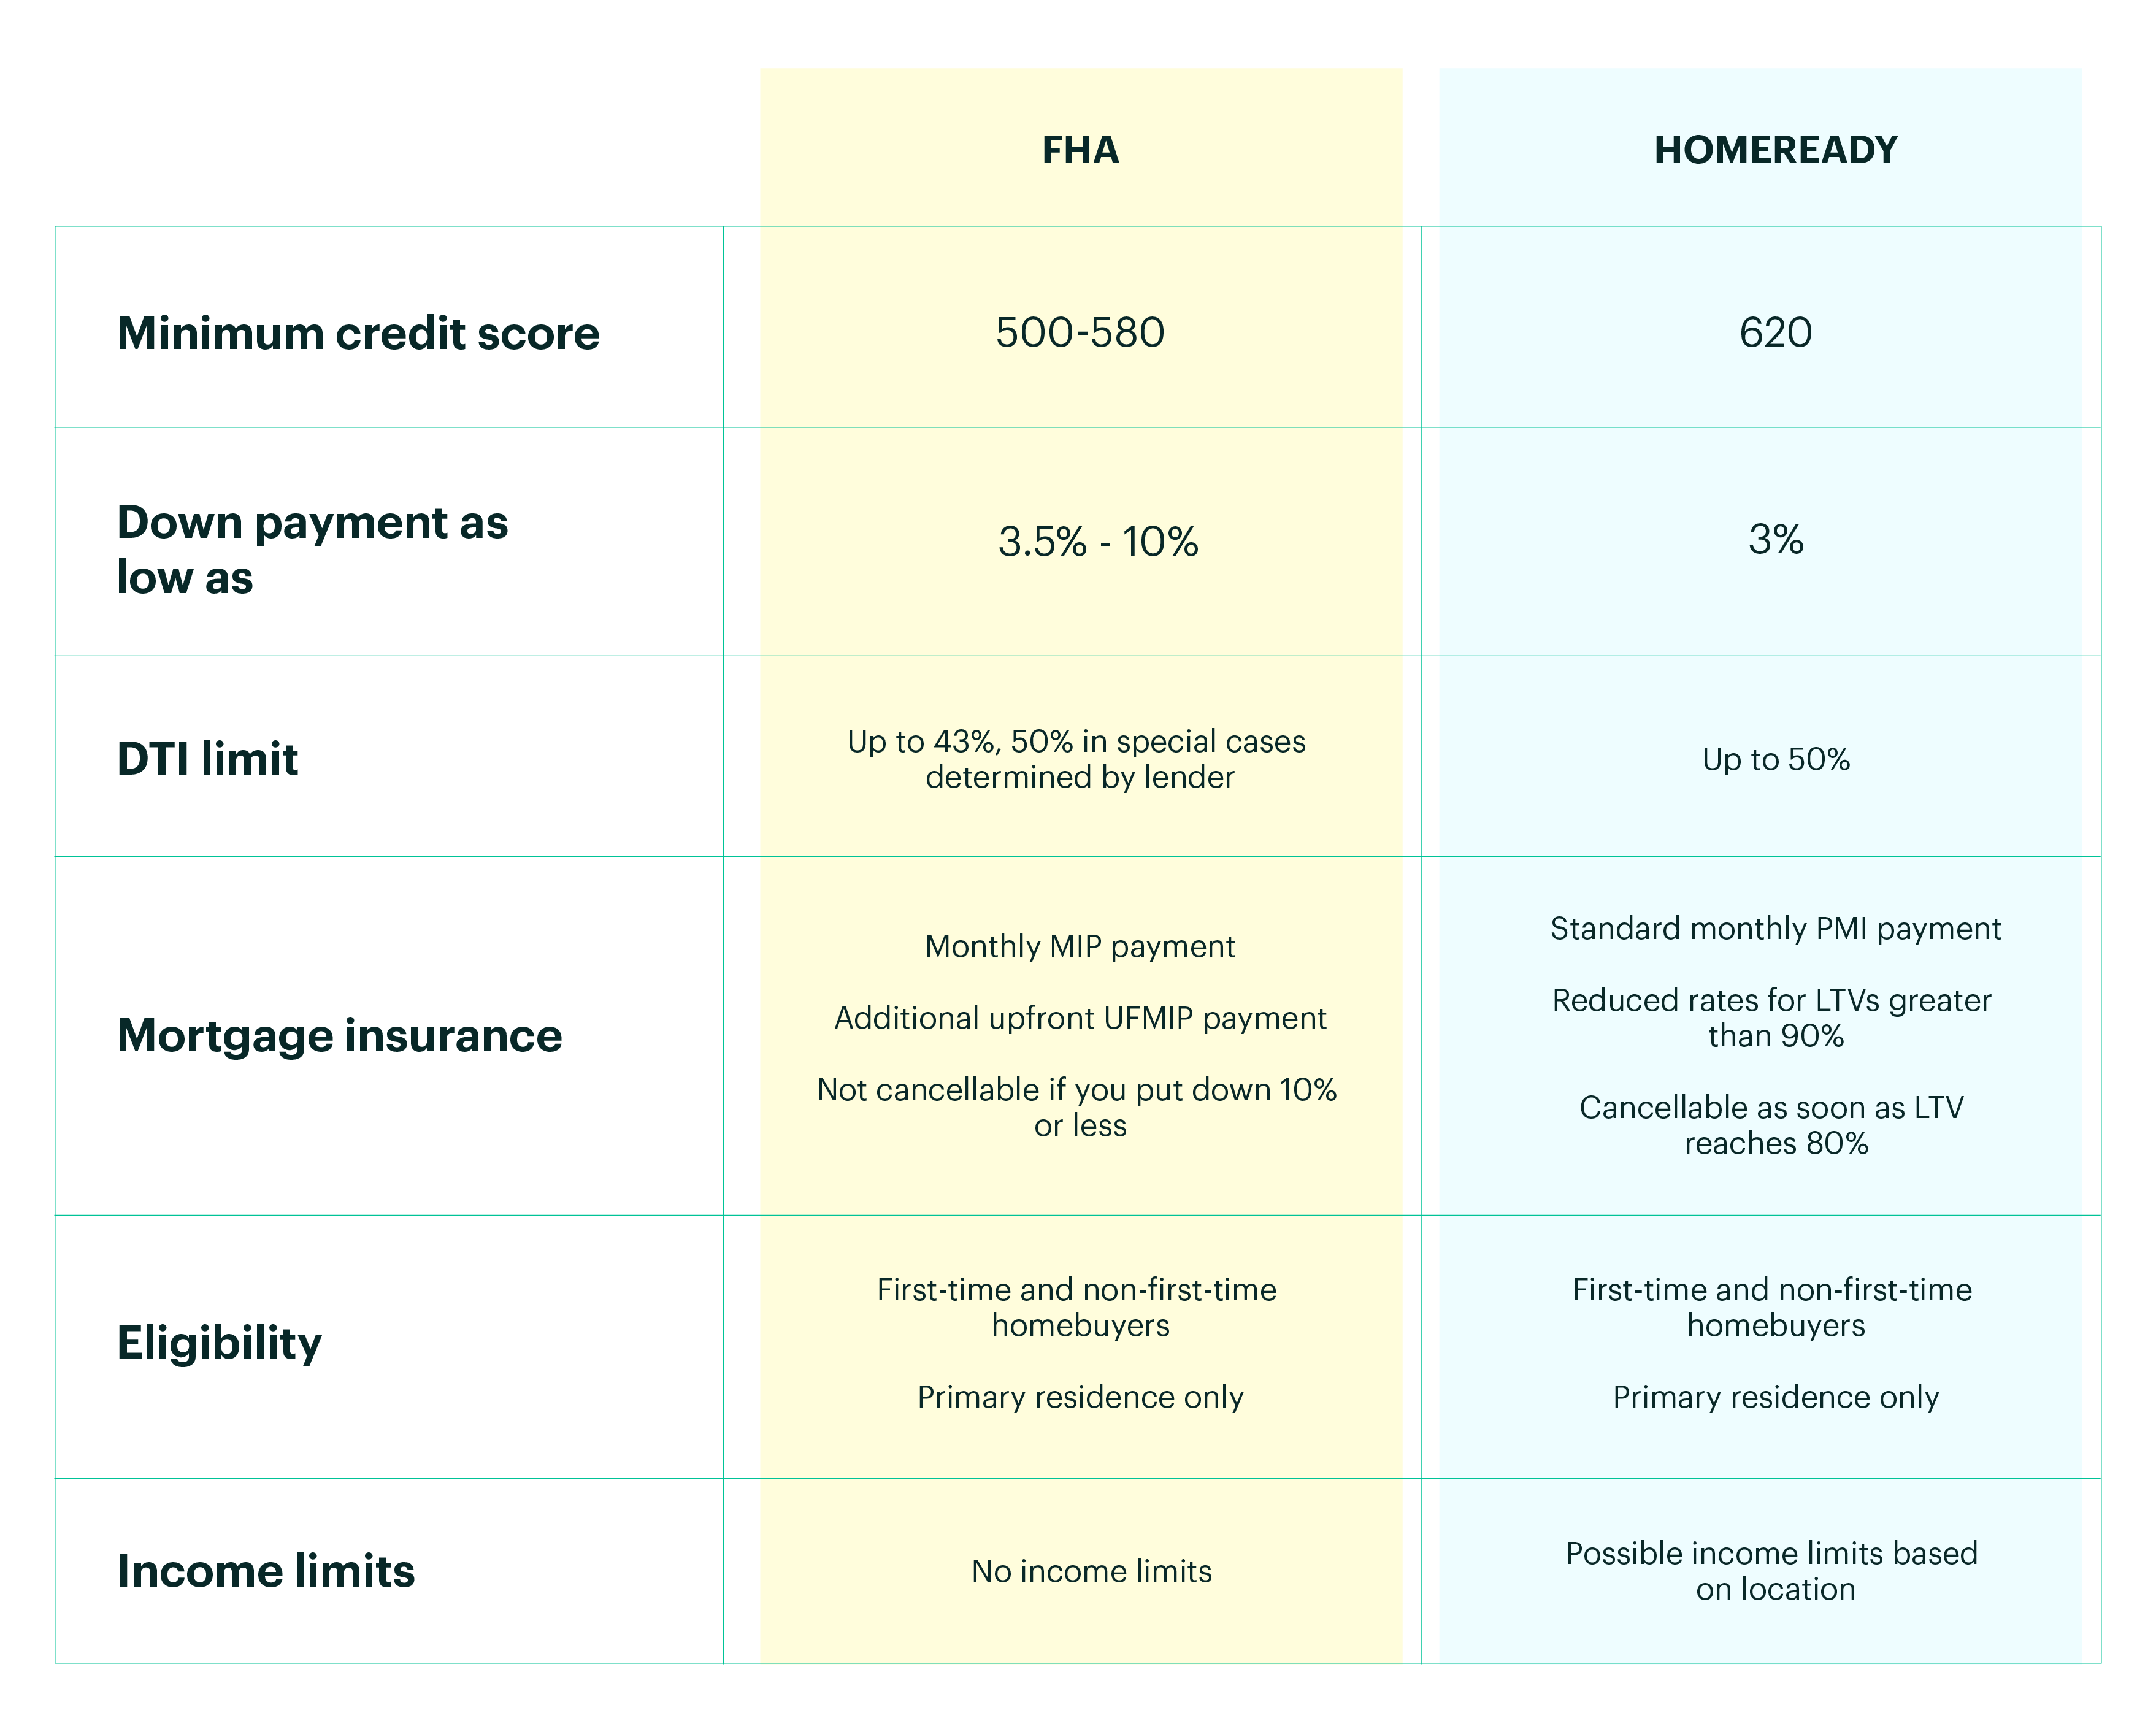
If you have a FICO score of at least 580, you have to make a 3.5% down payment. With a FICO score between 500 and 579, you’re required to make a 10% down payment, and mortgage insurance is required. Your debt-to-income ratio needs to be less than 43% whereas with a conventional loan it’s usually 36%. You do need to have proof of income and steady employment, as you would need with a conventional loan.

Are There FHA Loan Limits?

There are limits on the mortgage amount you can get with an FHA-guaranteed loan. The limits vary based on your county, and in 2020 these ranged from $331,760 to $765,600. The limit amounts are updated by the FHA each year based on fluctuations in home prices.

The Benefits of the FHA Loan

The primary benefits of an FHA loan are that buyers who wouldn’t otherwise qualify may be able to own a home and for a lower down payment. Sometimes the FHA will help facilitate coverage of closing costs. If you have problems making payments on an FHA loan you may be eligible for a forbearance period if you qualify.

What Are the Downsides of an FHA Loan?

You will have to pay an upfront mortgage insurance premium with an FHA loan to protect the lender. The fee is due when you close and it’s 1.75% of your loan. You will also have to pay an annual mortgage insurance premium for the life of your loan. The amount can range between 0.45% and 1.05%.

When you buy a home with an FHA loan, it has to meet strict standards in terms of health and safety.

Also, while there are set standards from the FHA, approved lenders can create their own requirements.

Applying for an FHA Loan

You’ll have to first find an FHA-approved lender to get one of these home loans. You’ll need some documents, including proof of U.S. citizenship, legal permanent residency, or eligibility to work in America. You’ll need bank statements for at least the past 30 days, and you’ll probably need to show pay stubs.

Some of the information your lender may be able to obtain on your behalf, such as your credit reports, tax returns and employment records.

There are advantages to an FHA loan because it expands homeownership to more people than conventional loans. It’s just important that if you’re considering this loan you understand the costs and that you’re not taking on more than you’re financially prepared for because of the less stringent approval requirements.

Written by Ashley Sutphin for http://www.RealtyTimes.com Copyright © 2020 Realty Times All Rights Reserved.

Kentucky FHA Mortgage Qualifying Guidelines

Kentucky FHA Loans

The FHA is actually not the lender. They insure the loans that are issued by FHA-approved lenders. FHA loans are gear more toward borrower’s with less than 20% down payment and credit issues in the past.

Qualifying for a FHA Loan Mortgage In Kentucky

Credit Scores and Down Payment Percentages – Each year, the rules for qualifying for these loans changes. For 2020, applicants need a minimum credit score of 580 in order to get the low down payment, which is 3.5 percent.

For those whose credit score is less than 580, they will have to come up with 10 percent for their down payment. This does not guaranteed a mortgage loan approval if you have the certain credit scores, just a the minimum required.

Compensating Factors for FHA loan Approval

The credit score is just one part of the story. The FHA will also evaluate the borrower’s bankruptcies, foreclosures, prior payment history on other debts. They will also want information on difficulties that kept the borrower from making payments on other debts in the past.

Negative strikes against qualifying for the loan include not having any credit history or a bankruptcy.

Someone with a bankruptcy will have to wait for two or more years after their bankruptcy before applying for an FHA-insured loan.

If you have late payments on debt obligations, it is best to wait until you have had a full year of on-time payments before you apply for a FHA-insured loan.

If you have had a foreclosure in the past, you may still be able to get a FHA-insured loan three years after your foreclosure. The lender will be looking at the circumstances behind the foreclosure.

If you have had any civil judgement against you for money owed, collections actions or unpaid/unresolved federal debt, the FHA-approved lender will be required by the FHA to establish that all of these outstanding issues are resolved or paid before you can go through closing.

Watch out for student loans if they are delinquent because sometime this can cause a lien against you in the form of a CAVIRS Alert with HUD

As you can see, many types of borrowers who would not be eligible for a traditional mortgage, or who would face exorbitant interest rates, will be able to qualify for a FHA-insured loan at attractive interest rates.

Employment and Income for a Kentucky FHA Loan

You must have an employment history that is steady for the last two years. Does not have to be same employer.

Your income has to be verifiable in some way, whether that be through pay stubs, your income tax returns. No bank statements or cash deposits , or undocumented income can be used for income qualifying purposes.

Image result for Employment and Income for a Kentucky FHA Loan

Debt-to-Income Ratio Requirements –

Depending on the automated underwriting system from Desktop Originator, your Debt-to-income ratio is the percentage of your income before taxes that you spend on monthly debt.

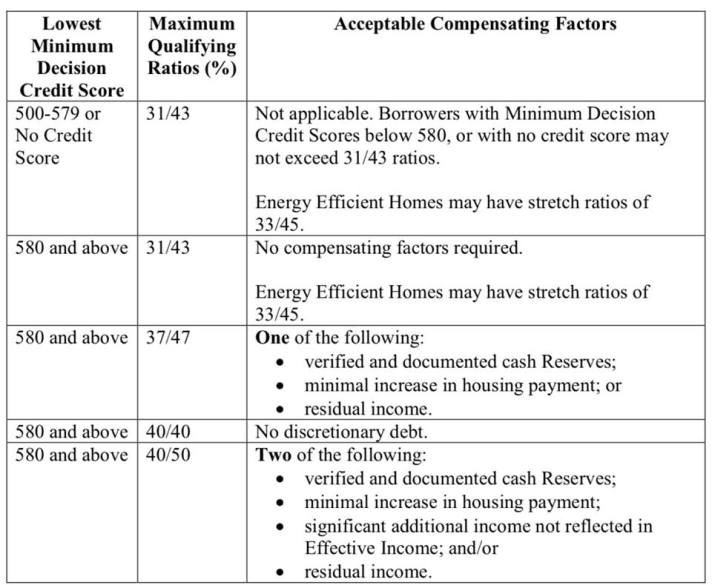
Taking into account the proposed mortgage payment as well as the other debts, the FHA requires that these debts all total less than 43 percent of your pretax income in order to qualify for the loan.

If your debt load is too high, you will struggle to pay all of your bills and mortgage expenses and care for yourself and your family.

55488026_2283733755207645_6787062571322048512_n (1)

Property Requirements for a Kentucky FHA Loan

It must be the place where you intend to reside. You must move into the home within 60 days of closing the loan. The home cannot be an investment. There will be an inspection to ensure that the home is safe and habitable.

It is really not too hard to pass FHA loans and the appraisal process.

23444444

Pros of FHA Loans –

  • New homebuyers and those who have lower credit scores or who have other blemishes on their credit history will often qualify for FHA-insured loans.

  • Even though these borrowers are considered “subprime” to a traditional lender, they will receive attractive interest rates through the FHA-insured mortgage programs.

  • The down payments required from borrowers are lower than those required by traditional mortgage lenders.

  • These loans can be combined with other forms of public assistance for lower income or new borrowers so that the borrower will not need to come up with a down payment of any kind.

Cons of FHA Loans –

  • Since the FHA is not actually the lender, and you have to go through FHA-approved lenders, you may not qualify due to stricter standards that the lender has for the loan.

  • Because you are not paying 20 percent as a down payment, the FHA requires two mortgage insurance premiums to be paid. One is an upfront premium that is 1.75 percent of the loan amount. Lenders often will allow you to make that mortgage insurance premium a part of your loan. The second is an annual mortgage insurance premium that is .45 percent or 1.05 percent. This premium is paid monthly.

 FHA FINANCING

CREDIT REQUIREMENTS FOR KENTUCKY FHA FINANCING

What credit score do I need to qualify for a Kentucky FHA loan is one of the most common questions I hear from Kentucky homebuyers?

The short answer is you must have a minimum credit score of 500 to be eligible for an FHA loan in Kentucky.  Anything lower than 500 disqualifies you from consideration for an FHA loan.

There are two sets of credit score requirements for a Kentucky FHA Loan

One important thing to understand is that the Federal Housing Administration (FHA) does not lend money directly to home buyers. You will fill out an application with a regular lender just as you would if you were applying for any other type of mortgage. What the FHA does is ensure your loan to help protect the lender in case you default.

You will be required not only to meet the FHA guidelines to qualify for a loan but also meet any additional qualifications required by the lender. This means there are two sets of requirements you have to meet with your credit score.

1. The first set of requirements comes from the Department of Housing and Urban Development (HUD). HUD oversees the FHA and determines what a borrower’s minimum eligibility requirements will be to obtain an FHA loan.

2. The second set of requirements comes from the mortgage lender. The mortgage lender has the right to add its requirements to those mandated by HUD.

What HUD requires of borrowers to be eligible for an FHA loan

The HUD Handbook 4000.1 includes the official guidelines when it comes to the FHA mortgage insurance program.

It states that in 2020 the Kentucky FHA borrowers with credit scores of 580 or higher are eligible for a 96.5% loan with 3.5% down.

Borrowers with credit scores from 500 to 579 are eligible for a 90% loan with 10% down.

Individuals with credit scores below 500 are not eligible for the FHA program.

What lenders may require of borrowers to be eligible for an Kentucky FHA loan

Lenders have the right to add requirements over and above the minimum requirements of HUD. These additional requirements are called overlays. Your lender may or may not require them.

This is not something that should come as a surprise to you, however. Requiring a credit score of 580 to 620 is not unusual. In addition to your credit score, you must have a manageable debt level that lenders are comfortable with and enough income to repay your loan.

What credit score do I need to qualify for FHA loan?

Each month Ellie Mae, the software company processing more than ⅓ of America’s mortgage loans, publishes an insight report for mortgage trends and standards. One of the things they track is average credit scores. The following is their report for November 2019 which shows what percentage of successful borrowers fall into what credit score ranges.

500 – 549    2.14%
550 – 599    5.20%
600 – 649    23.01%
650 – 699    34.74%
700 – 749    21.88%
750 – 799    10.87%
800+     1.89%

These percentages show that the majority of borrowers who successfully qualify for FHA loans fall into the 600 to 799 range. While it is true that some successfully qualify in the low range of 500 to 599, you have a much better chance of being approved for a loan with good terms and a low down payment if you fall into the higher range.


For your free credit report and analysis call us today at 502-905-3708 or email us at kentuckyloan@gmail.com


Joel Lobb (NMLS#57916)
Senior  Loan Officer
 
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
 
Company ID #1364 | MB73346


Text/call 502-905-3708
kentuckyloan@gmail.com


If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.


Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/


72875369_2600900606627287_6040534183682506752_n

How does Kentucky FHA Mortgage Rates work?

Kentucky FHA mortgage loans are backed by the Federal Housing Administration under the umbrella of HUD. FHA loans were developed to help borrowers that don’t have a large down payment and a weaker credit profile to buy and refinance their home mortgage loan.

​Kentucky FHA rates are backed by the government, so they are typically lower than other mortgage rates in the secondary market like Conventional loans and portfolio loans at banks, but fall in line compatible to other backed government loans in the secondary market likeUSDA, VA, mortgage loans. Most people seeking FHA mortgages will get a 30 year, 20 year of 15 year fixed rate loan with the security of the house payment not changing. ​

​Lower Credit Standards and Credit Scores for FHA loans

FHA mortgages will go down to a 500 credit score with at least 10% down payment, and if your credit score is higher than 580, you can put the minimum of 3.5% down payment. Additionally, you need to be only 2 years removed from a Chapter 7 bankruptcy, or 1 year from a Chapter 13 bankruptcy.

​Mortgage Insurance on FHA loans

Mortgage insurance is required on most FHA loans and is usually for life of loan with everyone paying the same. If you have a higher credit score and a larger down payment, it would make sense to look at doing a conventional mortgage loan because they are based on your credit score, money down, and debt to income ratio and not for life of loan.

You can get a lower FHA mortgage insurance premium and not have to finance the premiums for life of the loan if you put more than 10% down payment and finance on a 15 year term.

​Why would you consider a FHA mortgage?

​My best opinion is this. ​​​If you have a bankruptcy that is less than 4 years, have a credit score lower than 660, and very little money down, I would recommend at looking to do a FHA mortgage Loan. Your chances of getting approved with likely result in a loan approval as opposed to doing a conventional loan backed by Fannie Mae.

Why would you consider a Conventional Loan?

My best opinion is this. If you have a bankruptcy over 4 years or longer, at least 5% down payment, a credit score of 680 or higher, I would look doing a conventional mortgage loan.


Video: Kentucky FHA mortgage rates and loan options explained
▶ Click to watch on YouTube


​I can help you understand what mortgage is correct for you. Please contact me below and I will be happy to answer any questions.

Got questions about your Kentucky mortgage? Contact Joel Lobb
Joel Lobb (NMLS#57916)
Senior Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708

kentuckyloan@gmail.com


If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.


Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

How to qualify for a Kentucky FHA Home Loan ?

How to qualify for a Kentucky FHA Home Loan ?

Image result for fha loans ky


FHA stands for the Federal Housing Administration which is a government agency created to increase home-ownership across the United States all the way back in 1934. The agency itself doesn’t offer home loans but insures loan that are offered by private lenders (i.e. mortgage companies).

It’s important to understand the different types of loan programs available to you and what benefits and drawbacks there are to each type.

For example, if you’re looking to find a fixer upper this may not be the right loan program for you. But an FHA loan may be a better fit for you if you have little cash saved up for a down payment or if you don’t have a high credit score.

Kentucky FHA loan requirements:

  • At least 18 years old to apply
  • No age limit. just must be 18 years of age to apply.
  • Must occupy the home as a primary residence, no rental homes or investment property
  • An appraisal must be done by an FHA-approved appraiser.Typically FHA appraisal in Kentucky costs anywhere from low-end $325 to $525 with most FHA lenders in KY.
  • Home inspection is not required
  • Termite inspection not required
  • 2 years removed from Chapter 7 bankruptcy, and 1 year in Chapter 13 bankruptcy is possible to get a loan while in bankruptcy
  • Foreclosure or short sale on previous home mortgage requires 3 years removal from those dates.
  • Mortgage insurance (MIP) is required
  • Upfront Mortgage Insurance Premium is 1.75% and monthly mortgage insurance is .85% or .80% depending on loan term and loan to value.
  • Mortgage insurance is for life of loan.
  • No matter your credit scores, everyone pays the same mortgage insurance premiums.
  • Must have 2 years of employment history proving a reliable source of income
  • 500 FICO score requirement with at least 10% down payment
  • 580 FICO score requirement with at least 3.5% down payment
  • Gifts and down payment assistance programs are allowed to meet your down payment requirements. Cannot come from seller, but seller can contribute up to 6% of the sales price toward buyer’s closing costs and prepaids.
  • Student loan payments are factored into the debt-to-income ratio when applying. Typically if loans are deferred, or in an income=based repayment plan, the FHA underwriters will use 1% of the outstanding balance, which sometimes can make it difficult to qualify.
  • Your debt-to-income ratio must not be higher than 31% or total debt obligation cannot be higher than 43% of your current income. This is for a manual underwriter, meaning that if the AUS underwriting system by mortgage lenders will approve you for a higher debt to income ratio, that is fine.


Joel Lobb (NMLS#57916)
Senior  Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346

Text/call 502-905-3708kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

FHA vs Conventional Infograhic

Student Loans In Collections, What Can I Do to get Approved For A Kentucky Mortgage ?

Student Loans In Collections, What Can I Do?
If you have public student loans in collections, you really have three options to resolve it so it is not a CAIVRS issue.
1.      Pay it off in full – Not typically an option because very rarely do the clients have the funds to do so.
2.      Consolidation – Only takes about 90 days to consolidate and resolve CAIVRS issues. However, you push forward the last activity dates, DLA, and also introduce a new credit trade line that dilutes the length of the credit history. So you will normally see a drop in credit score.
3.      Rehabilitation – It is the slowest of all the options, but is the best thing for the clients’ credit scores. It is a 9 month commitment and once the client makes 9 consecutive payments, they will change the collection status to a good standing status. This will typically net a 40-100 point boost in the score depending on how many other collections are on the credit report.
If your client does not know who is servicing the student loan, they can contact the Student Loan Default Resolution Team at 1-800-621-3115 or visit the website at myeddebt.ed.gov
Bonus Tip: Private student loans do not adhere to consolidation or rehabilitation rules. If the client has private student loans in collections they will need to pay them off in full, or they will need to set up a payment plan on them. They will still remain in collections with a payment, but if you can get a qualified credit score you can push forward the loan including the liability payment towards the debt to income ratio.
As always, we bring you the best content so you can do what you do best, CLOSE LOANS! If you aren’t already sending us every credit challenged borrower you have, what is stopping you?
Guidelines for KY FHA, VA, USDA and VA Mortgage loans with Student Loans on A Credit Report:
Kentucky Fannie Mae or Conventional Guidelines for Student Loans:
  • If a monthly payment is on the credit report, the lender may use that amount for qualifying purposes.
  • If a monthly payment is on the credit report is incorrect, the lender may use the monthly payment on the most recent student loan statement
  • If the monthly payment on the credit report is zero, the lender must use one of the following options to calculate the payment for qualifying purposes
  1. Document the borrower is on an income driven payment plan and the actual monthly payment is zero
  2.  Use 1% of the outstanding student loan balance as the monthly payment
  3. Calculate a fully amortized payment using documented loan repayment terms
Kentucky FHA Mortgage Loans Guidelines:
Regardless of the payment status (currently in payment or deferred), the lender must use either:
  • The greater of:
  1. 1% of the outstanding balance; or
  2. The monthly payment reported on the credit; or
  •  Calculate a fully amortized payment using documented loan repayment terms
Kentucky USDA or Rural Housing Guidelines:
 
 
Regardless of the payment amount reporting on the credit, the lender must include the payment as follows:
  • A permanent amortized, fixed payment may be used in the debt ratio when the lender retains documentation to verify the payment is fixed, the interest rate is fixed, and the repayment term is fixed.
  • Payments for deferred loans, Income Based Repayment (IBR), Graduated, Adjustable, and other types of repayment agreements which are not fixed cannot be used in the total debt ratio calculation. One percent of the loan balance reflected on the credit report must be used as the monthly payment. No additional documentation is required.
Kentucky  VA Mortgage Guidelines for Student Loan:
  • If the borrower can document the student loan will be deferred 12 months from the closing date, the monthly payment does not need to be considered
  • If a student loan is in repayment or scheduled to begin repayment within 12 months from the closing date, the threshold payment amount must be calculated by  using 5% of the loan balance divided by 12 months
  • If the payment reporting on the credit report is greater than the threshold payment calculation amount, then the credit report payment must be used for ratios.
  • If the payment reporting on the credit report is less than the threshold payment calculation and the lender is using the lower payment to qualify the borrower then:
  1. A statement from the student loan servicer reflecting the actual loan terms and payment information must be included in the file.
  2. The statement must be dated within 60 days of closing
  3. It is the underwriter’s discretion to use the lower payment

As you can see, Fannie Mae or Conventional loans is the most lenient when it comes to qualifying for a mortgage loan with someone that has a lot of student loans on their credit report.