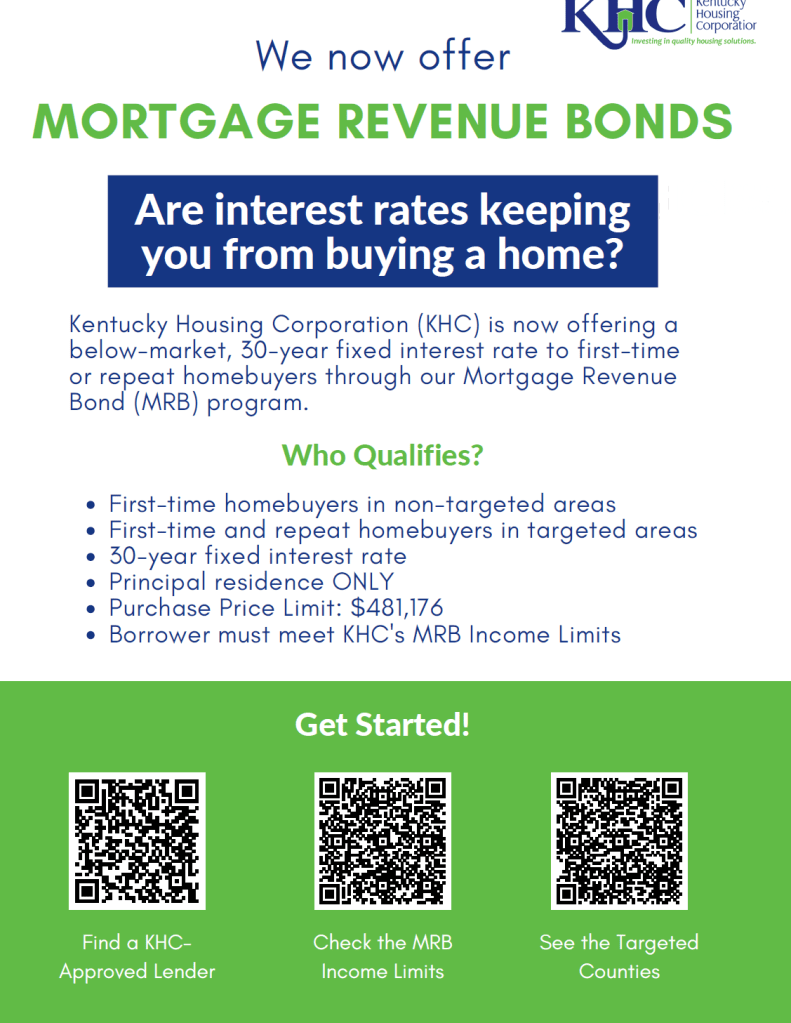
Kentucky Housing Corp KHC New income limits and Purchase Price Limits for 2024 Kentucky Homebuyer’s

The income limitations listed below are imposed by federal law.

Failure to comply with them may create adverse consequences for Kentucky Housing Corporation and its bondholders.

Funding Source: MRB (Purchase Price Limit – $510,939)

County

1-2

Person

3+

Person


County

1-2

Person

3+

Person


County

1-2

Person

3+

Person

Adair**

80,800

92,920

Grant

87,480

102,060

McLean

92,325

106,174

Allen

86,160

100,520

Graves

84,720

98,840

Meade

91,005

104,656

Anderson

91,345

105,047

Grayson

80,800

92,920

Menifee

96,960

113,120

Ballard

88,440

103,180

Green**

80,800

92,920

Mercer

92,105

105,921

Barren**

80,800

92,920

Greenup**

85,560

99,820

Metcalfe

96,960

113,120

Bath

96,960

113,120

Hancock

92,325

106,174

Monroe**

80,800

92,920

Bell

96,960

113,120

Hardin

93,245

107,232

Montgomery

85,920

100,240

Boone**

104,800

120,520

Harlan

96,960

113,120

Morgan

96,960

113,120

Bourbon

95,200

109,480

Harrison

93,120

107,324

Muhlenberg

86,400

100,800

Boyd**

85,560

99,820

Hart**

80,800

92,920

Nelson

91,605

105,346

Boyle

88,800

103,600

Henderson**

92,245

106,082

Nicholas

83,760

97,720

Bracken

104,800

120,520

Henry

96,400

110,860

Ohio

80,800

92,920

Breathitt

96,960

113,120

Hickman

87,480

102,060

Oldham

96,400

110,860

Breckinridge

84,360

98,420

Hopkins**

82,800

96,600

Owen

86,400

100,800

Bullitt

96,400

110,860

Jackson

96,960

113,120

Owsley

96,960

113,120

Butler

80,800

93,940

Jefferson**

96,400

110,860

Pendleton

104,800

120,520

Caldwell

80,800

93,660

Jessamine

95,200

109,480

Perry

96,960

113,120

Calloway**

90,720

105,840

Johnson

96,960

113,120

Pike

96,960

113,120

Campbell**

104,800

120,520

Kenton**

104,800

120,520

Powell

96,960

113,120

Carlisle

84,360

98,420

Knott

96,960

113,120

Pulaski**

80,800

92,920

Carroll

80,800

92,920

Knox

96,960

113,120

Robertson

96,960

113,120

Carter

96,960

113,120

Larue

93,245

107,232

Rockcastle

96,960

113,120

Casey

96,960

113,120

Laurel**

80,800

92,920

Rowan

96,960

113,120

Christian**

92,785

106,703

Lawrence

96,960

113,120

Russell

81,840

95,480

Clark**

95,200

109,480

Lee

96,960

113,120

Scott**

95,200

109,480

Clay

96,960

113,120

Leslie

96,960

113,120

Shelby

100,500

115,575

Clinton

96,960

113,120

Letcher

96,960

113,120

Simpson

87,000

101,500

Crittenden

92,040

107,380

Lewis

96,960

113,120

Spencer

96,400

110,860

Cumberland**

80,800

92,920

Lincoln**

80,800

92,920

Taylor

84,720

98,840

Daviess**

92,325

106,174

Livingston

86,040

100,380

Todd

84,720

98,840

Edmonson

91,765

105,530

Logan

88,800

103,600

Trigg

92,785

106,703

Elliott

96,960

113,120

Lyon

92,485

106,358

Trimble

93,005

106,956

Estill

96,960

113,120

Madison**

92,045

105,852

Union

84,360

98,420

Fayette**

95,200

109,480

Magoffin

96,960

113,120

Warren**

91,765

105,530

Fleming**

80,800

92,920

Marion

85,680

99,960

Washington

92,245

106,082

Floyd

96,960

113,120

Marshall

92,405

106,266

Wayne

96,960

113,120

Franklin

91,985

105,783

Martin

96,960

113,120

Webster

81,240

94,780

Fulton**

80,800

92,920

Mason**

82,560

96,320

Whitley

96,960

113,120

Gallatin

104,800

120,520

McCracken**

92,285

106,128

Wolfe

96,960

113,120

Garrard**

87,120

101,640

McCreary

96,960

113,120

Woodford

95,200

109,480

Counties in Green are Targeted

d Census Tracts


The income limitations listed below are imposed by federal law.

Failure to comply with them may create adverse consequences for Kentucky Housing Corporation and its bondholders

Funding Source: MRB (Purchase Price Limit – $510,939)

County

Census Tracts

1-2 Persons

3+ Persons

Adair

9703.00

96,960

113,120

Barren

9504.01, 9506.01

96,960

113,120

Boone

0703.01

125,760

146,720

Boyd

0302.00, 0303.00, 0308.00

96,960

113,120

Calloway

0103.03, 0104.00

96,960

113,120

Campbell

0501.00, 0506.00

125,760

146,720

Christian

2002.00, 2003.00, 2008.00, 2015.02

96,960

113,120

Clark

0201.06, 0202.01

114,240

133,280

Cumberland

9502.00

96,960

113,120

Daviess

0003.00

99,120

115,640

Fayette

0004.00, 0018.00, 0019.00, 0020.01

114,240

133,280

Fleming

9201.00, 9204.00

96,960

113,120

Fulton

9601.00

96,960

113,120

Garrard

9703.00

96,960

113,120

Green

9302.00, 9303.00

96,960

113,120

Greenup

0406.00

96,960

113,120

Hart

9703.02, 9704.00

96,960

113,120

Henderson

0203.00

99,600

116,200

Hopkins

9704.00, 9706.00

96,960

113,120


Jefferson

0002.01, 0004.00, 0006.00, 0009.00, 0014.00, 0018.00,

0023.00, 0024.01, 0027.00, 0030.00, 0035.02, 0038.00,

0041.00, 0043.01, 0043.02, 0050.00, 0059.01, 0059.02,

0065.00, 0110.07, 0127.01


115,680


134,960

Kenton

0651.00, 0671.00

125,760

146,720

Laurel

9701.00, 9702.01, 9702.02, 9703.00, 9705.00,

9709.00,9710.01 9710.03

96,960

113,120

Lincoln

9201.03, 9203.01, 9204.00

96,960

113,120

Madison

0102.02, 0103.02, 0103.03, 0104.00, 0105.00, 0112.01,

0112.02, 0113.01,

100,800

117,600

Mason

9602.02

96,960

113,120

McCracken

0301.00, 0302.00

99,360

115,920

Monroe

9302.00, 9304.00

96,960

113,120

Pulaski

9301.01, 9302.02, 9303.01, 9303.02, 9304.01, 9306.00,

9308.01, 9308.02, 9311.01, 9311.04,

96,960

113,120

Scott

0401.01

114,240

133,280

Warren

0102.00, 0103.00, 0108.04

102,480

119,560


Mortgage Revenue Bonds (MRB)

Joel Lobb  Mortgage Loan Officer

American Mortgage Solutions, Inc.
10602 Timberwood Circle
Louisville, KY 40223
Company NMLS ID #1364

Text/call: 502-905-3708

email: kentuckyloan@gmail.com


http://www.mylouisvillekentuckymortgage.com/


NMLS 57916  | Company NMLS #1364/MB73346135166/MBR1574

The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people.
NMLS ID# 57916, (www.nmlsconsumeraccess.org).

5 Things to Know about buying a house and getting a Mortgage Loan approval in Kentucky for 2023


1. Do Mortgage Rates Change Daily?

Just like the gas prices at the pump, mortgage rates can change daily or throughout the day. Typically mortgage rates are published at 10-11 am daily by most lenders and you can lock up through the close of business which is usually around 6-7 PM. Mortgage rates can change up or down throughout the day based on various financial, economics, and geopolitical news in the US Financial markets and World markets. Generally speaking, good economic news is bad for rates and vice versa, bad economic news is good for mortgage rates.

The good news is this: Once you find a home and get it under contract, you can lock your mortgage loan rate. Typically it takes about 30-45 days to close a mortgage loan in Kentucky, so the typical lock is for 30-60 days. If rates get better you may be able to negotiate a better rate with your lender, but they usually have to improve by at least 25 basis points (.25) to do that. Not all lenders offer this option. The longer you lock the loan, the greater the costs. It is usually free to lock in a loan for up to 90 days without having to pay a fee.

What a lot of lenders are experiencing now is that some loans don’t close on time for various reasons. You can always extend the lock on the loan but it will costs you usually .125 basis points to do so. If you let the lock expire on the loan, then you have to take worse case pricing on that day when you go to relock. It is usually best to extend the lock on your loan.

2. What kind of Credit Score Do I need to qualify?

When applying for a mortgage loan, lenders will pull what they call a “tri-merge” credit report which will show three different fico scores from Trans union, Equifax, and Experian. The lenders will throw out the high and low score and take the “middle score” For example, if you had a 614, 610, and 629 score from the three main credit bureaus, your qualifying score would be 614. Most lenders will want at least two scores. So if you only have one score, you may not qualify. Lenders will have to pull their own credit report and scores so if you had it ran somewhere else or saw it on a website or credit card you may own, it will not matter to the lender, because they have to use their own credit report and scores.
Most lenders will pull your credit report for free nowadays so this should not be a big deal as long as your scores are high enough.
The Secondary Market of Mortgage loans offered by FHA, VA, USDA, Fannie Mae, and KHC all have their minimum fico score requirements and lenders will create overlays in addition to what the Government agencies will accept, so even if on paper FHA says they will go down to 580 or 500 in some cases on fico scores, very few lenders will go below the 620 threshold.
If you have low fico scores it may make sense to check around with different lenders to see what their minimum fico scores are for loans.
The lenders I currently deal with have the following fico cutoffs for credit scores:
FHA–580 minimum score
VA—-580 minimum score
Fannie Mae–620 minimum score
USDA–620 minimum score
KHC with Down Payment Assistance –620 minimum score.

As you can see, 580-620 is the minimum score with most lenders for a FHA, VA, or Fannie Mae loan, is required for the no down payment programs offered by USDA for Kentucky for First Time Home Buyers wanting to go no money down.

3. What are the down payment requirements?

The most popular programs for Kentucky First Time Home Buyers usually involves one of the following housing programs outlined in bold below:
FHA:

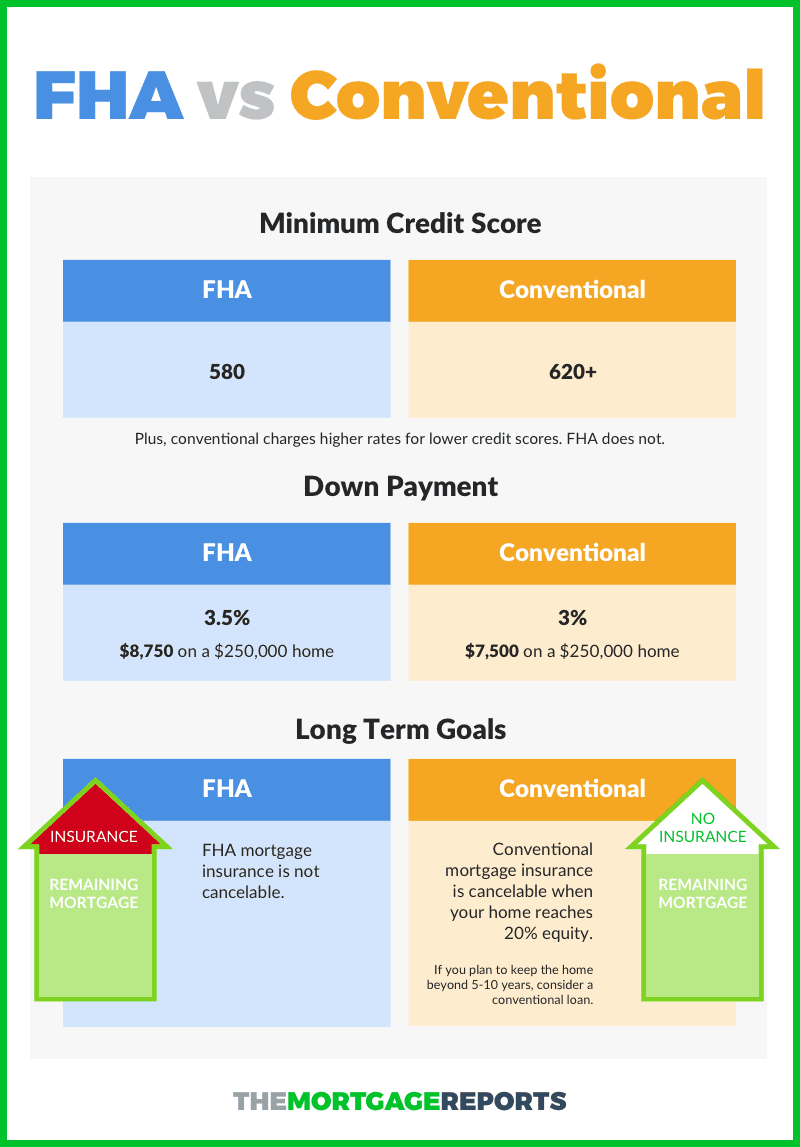
FHA will allow a home buyer to purchase a house with as little as 3.5% down. If your credit scores are low, say 680 and below, a lot of times it makes sense to go FHA because everyone pays the same mortgage insurance premiums no matter what your score is, and the down payment can be gifted to you. Meaning you really don’t have to have any skin into the game when it comes to down payment.

They even allow down payment assistance for down payment requirements of 3.5% through eligible parties like Kentucky Housing, Welcome Home Grants and Louisville KY and Covington Kentucky Down Payment Grants.

Lastly, FHA will allow for higher debt to income ratios with sometimes getting loan pre-approvals up to 55% of your total gross monthly income. So if you have a debt to income ratio of over 50%, Fannie Mae will not do the loan and USDA usually likes their debt to income ratios no more than 45%.

Think back to the last time you financed a purchase — be it a home, automobile, or what have you… You may remember having heard the term “debt-to-income ratio.” Today I want to spend some time going over exactly what this ratio is, and to also touch on how it can effect your personal finances.

4. What is your debt-to-income ratio?

Commonly referred to as your “DTI,” your debt-to-income ratio is a personal finance benchmark that relates your monthly debt payments to your monthly gross income.
As an example… Let’s say that your gross monthly salary is $5,000 and you are spending $2,800 of it toward monthly debt payments. In that case, your DTI would be an unhealthy 56%.
This version of your DTI is sometimes referred to as your “back-end” DTI. This is often broken down further to give a front-end debt-to-income ratio, which is a component of your back-end DTI.

How to calculate your front-end DTI for a Kentucky Mortgage Loan Approval

Your front-end DTI is calculated by dividing your monthly housing costs by your monthly gross income. Front-end DTI for renters is simply the amount paid in rent, whereas for homeowners it is the sum of mortgage principal, interest, property taxes, and home insurance (i.e., your PITI) divided by gross monthly income.

From above, if that $2,800 in debt payments is attributable to $1,500 in housing costs and $1,300 in non-housing costs, then your front-end DTI is $1,500/$5,000 = 30% (and your back-end ratio is still 56%, as calculated above).
Fannie Mae:
Fannie Mae requires just 3% down with their new Home Possible Program, but if you use their traditional mortgage loan, then 5% is the Fannie Mae Standard. Fannie Mae will go down 620 score, but if your scores are below 680, I would look seriously at the FHA loan program because Fannie Mae has steep increases to the interest rate and the mortgage insurance premiums if your scores are low.
A couple of good things about Fannie Mae is that you can buy a larger priced home and have a large loan amount due to FHA only allowing most Kentucky Home Buyers a maximum mortgage loan amount of $356,000 for a max FHA loan and $545,000 for Fannie Mae Conventional loans in Kentucky for 2020.
Lastly when it comes to mortgage insurance, FHA mortgage insurance premiums are for life of loan while Fannie Mae mortgage insurance premiums drop off when you develop 80% equity position in your house.
But as a tell most people, nobody has a loan for 30 years, and the average mortgage is either refinanced or home sold within the first 5-7 years.
VA Loans-

VA loans offer eligible Veterans and Active Duty Personnel to buy a home going no money down with no monthly mortgage insurance. This is probably the best no money down loan out there since the rates are traditionally very low on comparison to other government insured mortgages and no monthly mortgage insurance. The VA loan can be used anywhere in the state of Kentucky with the maximum VA loan limit being removed for 2021
USDA Loans-

USDA loans offer people buying a home in rural areas (typically towns of $20k or less) to buy a home going zero down. You cannot currently own another home and there is household income limits of $90,200 for a household family of four, and up to $119,300 for a household of five or more. You search USDA website for eligible areas and household income limits below at the yellow highlighted link :

KHC or Kentucky Housing-
Kentucky First Time Home Buyers typically use KHC for their down payment assistance. KHC currently offers $10,000 for down payment assistance and sometimes throughout the year they will offer low mortgage rates on their mortgage revenue bond program.

The down payment assistance usually never runs out because you have to pay it back in the form of a second mortgage. It helps a lot of home buyers that want to buy in urban areas that cannot utilizer the USDA program in rural areas. Most of the time the first mortgage is a FHA loan tied with the 2nd mortgage fore down payment assistance. All KHC programs require a 620 score and rates are locked for 45 days.

5. What if I have had a bankruptcy or foreclosure in the past?

FHA and VA are the easiest on previous bankruptcies. FHA and VA both require 2 years removed from the discharge date on a Chapter 7. If you are in the middle of a Chapter 13, FHA will allow for financing with a 12 month clean history payment to the Chapter 13 courts, and with trustee permission.

VA requires 2 years removed from a foreclosure (sheriff sale date of home) and FHA requires 3 years.

USDA requires 3 years removed from both a foreclosure and bankruptcy, but on the foreclosure they do not go off the sale date. This may save you a little time if you had a previous foreclosure.

Fannie Mae (Conventional Loan)

Fannie Mae is by far the strictest. They require 4-7 years out of a foreclosure or bankruptcy

If you have questions about qualifying as first time home buyer in Kentucky, please call, text, email or fill out free prequalification below for your next mortgage loan pre-approval.

Bankruptcy Requriements for a FHA, VA, USDA, and Fannie Mae Loan Approval in Kentucky
click on link to apply for free mortgage quote

Joel Lobb
Senior Loan Officer

(NMLS#57916)

Text or call phone: (502) 905-3708

email me at kentuckyloan@gmail.com

http://www.mylouisvillekentuckymortgage.com/

The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the views of my employer. Not all products or services mentioned on this site may fit all people

CONFIDENTIALITY NOTICE: This message is covered by the Electronic Communications Privacy Act, Title 18, United States Code, §§ 2510-2521. This e-mail and any attached files are deemed privileged and confidential, and are intended solely for the use of the individual(s) or entity to whom this e-mail is addressed. If you are not one of the named recipient(s) or believe that you have received this message in error, please delete this e-mail and any attached files from all locations in your computer, server, network, etc., and notify the sender IMMEDIATELY at 502-327-9770. Any other use, re-creation, dissemination, forwarding, or copying of this e-mail and any attached files is strictly prohibited and may be unlawful. Receipt by anyone other than the named recipient(s) is not a waiver of any attorney-client, work product, or other applicable privilege. E-mail is an informal method of communication and is subject to possible data corruption, either accidentally or intentionally. Therefore, it is normally inappropriate to rely on legal advice contained in an e-mail without obtaining further confirmation of said advice.

Kentucky FHA Loans in the State of Kentucky for 2022

Advantages of Kentucky FHA Mortgage Loans

  • You can often make a down payment as low as 3.5 percent down to a 580 credit score
  • You can finance a home with a 500 credit score with 10% down payment.
  •  Kentucky FHA loans are assumable meaning that if you have a good rate on your current mortgage and the potential buyer of your home meets FHA guidelines, then he can assume your low rate mortgage
  • Kentucky FHA loans offer streamline refinancing without credit score minimums, verification of income, and no appraisals to refinance to a lower rate making it easier to qualify.
  • Kentucky FHA loans offer flexible terms when it comes to previous bankruptcy or foreclosures. 2 years removed from Chapter 7 with reestablished
  •  credit, or if a Chapter 13, one year in the payment plan is eligible for FHA financing.
  • Foreclosures on a past home. FHA will finance a home 3 years removed from the sale date of your foreclosure property
  • 30 year fixed rate mortgage with usually the best going rates on government insured loans like FHA, VA, USDA etc.
  • No prepayment penalty on Kentucky FHA loans.
  • Higher debt to income ratio requirements when compared to Conventional loans because most Fannie Mae Conventional loans cannot have a higher debt to income ratio than 45% on the back-end
  • You can make an FHA loan anywhere in the state of Kentucky with no geographical restrictions.
  • Will allow for down payment assistance and grants for borrowers minimum down payments in the State of Kentucky through the likes of KHC, Welcome Home Grant, and Kentucky Housing Down Payment Second Mortgage loans.
  • Kentucky FHA loans allow for unoccupied cosigner. For example, lets say you have a daughter that is getting ready to graduate college and does not have the income or credit history established yet to buy a home. FHA allows a family-member to co-sign for them to buy a home and you don’t have to occupy as primary residence. Note, FHA co-singers are not allowed to makeup for some that has bad credit, because they will take the lowest credit scores of both applicants. FHA usually allows for co-singers lack of income purposes only.
  • Can usually close within 30 days just like a regular conventional mortgage. No extra time to close an FHA loan in Kentucky versus other secondary market loans like VA, USDA, Fannie Mae.
  • You can use the FHA loan over and over. You can actually have two FHA loans open at the same time, but it gets tricky on this. Call or text me with more info if you have an FHA loan currently and would like to use FHA Financing again.
  • FHA loans aren’t just for first time home buyers in Kentucky.


Disadvantages of Kentucky FHA Mortgage Loans

  • There are loan limits in the State of Kentucky on FHA Mortgage loans. The maximum FHA loan in the state of Kentucky is $$420,680 for 2022.  So if you were needing to finance a loan over this amount, you would need to look at doing a Conventional loan with the updated 2021 Kentucky State Loan Limits for a Fannie Mae loan being $647,250
  • If buying a condo in Kentucky, FHA requires the condo development be FHA approved. There is a >>>list here of Kentucky FHA approved condos here.
  • Seller must have own the home for 90 days before you can make an offer on the home. This comes into play where the seller bought the home as an investor and rehabbed the property and wants to sell for a quick profit. FHA mandates seller must maintain for 90 days before you can write up an offer on it. Also called FHA Flipping Policy. Read more here  
  • There is mortgage insurance. This is one of the biggest disadvantages for FHA loans. But as I tell most people, nobody rarely has a loan for 30 years, so if it meets your payment and your cash to close requirement, I tell people to go with it because it can be refinanced down the road and you are getting one of the lowers 30 year fixed rates out there. Both upfront and monthly mortgage insurance premiums you have to pay HUD/FHA. These premiums change whenever FHA/HUD replenish their insurance pool to pay claims from defaults, but currently the FHA upfront mortgage insurance premium is 1.75% and monthly is .85% and .80% of the loan amount. If you happen do a 15 year term or shorter, the mortgage insurance is cheaper monthly with .45 and .70 respectively  each month. The upfront mortgage insurance is the same for a 30 year and 15 year at 1.75%
  • FHA Mortgage insurance can be on the loan for life of loan. This is a recent change made in 2016 when FHA lowered there premiums for upfront and monthly mi premiums, but made the mortgage insurance for life of loan for some FHA loans. 
  • If you put down more than 10% on the loan, or have at least 10% equity in the home for a refinance, you only have to pay mortgage insurance for 11 years before it automatically falls off.
  • Obviously you can refinance out of an FHA loan at anytime, since it does not a prepayment penalty, and you can potentially get a refund of your upfront mortgage insurance if paid off within 3 years on sliding scale.
  • I have incorporated some charts below to illustrate the different Kentucky FHA Mortgage Insurance premiums to explain it better.
  • The upfront mortgage insurance is usually financed into the loan, so it will look like you are borrowing more than the standard 3.5% down payment because this is financed into the loan. Some borrowers elect to pay it out of pocket upfront, but I have never seen this done in my 20 years of doing FHA loans in the State of Kentucky
  • Kentucky FHA Loans Greater Than 15 Years MIP Chart
  • 👇
    Base Loan Amt. LTV Annual MIP
    ≤$625,500 ≤95.00% 80 bps (0.80%)
    ≤$625,500 >95.00% 85 bps (0.85%)
    >$625,500 ≤95.00% 100 bps (1.00%)
    >$625,500 >95.00% 105 bps (1.05%)

    Kentucky FHA Loans Less Than or Equal to 15 Years MIP Chart👇

    Base Loan Amt. LTV Annual MIP
    ≤$625,500 ≤90.00% 45 bps (0.45%)
    ≤$625,500 >90.00% 70 bps (0.70%)
    >$625,500 ≤78.00% 45 bps (0.45%)
    >$625,500 78.01% – 90.00% 70 bps (0.70%)
    >$625,500 >90.00% 95 bps (0.95%)

    When can I get the FHA mortgage insurance off my Mortgage Loan? See chart below 👇👇

Image result for fha cancellation of mortgage insurance chart kentucky

  • Appraisals. On an FHA appraisal, the FHA appraiser has to turn on the utilities to make sure they are in worked order when he gets there. This is different that Conventional loan appraisals. A lot of realtors or buyers think that FHA loans are harder due to appraisals, but honestly, they’re really not. FHA puts these minimum HUD standards in place to make sure the home is in good working order and SAFE to live in. I.e.is there any lead based paint or chipping paint that could lead to poisoning  It is all about Safety with FHA and HUD on these appraisals. The value is determined just like a regular Conventional, USDA, VA appraisals whereas they compare the house to 3 recent homes sold in the area to get a value.
  • Some lenders don’t offer FHA loans due to their complexity and sale on the secondary market, so if you call a local lender in Kentucky and they don’t offer FHA loans, the reason is usually they don’t have the team in place to do them or don’t want to do them due to lack of experience on the secondary government market.
  • Government Liens. FHA will not be an option for you usually if you have unpaid federal tax liens, delinquency  on federal backed-government loans, or a claim with social security etc. FHA loans are ran through aCAVIRS alert system to check to see if you are delinquent on any federal oblation. If so, this swill stop you until you can clear the CAVIRS alert system. For example, I did a loan for a buyer that had a delinquent federal debt with his student loan that happened over 14 years old. It was off the credit report and title search, so I had to switch to a conventional loan to make the home loan work.
  • FHA loans are not good for second homes or investment properties. FHA loans are mainly for single family residence 1-4 unit, that are going to occupied primarily as main home.

In summary, FHA loans have few drawbacks other than the mortgage insurance in my opinion. It is a great first time home buyer program or borrowers with past credit problems to get into a house of their own with very little out of pocket, at a low 30 year fixed rate, and no prepayment penalty

Questions about qualifying for a FHA loan in Kentucky . Give me text, call or email below. Love to help you out on your next home or refinance in Kentucky

Read more below about specific FHA Loans in Kentucky.👇👇👇
Joel Lobb (NMLS#57916)
Senior  Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708

kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

Louisville Kentucky Mortgage Broker Offering FHA, VA, USDA, Conventional, and KHC Zero Down Payment Home Loans | October 17, 2018 at 3:54 pm | Tags: fha gift fundsfha loan kentuckyFHA Loans Kentucky Housing First time home buyerfha mortgagefha mortgage loangift funds for fha mortgagekentucky fha loans |

Louisville Kentucky Mortgage Rates for First Time Home Buyers


Do I qualify as a Kentucky first-time home buyer?

You are typically considered eligible to apply for first-time home buyer loans and benefits if you haven’t owned your principal residence within the past three years.

Some first-time home buyer assistance programs are even more lenient, offering financial aid in specific areas targeted for redevelopment, even to repeat buyers.


Kentucky First-time home buyer benefits

Benefits can include low- or no-down-payment loans, grants or forgivable loans for closing costs and down payment assistance, as well as federal tax credits with the Kentucky Housing Agency or KHC


Is there an income limit to qualify as a first-time home buyer?

Income limits come into play when you are applying for local, state or federal government assistance. Some national mortgage programs, such as loans issued or backed by the U.S. Department of Agriculture, also have household income limits.

Some low-down-payment conventional loans do, too.

In these cases, your income may be benchmarked to local county limits for low- and moderate-income households.

Lenders, even those working with loan programs authorized by a state housing agency, will likely consider your debt-to-income ratio when determining if you qualify.


How to qualify for a first-time home buyer grant

Grants or forgivable loans that typically don’t require repayment are available to low- and moderate-income borrowers through state first-time home buyer programs. Approval standards vary by program and location but often include household income and home sale price limits.

How to qualify for down payment assistance

Just as for grants, down payment and closing cost assistance is often offered by local and state housing authorities. Again, qualifications vary. Look for income and home sale price caps here, too.

Don’t be surprised if a first-time home buyer class is required to qualify for a grant or down payment assistance. These classes are designed to help you navigate the homebuying process, and can be a good idea to take whether they’re mandatory or not.


What are the requirements to qualify for a first-time home buyer loan?

Qualifications required for approval of a loan vary by the type of mortgage — and even by the lender — but here are some general guidelines:

Kentucky Conventional loans:

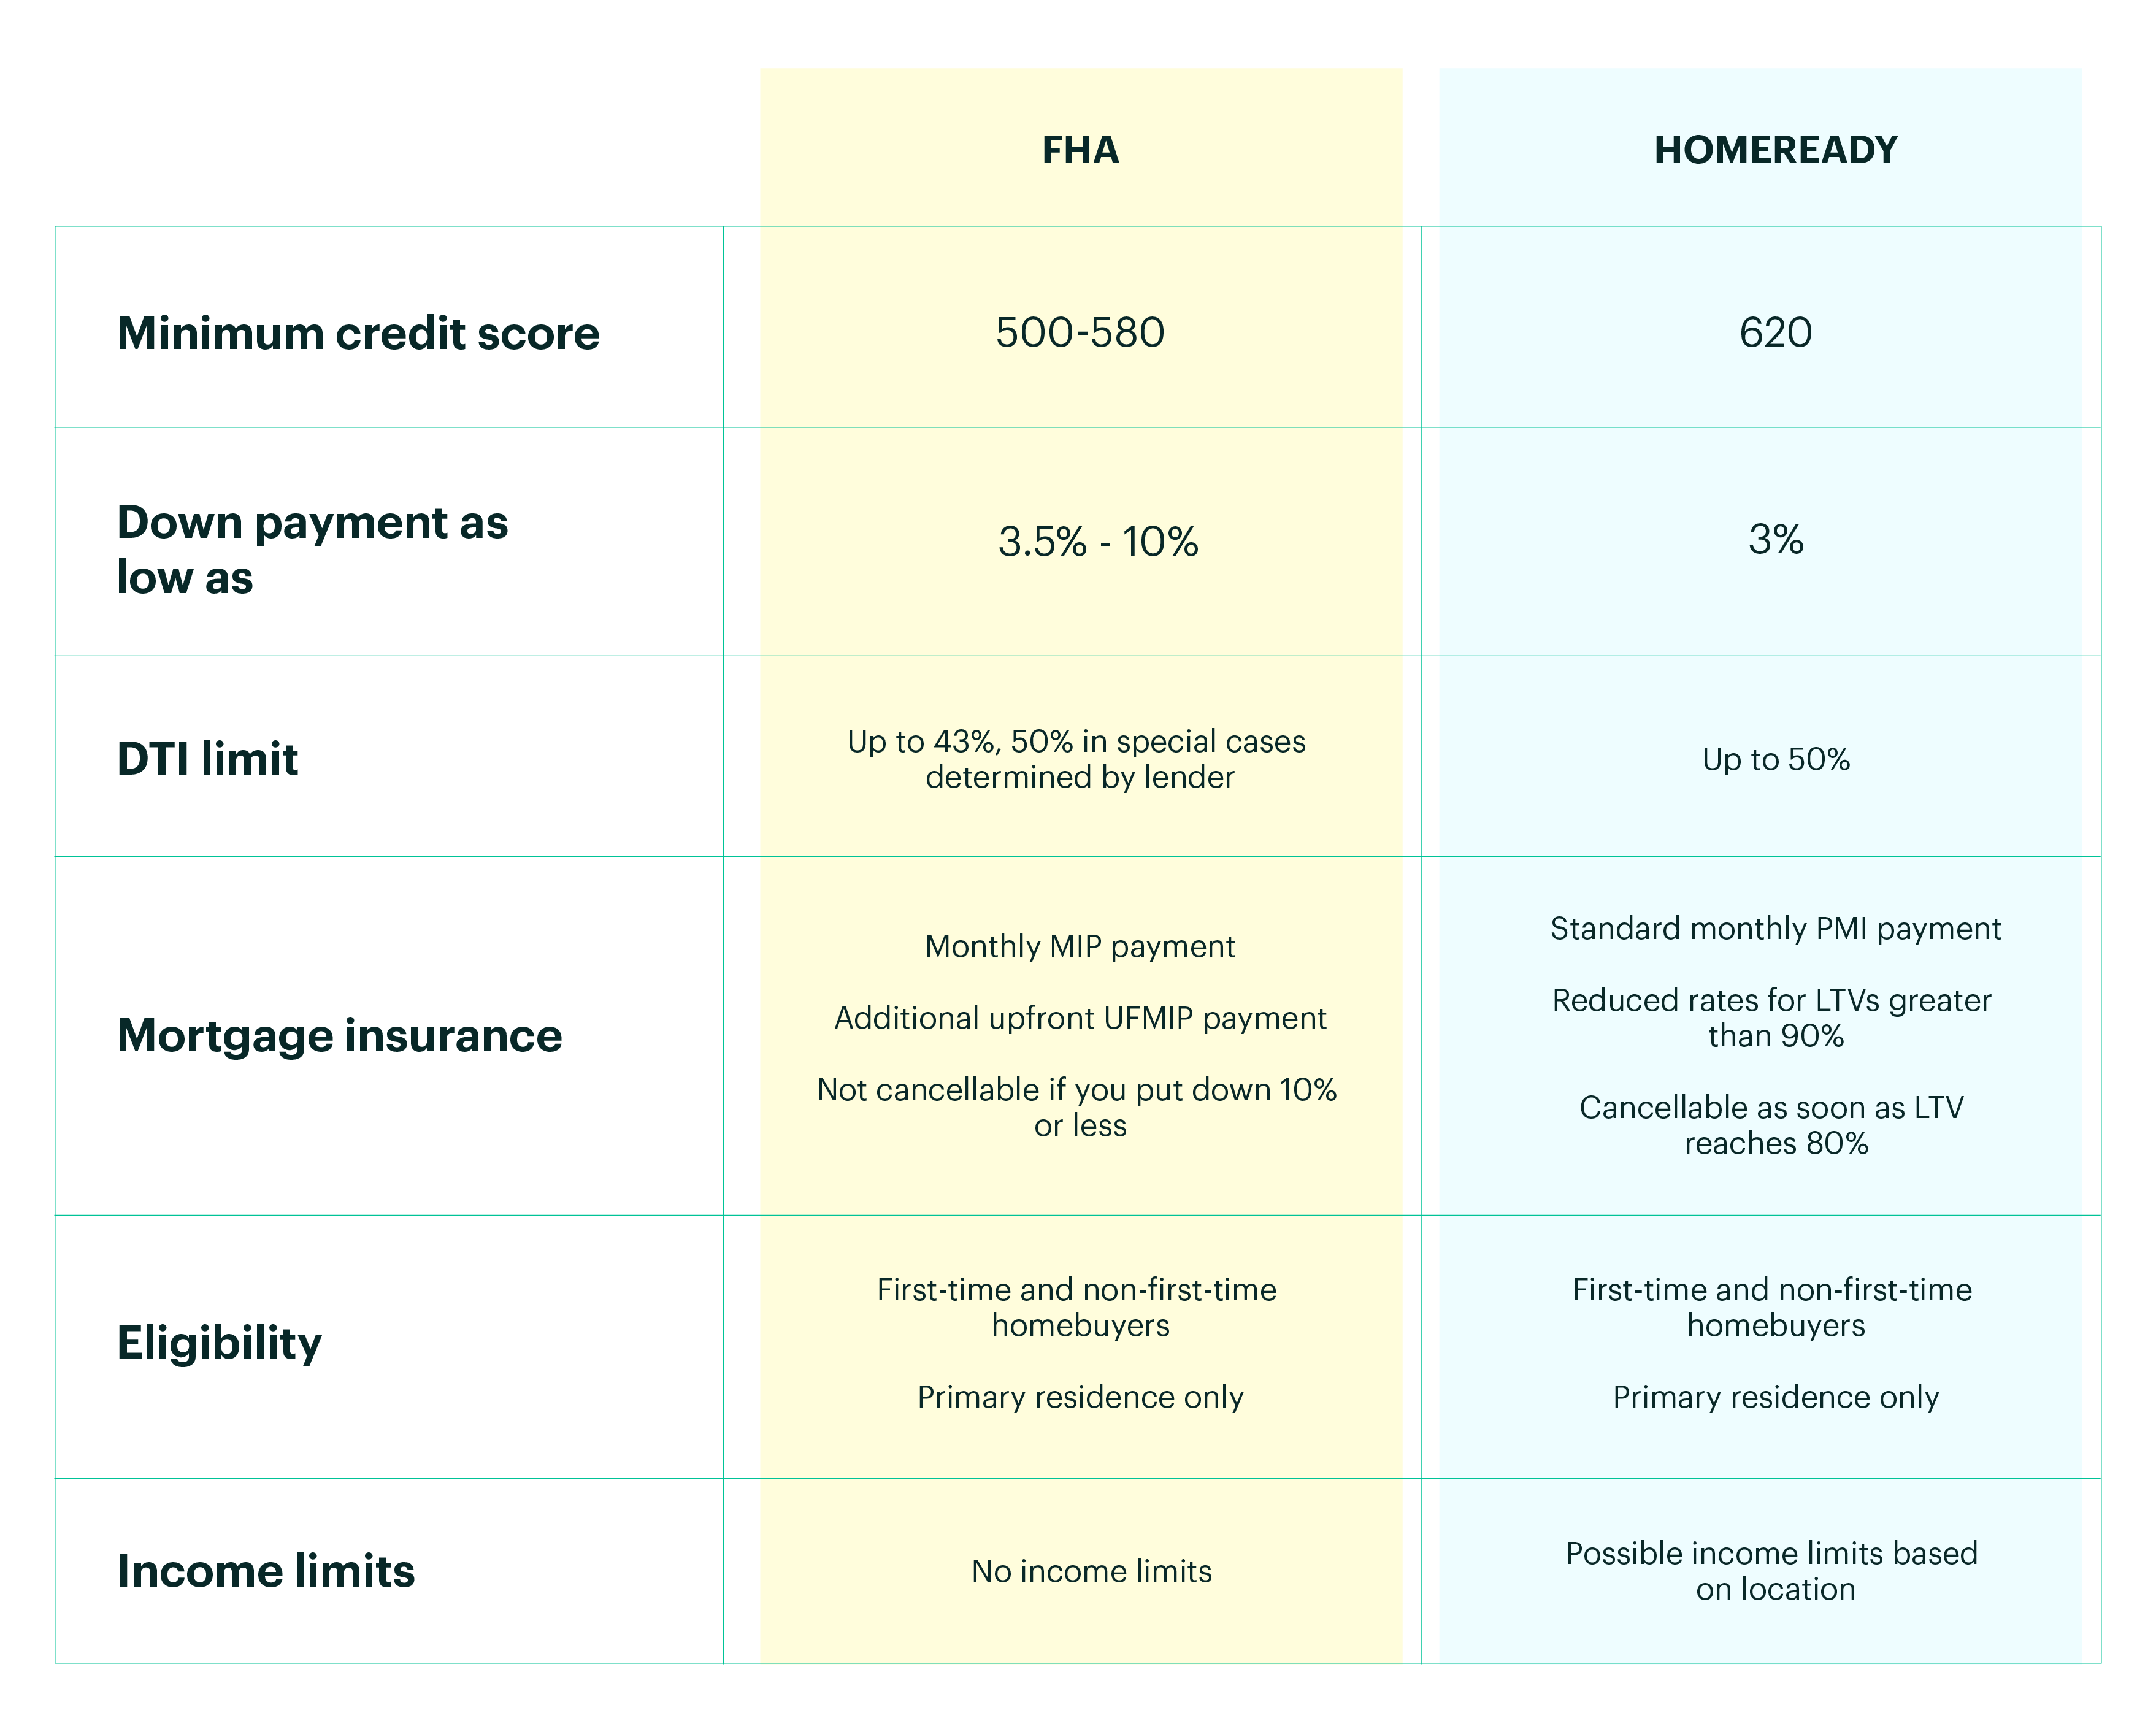
For a 3% down payment, you’ll need at least a 620 FICO and a debt-to-income ratio below 50%. The higher your credit score or the lower your debt, the better your chances are for approval.

Kentucky FHA loans:

If you want a down payment as low as 3.5%, you’ll need a FICO score of 580 or higher. With 10% down, your required credit score may go as low as 500.

Kentucky VA loans:

Down payments aren’t generally required for a loan backed by the Department of Veterans Affairs. And while VA-backed loans don’t have a minimum FICO score as a part of their official requirements, many lenders look for a score of 620 or better.

KentukcyUSDA loans:

Another no-down-payment option, USDA-backed loans are typically issued for rural or suburban properties. Income limits apply. A FICO score of 640 or better is generally required, though exceptions with documentation can allow a lower score.

Lenders can add additional conditions, called “overlays,” to loan approval. This is another good reason to shop for more than one lender.


Joel Lobb
Mortgage Loan Officer
Individual NMLS ID #57916
 
American Mortgage Solutions, Inc.
 

Text/call:      502-905-3708

fax:            502-327-9119
email:
          kentuckyloan@gmail.com
 

Unknown's avatarKentucky USDA Mortgage Lender for Rural Housing Loans

View original post 1,829 more words

How to qualify for a Kentucky FHA Home Loan ?

How to qualify for a Kentucky FHA Home Loan ?

Image result for fha loans ky


FHA stands for the Federal Housing Administration which is a government agency created to increase home-ownership across the United States all the way back in 1934. The agency itself doesn’t offer home loans but insures loan that are offered by private lenders (i.e. mortgage companies).

It’s important to understand the different types of loan programs available to you and what benefits and drawbacks there are to each type.

For example, if you’re looking to find a fixer upper this may not be the right loan program for you. But an FHA loan may be a better fit for you if you have little cash saved up for a down payment or if you don’t have a high credit score.

Kentucky FHA loan requirements:

  • At least 18 years old to apply
  • No age limit. just must be 18 years of age to apply.
  • Must occupy the home as a primary residence, no rental homes or investment property
  • An appraisal must be done by an FHA-approved appraiser.Typically FHA appraisal in Kentucky costs anywhere from low-end $325 to $525 with most FHA lenders in KY.
  • Home inspection is not required
  • Termite inspection not required
  • 2 years removed from Chapter 7 bankruptcy, and 1 year in Chapter 13 bankruptcy is possible to get a loan while in bankruptcy
  • Foreclosure or short sale on previous home mortgage requires 3 years removal from those dates.
  • Mortgage insurance (MIP) is required
  • Upfront Mortgage Insurance Premium is 1.75% and monthly mortgage insurance is .85% or .80% depending on loan term and loan to value.
  • Mortgage insurance is for life of loan.
  • No matter your credit scores, everyone pays the same mortgage insurance premiums.
  • Must have 2 years of employment history proving a reliable source of income
  • 500 FICO score requirement with at least 10% down payment
  • 580 FICO score requirement with at least 3.5% down payment
  • Gifts and down payment assistance programs are allowed to meet your down payment requirements. Cannot come from seller, but seller can contribute up to 6% of the sales price toward buyer’s closing costs and prepaids.
  • Student loan payments are factored into the debt-to-income ratio when applying. Typically if loans are deferred, or in an income=based repayment plan, the FHA underwriters will use 1% of the outstanding balance, which sometimes can make it difficult to qualify.
  • Your debt-to-income ratio must not be higher than 31% or total debt obligation cannot be higher than 43% of your current income. This is for a manual underwriter, meaning that if the AUS underwriting system by mortgage lenders will approve you for a higher debt to income ratio, that is fine.


Joel Lobb (NMLS#57916)
Senior  Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346

Text/call 502-905-3708kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

FHA vs Conventional Infograhic