
What is the minimum credit score I need to qualify for a Kentucky FHA, VA, USDA and KHC Conventional mortgage loan?

What is an FHA Loan and Is It Right for You?
Source: What is an FHA Loan and Is It Right for You?
What Is An FHA Loan And Is It Right For You?
Sponsored by:
The Federal Housing Administration insures what are called FHA loans. These mortgage loans provide opportunities for buyers with less-than-perfect credit or limited down payments to purchase homes, but they aren’t without potential pitfalls.
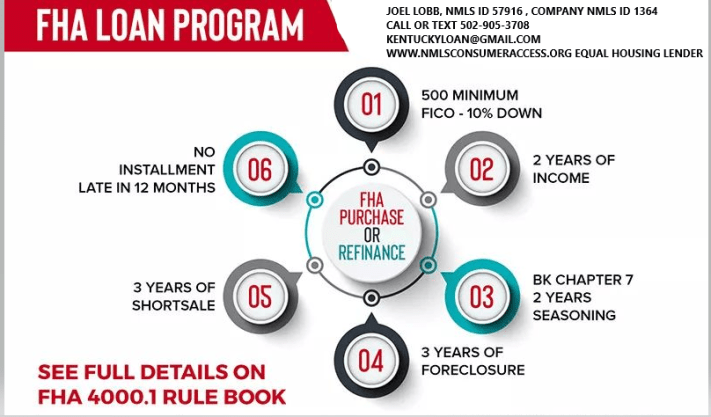
FHA loans are available to borrowers with a credit score of at least 580, and you have to make a minimum 3.5% down payment. They’re a popular option for first-time home buyers.
Lenders such as banks and credit unions issue the mortgages, which are insured by the FHA. That protects the lender if the borrower defaults, which is why the terms are more favorable than a traditional mortgage.
Around eight million single-family homes have loans insured by the FHA.
What Can an FHA Loan be Used For?
You can use an FHA loan to refinance single-family houses, to buy a single-family home, to buy some multifamily homes and condos and certain mobile and manufactured homes. There are particular types of FHA loans that can be used to renovate an existing property or for new construction.
How is an FHA Loan Different from a Conventional Mortgage Loan?
The biggest differentiator between an FHA loan and a conventional mortgage is that it’s easier to qualify for an FHA loan. You may get a loan with a lower credit score than you would otherwise, and your mortgage insurance payments may be lower too.
There are also fewer restrictions as far as using gifts from family or donations for your down payment.
If you have a FICO score of at least 580, you have to make a 3.5% down payment. With a FICO score between 500 and 579, you’re required to make a 10% down payment, and mortgage insurance is required. Your debt-to-income ratio needs to be less than 43% whereas with a conventional loan it’s usually 36%. You do need to have proof of income and steady employment, as you would need with a conventional loan.
Are There FHA Loan Limits?
There are limits on the mortgage amount you can get with an FHA-guaranteed loan. The limits vary based on your county, and in 2020 these ranged from $331,760 to $765,600. The limit amounts are updated by the FHA each year based on fluctuations in home prices.
The Benefits of the FHA Loan
The primary benefits of an FHA loan are that buyers who wouldn’t otherwise qualify may be able to own a home and for a lower down payment. Sometimes the FHA will help facilitate coverage of closing costs. If you have problems making payments on an FHA loan you may be eligible for a forbearance period if you qualify.
What Are the Downsides of an FHA Loan?
You will have to pay an upfront mortgage insurance premium with an FHA loan to protect the lender. The fee is due when you close and it’s 1.75% of your loan. You will also have to pay an annual mortgage insurance premium for the life of your loan. The amount can range between 0.45% and 1.05%.
When you buy a home with an FHA loan, it has to meet strict standards in terms of health and safety.
Also, while there are set standards from the FHA, approved lenders can create their own requirements.
Applying for an FHA Loan
You’ll have to first find an FHA-approved lender to get one of these home loans. You’ll need some documents, including proof of U.S. citizenship, legal permanent residency, or eligibility to work in America. You’ll need bank statements for at least the past 30 days, and you’ll probably need to show pay stubs.
Some of the information your lender may be able to obtain on your behalf, such as your credit reports, tax returns and employment records.
There are advantages to an FHA loan because it expands homeownership to more people than conventional loans. It’s just important that if you’re considering this loan you understand the costs and that you’re not taking on more than you’re financially prepared for because of the less stringent approval requirements.
Written by Ashley Sutphin for http://www.RealtyTimes.com Copyright © 2020 Realty Times All Rights Reserved.
Kentucky FHA Loan Requirements For 2020
Kentucky FHA Mortgage Loans Guidelines

FHA Announces COVID-19 Temporary Guidance for Kentucky FHA Mortgage Loans
Kentucky FHA Temporary Guideline Changes:
Rental Income & Self-Employment Income
FHA Announces COVID-19 Temporary Guidance for Kentucky FHA Mortgage Loans
Due to the ongoing effect of COVID-19, FHA has announced in ML 2020-03, updates to the following temporary guidelines below effective with case number assignments on or after 8/12/2020 -11/30/2020:
Rental Income for Kentucky FHA Mortgage Loans
- When qualifying utilizing rental income, for each property generating rental income the following is required:
- Reduce the effective income associated with the calculation of rental income by 25%, or
- Verify 6 months PITI reserves, or
- Verify the borrower has received the previous 2 months rental payments as evidenced by borrower’s bank statements showing the deposit. (This option is applicable only for borrowers with a history of rental income from the property).
Self Employment Income for Kentucky FHA Mortgage loans
- Self-employment income must be stable with a reasonable expectation that it will continue. Verification of the existence of the borrower’s business within 10 calendar days prior to the date of the Note to confirm that the Borrower’s business is open and operating. One (1) of the following to verify and confirm that the business is open and operating:
- Evidence of current work (executed contracts or signed invoices that indicate the business is operating on the day the lender verifies self-employment);
- Evidence of current business receipts within 10 days (Note Fairway Policy) of the note date (payment for services performed);
- Lender certification that the business is open and operating (lender confirmed through a phone call or other means) (Note Fairway Policy); or
- Business website demonstrating activity supporting current business operations (timely appointments for estimates or service can be scheduled).
Joel Lobb
Mortgage Loan Officer
Mortgage Loan Officer
Individual NMLS ID #57916
American Mortgage Solutions, Inc.
Text/call: 502-905-3708
fax: 502-327-9119
email: kentuckyloan@gmail.com
email: kentuckyloan@gmail.com


