Complete Guide to FHA Loan Requirements in Kentucky

FHA loans are a popular choice for many first-time homebuyers in Kentucky. This is due to their flexible qualifying criteria. If you’re considering an FHA loan in the Bluegrass State, understanding the key qualifying factors is crucial. Here’s a comprehensive guide to the criteria you need to know:

  1. Credit Score Requirements:
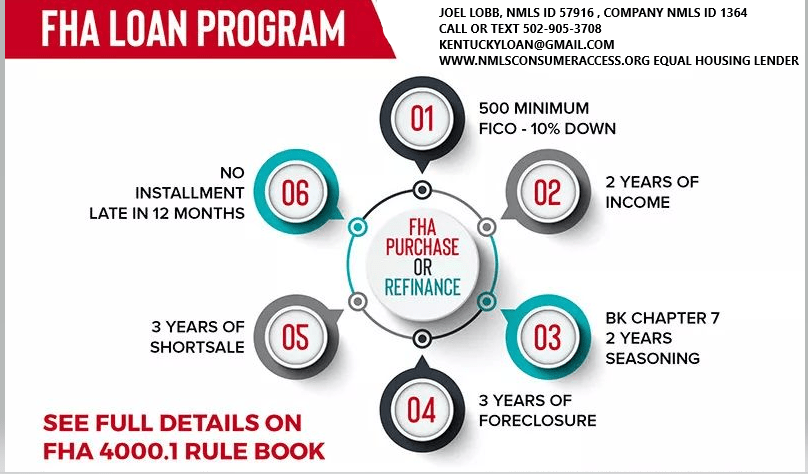
    • FHA loans are known for accommodating borrowers with lower credit scores. The minimum required credit score can vary. Typically, a credit score of 580 or higher is needed to qualify for the minimum down payment of 3.5%. Borrowers with credit scores between 500 and 579 might still qualify. They will need a higher down payment, usually around 10%.
  2. Down Payment:
    • The minimum down payment for an FHA loan in Kentucky is 3.5% of the home’s purchase price. This is advantageous for buyers who may not have substantial savings for a larger down payment, making homeownership more accessible.
  3. Work History:
    • Lenders typically look for a steady 2 year employment history when considering FHA loan applications. A consistent work history is beneficial. It is preferable to have worked with the same employer or within the same field. This helps demonstrate financial stability and the ability to repay the loan.
  4. Debt-to-Income Ratio (DTI):
    • The debt-to-income ratio is a crucial factor in mortgage approval. For FHA loans, the maximum allowable DTI ratio is typically around 40% to 45% of your gross monthly income. It can go higher up to 56% with good credit scores, a large down payment, or a shorter-term loan. Lenders may also consider higher ratios in certain cases if compensating factors are present.
  5. Bankruptcy and Foreclosure:
    • FHA loans have lenient guidelines regarding bankruptcy and foreclosure. Generally, borrowers with a past bankruptcy may qualify for an FHA loan after two years. This is possible if they have re-established good credit and demonstrated responsible financial behavior. For foreclosures, the waiting period is usually three years.
  6. Mortgage Term:
    • FHA loans offer various mortgage term options, including 15-year, 20 year, 25 year and 30-year fixed-rate loans. The choice of term depends on your financial goals and ability to manage monthly payments.
    • Occupancy: Primary residences with 1-4 units. Not for investment properties or second homes.
    • Mortgage Insurance on the loan for life of loan. Larger down payments and shorter terms will reduce the upfront mi and monthly mi premiums
    • can be used for refinances, not only for purchases.
    • No income limits nor property restrictions on where home is located
    • Can close within 30 days typically with good appraisal and title work

FHA Loan Requirements in Kentucky for Credit scores, Down payment, Debt Ratio and work history below

RequirementDetails
Credit Score– 580+: Eligible for a 3.5% down payment.
– 500-579: Requires a 10% down payment.
Down PaymentMinimum of 3.5% for qualified buyers; 10% for lower credit scores below 580 to 500 score range
Debt-to-Income Ratio (DTI)– Ideal: 45% or lower on front end ratio or housing ratio.
– Acceptable: Up to 57% with compensating factors. There are two ratios. Front end and back end with front end being maxed at 45% and the backed end ratio being 56.99% with an AUS approval. If manually underwritten, see guidelines here
Employment HistoryMust provide at least **2 years of consistent employment—College transcripts can supplement with a less than 2 year work history

Key Benefits of FHA Loans in Kentucky

  1. Low Credit Score Requirements
    • FHA loans accept borrowers with credit scores as low as 500. However, a score of 580+ qualifies you for the lowest down payment option.
  2. Low Down Payment Options
    • You can purchase a home with as little as 3.5% down if you meet credit requirements, making FHA loans more accessible than conventional loans.
  3. Competitive Interest Rates
    • FHA loans typically offer rates comparable to conventional mortgages. They may even offer lower rates. This could save you money over the life of the loan.
  4. Flexible Loan Uses
    • With an FHA 203(k) loan, you can bundle home purchase and renovation costs into a single mortgage.
  5. Assumable Loans
    • FHA loans can be transferred to a new buyer. This feature is especially valuable if you sell your home when interest rates are higher.

Understanding these qualifying criteria can help you navigate the FHA loan application process in Kentucky more effectively. Working with an experienced mortgage professional can provide valuable guidance. They offer assistance tailored to your specific financial situation and homeownership goals.

Joel Lobb  Mortgage Loan Officer

Any questions, please don’t hesitate to reach out via, text, email,  or call.  Advice is always free. 
 
One of Kentucky’s highest rated mortgage loan officers for FHA, VA, USDA, Kentucky Housing KHC and conventional mortgage loans.  
1 – 📅 Email – kentuckyloan@gmail.com 
2.  📞 Call/Text – 502-905-3708
 

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans

🌐 Website: www.mylouisvillekentuckymortgage.com
🏢 Address: 911 Barret Ave., Louisville, KY 40204


Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.

Kentucky Local Home Loan Lender Services

✅ First-Time Home Buyers Welcome
✅ FHA, Rural Housing (USDA), VA, and Kentucky Housing Corporation (KHC) Loans
✅ Conventional Loan Options Available
✅ Fast Local Decision-Making
✅ Experienced Guidance Through the Home Buying Process


NMLS 57916  | Company NMLS #173846
The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people.
(www.nmlsconsumeraccess.org).
Kentucky First Time Homebuyers FHA, VA, USDA & Rural Housing, KHC and Fannie Mae mortgage loans
 

Kentucky FHA Manual Underwriting Explained

KENTUCKY FHA MORTGAGE MANUAL UNDERWRITING GUIDELINES FOR VA RESIDUAL INCOME

Kentucky FHA Mortgage  Manual Undewriting Guidelines for FHA Mortgage Refer Eligible or Manual Downgrades

Continue reading “Kentucky FHA Manual Underwriting Explained” →

FHA Guidelines for Well Water in Kentucky

Image result for fha minimum property standards

Below are Kentucky  FHA guidelines for a property that has well water and septic tanks for waste disposal .  The Kentucky FHA appraiser should be able to address the distance between the well and septic for distance requirements, and comment if public sewers are available.

Well water test will be required as a closing condition. FHA mortgages loans in Kentucky  require a septic inspection unless the appraiser mentions it is necessary.

(O) Water Supply Systems in Kentucky 

(1) Public Water Supply System The Mortgagee must confirm that a connection is made to a public or Community Water System whenever feasible and available at a reasonable cost. If connection costs to the public or community system are not reasonable, the existing onsite systems are acceptable, provided they are functioning properly and meet the requirements of the local health department.

(2) Individual Water Supply Systems (Wells) When an Individual Water Supply System is present, the Mortgagee must ensure that the water quality meets the requirements of the health authority with jurisdiction. If there are no local (or state) water quality standards, then water quality must meet the standards set by the EPA, as presented in the National Primary Drinking Water regulations in 40 CFR §§ 141 and 142. Soil poisoning is an unacceptable method for treating termites unless the Mortgagee obtains satisfactory assurance that the treatment will not endanger the quality of the water supply. Requirements for the location of wells for FHA-insured Properties are located in 24 CFR § 200.926d (f) (3). The following tables provide the minimum distance required between wells and sources of pollution for Existing Construction:

Individual Water Supply System for Minimum Property
Requirements for Existing Construction*
1 Property line/10 feet
2 Septic tank/50 feet
3 Drain field/100 feet
4 Septic tank drain field reduced to 75 feet if allowed by local authority
5 If the subject Property line is adjacent to residential Property then local well distance requirements prevail. If the subject Property is adjacent to non-residential Property or roadway, there needs to be a separation distance of at least 10 feet from the property line.
* distance requirements of local authority prevail if greater than stated above

The following provides the minimum requirements for water wells:

Water Wells Minimum Property Standards for New Construction
24 CFR § 200.926d(f)(1)
1 Lead-free piping
2 If no local chemical and bacteriological water standards, state standards apply
3 Connection of public water whenever feasible
4 Wells must deliver water flow of five gallons per minute over at least a four-hour period
Water Wells Minimum Property Requirements for Existing Construction
1 Existing wells must deliver water flow of three to five gallons per minute
2 No exposure to environmental contamination
3 Continuing supply of safe and potable water
4 Domestic hot water
5 Water quality must meet requirements of local jurisdiction or the EPA if no local standard

Shared WellsThe Mortgagee must confirm that a Shared Well:

  • serves existing Properties that cannot feasibly be connected to an acceptable public or Community Water supply System;
  • is capable of providing a continuous supply of water to involved Dwelling Units so that each existing Property simultaneously will be assured of at least three gallons per minute (five gallons per minute for Proposed Construction) over a continuous four-hour period. (The well itself may have a lesser yield if pressurized storage is provided in an amount that will make 720 gallons of water available to each connected existing dwelling during a continuous four-hour period or 1,200 gallons of water available to each proposed dwelling during a continuous four-hour period. The shared well system yield must be demonstrated by a certified pumping test or other means acceptable to all agreeing parties.);
  • provides safe and potable water. An inspection is required under the same circumstances as an individual well. This may be evidenced by a letter from the health authority having jurisdiction or, in the absence of local health department standards, by a certified water quality analysis demonstrating that the well water complies with the EPA’s National Interim Primary Drinking Water Regulations;
  • has a valve on each dwelling service line as it leaves the well so that water may be shut off to each served dwelling without interrupting service to the other Properties; and
  • serves no more than four living units or Properties.

For both proposed and existing Properties, the Mortgagee must ensure that the shared well agreement complies with the guidance provided in the following table.

Item Provisions that must be reflected in any acceptable shared well agreement include the following:
1 Require that the agreement is binding upon signatory parties and their successors in title, recorded in local deed records when executed and recorded, and reflects joiner by any Mortgagee holding a Mortgage on any Property connected to the Shared Well.
2 Permit well water sampling and testing by the local authority at the request of any party at any time.
3 Require that corrective measures be implemented if testing reveals a significant water quality deficiency, but only with the consent of a majority of all parties.
4 Ensure continuity of water service to “supplied” parties if the “supplying” party has no further need for the shared well system. (“Supplied” parties normally should assume all costs for their continuing water supply.)
5 Prohibit well water usage by any party for other than bona fide domestic purposes.
6 Prohibit connection of any additional living unit to the shared well system without:·        the consent of all parties;

·        the appropriate amendment of the agreement; and

·        compliance with item 3.

7 Prohibit any party from locating or relocating any element of an individual sewage disposal system within 75 feet (100 feet for Proposed Construction) of the Shared Well.
8 Establish Easements for all elements of the system, ensuring access and necessary working space for system operation, maintenance, improvement, inspection and testing.
9 Specify that no party may install landscaping or improvements that will impair use of the Easements.
10 Specify that any removal and replacement of preexisting site improvements, necessary for system operation, maintenance, replacement, improvement, inspection or testing, will be at the cost of their owner, except for costs to remove and replace common boundary fencing or walls, which must be shared equally between or among parties.
11 Establish the right of any party to act to correct an emergency in the absence of the other parties onsite. An emergency must be defined as failure of any shared portion of the system to deliver water upon demand.
12 Permit an agreement amendment to ensure equitable readjustment of shared costs when there may be significant changes in well pump energy rates or the occupancy or use of an involved Property.
13 Require the consent of a majority of all parties upon cost sharing, except in emergencies, before actions are taken for system maintenance, replacement or improvement.
14 Require that any necessary replacement or improvement of a system element(s) will at least restore original system performance.
15 Specify required cost sharing for:·        the energy supply for the well pump;

·        system maintenance, including repairs, testing, inspection and disinfection;

·        system component replacement due to wear, obsolescence, incrustation or corrosion; and

·        system improvement to increase the service life of a material or component to restore well yield or to provide necessary system protection.

16 Specify that no party is responsible for unilaterally incurred shared well debts of another party, except for correction of emergency situations. Emergency correction costs must be equally shared.
17 Require that each party be responsible for:·        prompt repair of any detected leak in this water service line or plumbing system;

·        repair costs to correct system damage caused by a resident or guest at their Property; and

·        necessary repair or replacement of the service line connecting the system to the dwelling.

18 Require equal sharing of repair costs for system damage caused by persons other than a resident or guest at a Property sharing the well.
19 Ensure equal sharing of costs for abandoning all or part of the shared system so that contamination of ground water or other hazards will be avoided.
20 Ensure prompt collection from all parties and prompt payment of system operation, maintenance, replacement or improvement costs.
21 Specify that the recorded agreement may not be amended during the term of a federally-insured or -guaranteed Mortgage on any Property served, except as provided in items 5 and 11 above.
22 Provide for binding arbitration of any dispute or impasse between parties with regard to the system or terms of agreement. Binding arbitration must be through the American Arbitration Association or a similar body and may be initiated at any time by any party to the agreement. Parties to the agreement must equally share arbitration costs.
http://www.emailmeform.com/builder/form/0bfJs9b6bK8TGoc6mQk9hIu
 
Joel Lobb
Mortgage Broker – FHA, VA, USDA, KHC, Fannie Mae
EVO Mortgage • Helping Kentucky Homebuyers Since 2001
📞 Call/Text: 502-905-3708
📧 Email: kentuckyloan@gmail.com
🌐 Website: www.mylouisvillekentuckymortgage.com
🏠 Address: 911 Barret Ave, Louisville, KY 40204
NMLS #57916 | Company NMLS #1738461
Free Info & Homebuyer Advice →
Kentucky Mortgage Loan Expert
FHA | VA | USDA | KHC Down Payment Assistance | Fannie Mae
Equal Housing Lender. This is not a commitment to lend. All loans are subject to credit approval and program requirements.
http://www.nmlsconsumeraccess.org/
Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916 http://www.nmlsconsumeraccess.org/
 
— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.
 

2026 FHA Loan Options for Kentucky Homebuyers

Kentucky FHA Loan Requirements – Updated for 2026

Kentucky FHA loan guidelines are established by the U.S. Department of Housing and Urban Development (HUD). FHA loans remain one of the most flexible mortgage options available to Kentucky homebuyers, particularly first-time buyers, borrowers rebuilding credit, and households using down payment assistance.

Employment and Income Requirements

Borrowers must demonstrate a stable employment history covering the most recent two years. This does not require the same employer, but the work history must show consistency in the same industry or line of work.

Recent college graduates may satisfy the two-year work history requirement by providing college transcripts, provided the current employment aligns logically with the education received.

Self-employed borrowers must document a minimum two-year history of self-employment and provide the most recent two years of federal tax returns filed with the IRS. FHA underwriting uses a two-year average of qualifying income, adjusted for business stability and trends.

All income must be verifiable through acceptable documentation such as pay stubs, W-2s, or tax returns. Cash income, undocumented deposits, or bank-statement-only income is not permitted for FHA qualifying purposes.

Down Payment Requirements

FHA loans require a minimum down payment of 3.5 percent for borrowers with credit scores of 580 or higher.

Borrowers with credit scores between 500 and 579 are limited to a maximum loan-to-value of 90 percent, requiring a minimum 10 percent down payment. In practice, most lenders apply overlays requiring higher credit scores, typically between 580 and 620, even though HUD technically allows lower scores.

Down payment funds must come from an approved source. Acceptable sources include personal savings, retirement account loans or withdrawals, and properly documented gift funds. Large or undocumented cash deposits are not allowed and remain one of the most common reasons for FHA loan delays or denials in underwriting.

Occupancy and Property Use

FHA loans are for primary residences only. The borrower must occupy the property as their primary home and move in within 60 days of closing. FHA financing may not be used for rental properties or investment homes.

Appraisal and Property Standards

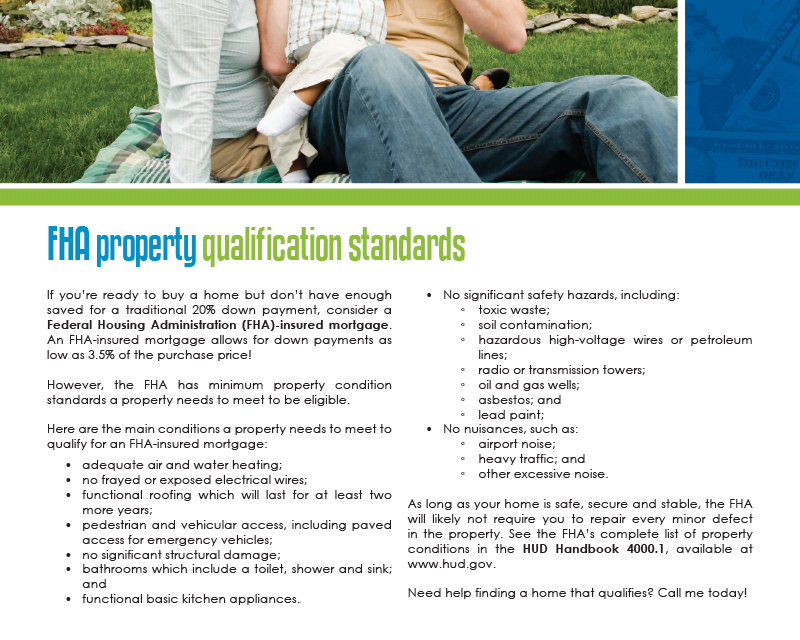
The property must be appraised by a Kentucky-licensed, FHA-approved appraiser. The home must meet HUD’s minimum property standards, meaning it must be safe, sound, and secure.

Common appraisal concerns include peeling paint, exposed wiring, missing handrails, roof condition, and health or safety hazards. Most FHA appraisal issues are correctable prior to closing.

Debt-to-Income Ratio Guidelines

FHA evaluates two debt ratios:

The housing ratio (front-end), which includes principal, interest, property taxes, homeowners insurance, mortgage insurance, and HOA dues, is typically capped at 31 percent of gross monthly income.

The total debt ratio (back-end), which includes the housing payment plus all other monthly obligations reported on credit, is typically capped at 43 percent.

However, borrowers receiving an “Approve/Eligible” finding through FHA’s automated underwriting system may qualify with higher ratios, depending on credit scores, cash reserves, and other compensating factors.

Credit Score and Credit History Requirements

The minimum FHA credit score for maximum financing remains 580 in 2026. This does not guarantee approval, as lenders apply additional underwriting standards and overlays.

Borrowers must demonstrate acceptable recent payment history. FHA places significant weight on the most recent 12 months of credit performance.

Bankruptcy and Foreclosure Guidelines

Chapter 7 bankruptcy requires a minimum waiting period of two years from discharge, with re-established good credit and on-time payments afterward.

Chapter 13 bankruptcy may be eligible after at least 12 months of on-time plan payments, with trustee approval, and the borrower must qualify including the Chapter 13 payment.

Foreclosure generally requires a three-year waiting period from the date of foreclosure completion. Exceptions may be considered only for documented extenuating circumstances beyond the borrower’s control. Job relocation alone does not qualify as an extenuating circumstance.

Federal Debt and CAIVRS Requirements

Borrowers may not have delinquent federal debt, defaulted federal student loans, unpaid federal judgments, or unresolved FHA claims.

Lenders are required to check the CAIVRS (Credit Alert Interactive Voice Response System) database for all federally backed loans, including FHA, VA, USDA, and SBA loans. Title 31 of the U.S. Code prohibits delinquent federal debtors from receiving federal loan insurance or guarantees.

If a CAIVRS alert appears, the debt must be resolved or paid in full before closing.

FHA Gift Fund Rules for Down Payments

FHA permits gift funds for down payments and closing costs, provided there is no expectation of repayment.

Acceptable gift sources include relatives, employers, labor unions, close friends with a documented relationship, charitable organizations, and government or public entities.

Unacceptable gift sources include the seller, real estate agents, brokers, builders, or any party with a financial interest in the transaction.

A proper gift letter is required, stating that repayment is not expected. The donor must provide identifying information and documentation showing the transfer of funds from their account to the borrower.

Government and Employer Assistance Programs

Borrowers without access to family gift funds may qualify for state, local, or employer-assisted housing programs that provide down payment or closing cost assistance. In Kentucky, FHA loans can often be paired with Kentucky Housing Corporation (KHC) down payment assistance programs, subject to income limits and program availability.

How FHA Loans Are Used in Kentucky

FHA does not directly lend money. Instead, it insures loans made by FHA-approved lenders. These loans are designed for borrowers with limited down payment funds, past credit challenges, or non-traditional credit profiles.

Many Kentucky borrowers who do not qualify for conventional financing are still able to achieve homeownership through FHA-insured loans at competitive interest rates.

Pros and Cons of FHA Loans

Advantages include low down payment requirements, flexible credit standards, and the ability to combine FHA loans with down payment assistance programs.

Disadvantages include mandatory mortgage insurance. FHA charges an upfront mortgage insurance premium of 1.75 percent of the loan amount, which can be financed, and an annual mortgage insurance premium that ranges from approximately 0.45 percent to 1.05 percent depending on loan term, loan-to-value, and origination date. This annual premium is paid monthly and, in most cases, remains for the life of the loan unless refinanced.

Final Thoughts for Kentucky Homebuyers in 2026

FHA loans continue to be a practical, reliable option for Kentucky homebuyers who need flexibility without sacrificing long-term stability. While FHA guidelines are forgiving compared to conventional loans, preparation matters. Clean documentation, stable income, responsible credit behavior, and proper sourcing of funds are essential to a smooth approval.

Working with an experienced Kentucky FHA lender can help you navigate overlays, improve credit positioning, and pair FHA financing with available assistance programs.


Joel Lobb
NMLS #57916
Text or Call 502-905-3708
kentuckyloan@gmail.com
www.mylouisvillekentuckymortgage.com

Company NMLS #1738461
Equal Housing Lender

Information is provided for educational purposes only and does not guarantee loan approval. All loans are subject to underwriting guidelines, program availability, and lender approval.

How to Qualify for an FHA Mortgage Loan in Kentucky: A Guide for First-Time Homebuyers

There are many ways to get the mortgage to buy your first home. The FHA is one option. If you are a first-time homebuyer in Kentucky, an FHA loan could be the perfect option for you. There are many flexible requirements, low down payments, and financial assistance options available. These are just a few of the many things that can help make homeownership more accessible.


What is an FHA Loan?

An FHA loan is a government-backed mortgage insured by the Federal Housing Administration (FHA). It’s designed for low-to-moderate-income borrowers, offering relaxed qualification standards compared to conventional loans. Here are the main advantages:

  • Low down payment: As little as 3.5% of the purchase price.
  • Lower credit score requirements: Minimum score of 500 with 10% down or 580 with 3.5% down.
  • Seller-paid closing costs: Sellers can contribute up to 6% of the purchase price.
  • Flexible qualifying criteria: Higher debt-to-income (DTI) ratios and options for non-occupant co-signers.

How to Qualify for a Kentucky FHA Loan

1. Credit Score Requirements

  • 580 or higher: You’ll need a minimum credit score of 580 to qualify for the 3.5% down payment option.
  • 500-579: You can still qualify with a 10% down payment, but many lenders prefer a score of 580 or higher.
  • Bankruptcy or Foreclosure:
    • Chapter 7 bankruptcy: Must be 2 years removed, with good credit since.
    • Chapter 13 bankruptcy: Can qualify after 1 year of on-time payments with trustee approval.
    • Foreclosure: Must be 3 years removed, unless there are extenuating circumstances.

2. Income and Debt-to-Income Ratio

  • DTI ratio: Typically, up to 45%% of your income can go toward your mortgage payment, and up to 56.9% can go toward all debts, depending on your credit and financial history.
  • Work history: You must have a stable employment history of at least 2 years in the same field. Recent graduates can use college transcripts as a substitute.

3. Down Payment and Gift Options

  • 3.5% down payment: This can be gifted by a family member, employer, or nonprofit organization, drawn off a retirement account like a 401k or money saved up.
  • Cash deposits: Cash cannot be used as proof of funds for your down payment—only traceable sources are allowed.

4. Property Requirements

  • Must be your primary residence. FHA loans are not for investment properties or second homes.
  • Eligible property types: Single-family homes, townhomes, condos (must be approved condo development on HUD approved list), duplexes, and some manufactured homes (if affixed to a permanent foundation).
  • Appraisal: The property must be appraised by an FHA-approved appraiser to meet HUD standards.

5. Mortgage Insurance Premium (MIP)

  • Upfront MIP: 1.75% of the loan amount, which can be rolled into the loan.
  • Annual MIP: 0.45%-1.05% of the loan amount, depending on the down payment and loan term.

Kentucky FHA Loan Limits for 2025

In all Kentucky counties, the FHA loan limit is $524,225 for a single-family home up to $1,008,300 for a four-unit property


Why Choose an FHA Loan as a Kentucky First-Time Buyer?

Pros

  • Lower credit thresholds: You can qualify with a credit score as low as 500.
  • Smaller down payments: With as little as 3.5% down with a 580 credit score
  • Seller-paid costs: The seller can pay a significant portion of your closing costs.
  • Higher debt to income ratios
  • Lenient on past bankruptcies and foreclosures.

Cons

  • Mortgage insurance: You’ll pay MIP for the life of the loan if your down payment is less than 10%.
  • Property requirements: Homes must meet specific standards, which may limit your options.
  • a lot of sellers will not accept an FHA mortgage as a offer due to property may need work to meet FHA HUD minimum standards
  • Purchase price limits and only can be used for primary residence

FHA Loans vs. Conventional Loans

Feature FHA Loan Conventional Loan
Credit Score 500+ 620+
Down Payment 3.5% (580+ credit score) 3%-20%
Mortgage Insurance Required for life of loan Can be removed at 20% equity
Debt-to-Income Ratio Up to 55% Up to 45%
Property Standards Strict requirements More flexibility

Other Kentucky First-Time Homebuyer Programs

1. Kentucky Housing Corporation (KHC)

  • Down payment assistance up to $10,000.
  • Tax credit programs for first-time buyers.

2. USDA Loans

  • Zero-down-payment option for eligible rural areas.
  • Minimum credit score of 620-640 preferred.

3. VA Loans

  • No down payment or private mortgage insurance required for eligible veterans. No minimum credit score, higher debt to income ratios allowed and no monthly mortgage insurance and low 30 year fixed rates

Need Help Getting Approved for an FHA Loan in Kentucky?

As an experienced mortgage loan officer specializing in FHA loans for Kentucky first-time homebuyers, I’m here to guide you every step of the way.

Contact Me Today:

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans

Website: www.mylouisvillekentuckymortgage.com
Address: 911 Barret Ave., Louisville, KY 40204


Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

Equal Housing Lender

www.nmlsconsumeraccess.org

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.