CREDIT SCORE REQUIREMENTS FOR KENTUCKY FHA FINANCING

CREDIT REQUIREMENTS FOR KENTUCKY FHA FINANCING

What credit score do I need to qualify for a Kentucky FHA loan is one of the most common questions I hear from Kentucky homebuyers?

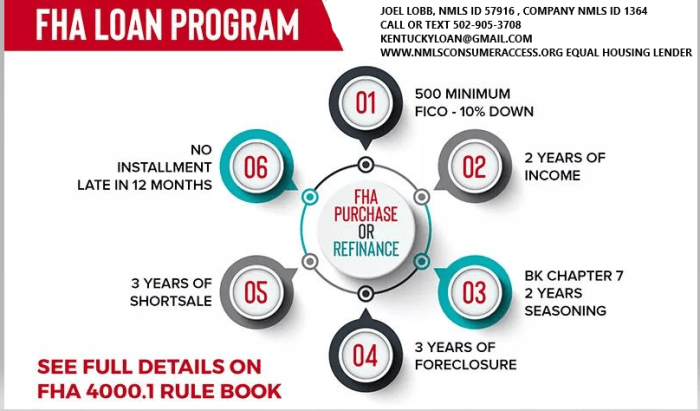
The short answer is you must have a minimum credit score of 500 to be eligible for an FHA loan in Kentucky.  Anything lower than 500 disqualifies you from consideration for an FHA loan.

There are two sets of credit score requirements for a Kentucky FHA Loan

One important thing to understand is that the Federal Housing Administration (FHA) does not lend money directly to home buyers. You will fill out an application with a regular lender just as you would if you were applying for any other type of mortgage. What the FHA does is ensure your loan to help protect the lender in case you default.

You will be required not only to meet the FHA guidelines to qualify for a loan but also meet any additional qualifications required by the lender. This means there are two sets of requirements you have to meet with your credit score.

1. The first set of requirements comes from the Department of Housing and Urban Development (HUD). HUD oversees the FHA and determines what a borrower’s minimum eligibility requirements will be to obtain an FHA loan.

2. The second set of requirements comes from the mortgage lender. The mortgage lender has the right to add its requirements to those mandated by HUD.

What HUD requires of borrowers to be eligible for an FHA loan

The HUD Handbook 4000.1 includes the official guidelines when it comes to the FHA mortgage insurance program.

It states that in 2020 the Kentucky FHA borrowers with credit scores of 580 or higher are eligible for a 96.5% loan with 3.5% down.

Borrowers with credit scores from 500 to 579 are eligible for a 90% loan with 10% down.

Individuals with credit scores below 500 are not eligible for the FHA program.

What lenders may require of borrowers to be eligible for an Kentucky FHA loan

Lenders have the right to add requirements over and above the minimum requirements of HUD. These additional requirements are called overlays. Your lender may or may not require them.

This is not something that should come as a surprise to you, however. Requiring a credit score of 580 to 620 is not unusual. In addition to your credit score, you must have a manageable debt level that lenders are comfortable with and enough income to repay your loan.

What credit score do I need to qualify for FHA loan?

Each month Ellie Mae, the software company processing more than ⅓ of America’s mortgage loans, publishes an insight report for mortgage trends and standards. One of the things they track is average credit scores. The following is their report for November 2019 which shows what percentage of successful borrowers fall into what credit score ranges.

500 – 549    2.14%
550 – 599    5.20%
600 – 649    23.01%
650 – 699    34.74%
700 – 749    21.88%
750 – 799    10.87%
800+     1.89%

These percentages show that the majority of borrowers who successfully qualify for FHA loans fall into the 600 to 799 range. While it is true that some successfully qualify in the low range of 500 to 599, you have a much better chance of being approved for a loan with good terms and a low down payment if you fall into the higher range.


For your free credit report and analysis call us today at 502-905-3708 or email us at kentuckyloan@gmail.com
Joel Lobb (NMLS#57916)
Senior  Loan Officer
 
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708
kentuckyloan@gmail.com


If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.


Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/


Lending 101: FHA Loans In Kentucky

Lending 101: FHA Loans In Kentucky

Kentucky FHA loans are great loan program that is not just for first-time buyers!
Here are some of our favorite features of Kentucky FHA loans:

  1. Low down payment – FHA requires 3.5 % down. For qualified buyers, this money may be able to be gifted from a family member.
  2. No income limits – There are no income limits placed on the borrower or the household.
  3. Credit scores – Interest rates and underwriting requirements are less credit score sensitive than other loan programs. In some scenarios, we are able to lend to buyers with scores in the mid-500s. *Note: Credit scores under 580 will require a 10% down payment.
  4. Manufactured homes – No problem with FHA! Manufactured homes must be on a permanent foundation and have been built after June 1976.
  5. Rehab loans – Utilizing the FHA 203K program, we can do purchase and refinance loans that roll the cost of rehabs or repairs into the loan amount.
  6. No geographic restrictions – FHA loans can be done anywhere,
  7. Generous Debt-to-Income Ratios – For most buyers, FHA allows for a higher debt load than other programs. FHA may be the only program for some borrowers with high credit card and/or student loan debt.
  8. Non-Occupant Co-Borrowers – FHA is one of the few programs that allow non-occupant co-borrowers. While a non-occupant co-borrower cannot help in scenarios where a buyer has a low score and cannot qualify on their own, it is a great solution for buyers who have low income or income that can’t be documented.

Want to learn more about FHA loans? Contact any member of our team today, reply to this email, or give us a call at 502-905-3708 and ask to speak to a mortgage loan originator.

What are the requirements to  qualify for a Kentucky FHA Mortgage?

What are the requirements to  qualify for a Kentucky FHA Mortgage in 2020?

Kentucky  FHA loan is a mortgage that is insured by the Government agency under Housing and Urban Development that is called FHA or short for Federal Housing Administration. The loan was established for Kentucky Home buyers will very little or no money down home loans with more  lenient credit score and  income requirements  and tends to be more forgiving about credit history with regard to bankruptcy and foreclosures, higher debt to income ratios and job history with limited work history for home buyers will only 2 years work history or less.

Kentucky FHA Credit Score Requirements and Down Payment Requirements

The Kentucky FHA  home loan  program may accept credit scores as low as 580 and require at least a 3.5 percent down payment of the sales price on a purchase. If you have a credit score below 580, then  a 10 percent down payment or more may be acceptable some FHA lenders in Kentucky , providing you meet all program guidelines in regards to debt to income ratios, assets, and income requirements .  The loan cannot be used for rental properties and does allow for co-signers if they are related.

Remember, these guidelines are set forth by FHA and all lenders do not have to offer these guidelines, to whereas they may a higher credit score or more money down or income restrictions on how much you can qualify for.

Kentucky FHA Mortgage Loans and Bankruptcy or Foreclosure

In case you had a  blemish on your credit report with a bankruptcy, short sale or foreclosure, follow these guidelines.

Kentucky FHA loans requires a passage of two years since the discharge date of a chapter 7 bankruptcy. A chapter 13 bankruptcy may be acceptable after at least 12 months of an on time pay-back period and the borrower has received permission from bankruptcy court to enter the mortgage transaction, and you qualify with the new house payment along with other debts on the credit report.

Three years must pass if you went through a short sale or foreclosure. The date starts when the home was sold, not when you entered the transaction toward foreclosure or short sale period. Sometimes the house will not sell to 1-2 years later after the foreclosure and this is when the passage date starts. Keep this in mind on your next FHA loan pre-approval if you have had a bankruptcy or foreclosure in the past.

Kentucky FHA Loans and Mortgage Insurance

FHA loans have two forms of mortgage insurance which protects the lender for any losses suffered if the borrower defaults on the payment. ne is called upfront mortgage insurance premium (UFMIP) which has a rate of 1.75% of the loan amount. The fee can be added to the loan amount or paid in full as part of your closing costs. In addition, FHA loans also have a 0.8-0.85% (of the loan amount) monthly mortgage insurance. In most cases, this mortgage insurance remains for the life of the loan. To eliminate the mortgage insurance, the borrower must refinance the loan into a non-FHA loan program and have 20% equity in the property.

In addition to the down payment requirements on a FHA loan, they’re closing costs and prepaids to pay at closing. The  seller can contribute up to 6% of the sales price to help the buyer with closing costs and prepaid expenses. Closing costs vary from lender to lender and your prepaids would be the same no matter which lender you choose because this is a function of the property ‘s home insurance premium quote you obtain and the property tax bill on the home set by PVA.

Sometimes the lender can pay a credit toward these expenses at closing with a lender credit which lets the lender credit back to you with a higher rate to reduce the costs of the loan’s costs at closing for out of pocket expenses.

All Kentucky FHA loans are assumable, which means that when the homeowner sells a home, the buyer may be able to take on the existing loan and terms (e.g.: balance, rate and remaining loan amount). Of course, anyone interested in the assumable loan feature must go through the approval process (credit check, income verification) with the current lender on the property. This is a very rare occurrence because most sellers are going to sell the home for more than they owe on it.

Kentucky FHA Loan Requirements


The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people. NMLS ID# 57916, (www.nmlsconsumeraccess.org). USDA Mortgage loans only offered in Kentucky.

All loans and lines are subject to credit approval, verification, and collateral evaluation

 FHA Mortgage Loans- Gifts to Pay off Debt to Qualify for a FHA Home Loan.


FHA Loans in Kentucky  – Gifts to Pay off Debt

Do you know that a gift can be used to pay off Borrower’s debts to qualify on an Kentucky FHA Loan?

A regular gift (this does not include a gift of equity) may be used to pay off a Borrower’s debt(s) for qualifying purposes as long as both the gift funds and the debt(s) being paid off with the gift funds are accurately disclosed and assessed by AUS TOTAL Scorecard. Whenever a gift is received on an Kentucky FHA loan, regardless of what it is being used for, it carries certain risks that must be assessed by TOTAL Scorecard for qualifying purposes.

When a gift is received to pay off debt(s), follow the steps below to ensure that TOTAL Scorecard accurately assesses the risk of using gift funds in paying off debt for qualifying:

  • Verify that evidence of the debt(s) having a zero balance has been obtained,
  • Enter the gift funds received separate from any account balances and check “will be paid off” for debts in loan origination system (not “paid off”), and
  • Submit the loan to TOTAL Scorecard
 
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708
kentuckyloan@gmail.com

http://www.nmlsconsumeraccess.org/
If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

Getting a FHA Loan Approved with the new Guidelines for Student Loans in Kentucky for 2018

2018 KENTUCKY FHA MORTGAGE GUIDELINES FOR APPROVAL WITH STUDENT LOANS

images-3

Student Loan Payment Calculation
Must include all student loans in the borrower’s liabilities, regardless of the payment type or status of payments.

Calculation of monthly obligation, regardless of the payment status, must use either:
the greater of:
• 1 percent of the outstanding balance on the loan; or
• the monthly payment reported on the borrower’s credit report; or

the actual documented payment, provided the payment will fully amortize the loan over its term.
Additional documentation required if the payment used for the monthly obligation is:
• less than 1 percent of the outstanding balance reported on the borrower’s credit report;and
• less than the monthly payment reported on the borrower’s credit report.
Provide written documentation of the actual monthly payment, the payment status, and evidence of the outstanding balance and terms from the creditor.
Guide Reference – 4000.1 II.A.4.b.iv(H) (TOTAL) and II.A.5.a.iv.(G) (Manual)

gotquestion-1

50dd9-object_preapproval

I can answer your questions and usually get you pre-approved the same day.

Call or Text me at 502-905-3708 with your mortgage questions.
Email Kentuckyloan@gmail.com


Joel Lobb (NMLS#57916)
Senior  Loan Officer
 
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708
kentuckyloan@gmail.com

The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only.  The posted information does not guarantee approval, nor does it comprise full underwriting guidelines.  This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of  my employer. Not all products or services mentioned on this site may fit all people.
, NMLS ID# 57916, (www.nmlsconsumeraccess.org). I lend in the following states: Kentucky