How does Kentucky FHA Mortgage Rates work?

Kentucky FHA mortgage loans are backed by the Federal Housing Administration under the umbrella of HUD. FHA loans were developed to help borrowers that don’t have a large down payment and a weaker credit profile to buy and refinance their home mortgage loan.

​Kentucky FHA rates are backed by the government, so they are typically lower than other mortgage rates in the secondary market like Conventional loans and portfolio loans at banks, but fall in line compatible to other backed government loans in the secondary market likeUSDA, VA, mortgage loans. Most people seeking FHA mortgages will get a 30 year, 20 year of 15 year fixed rate loan with the security of the house payment not changing. ​

​Lower Credit Standards and Credit Scores for FHA loans

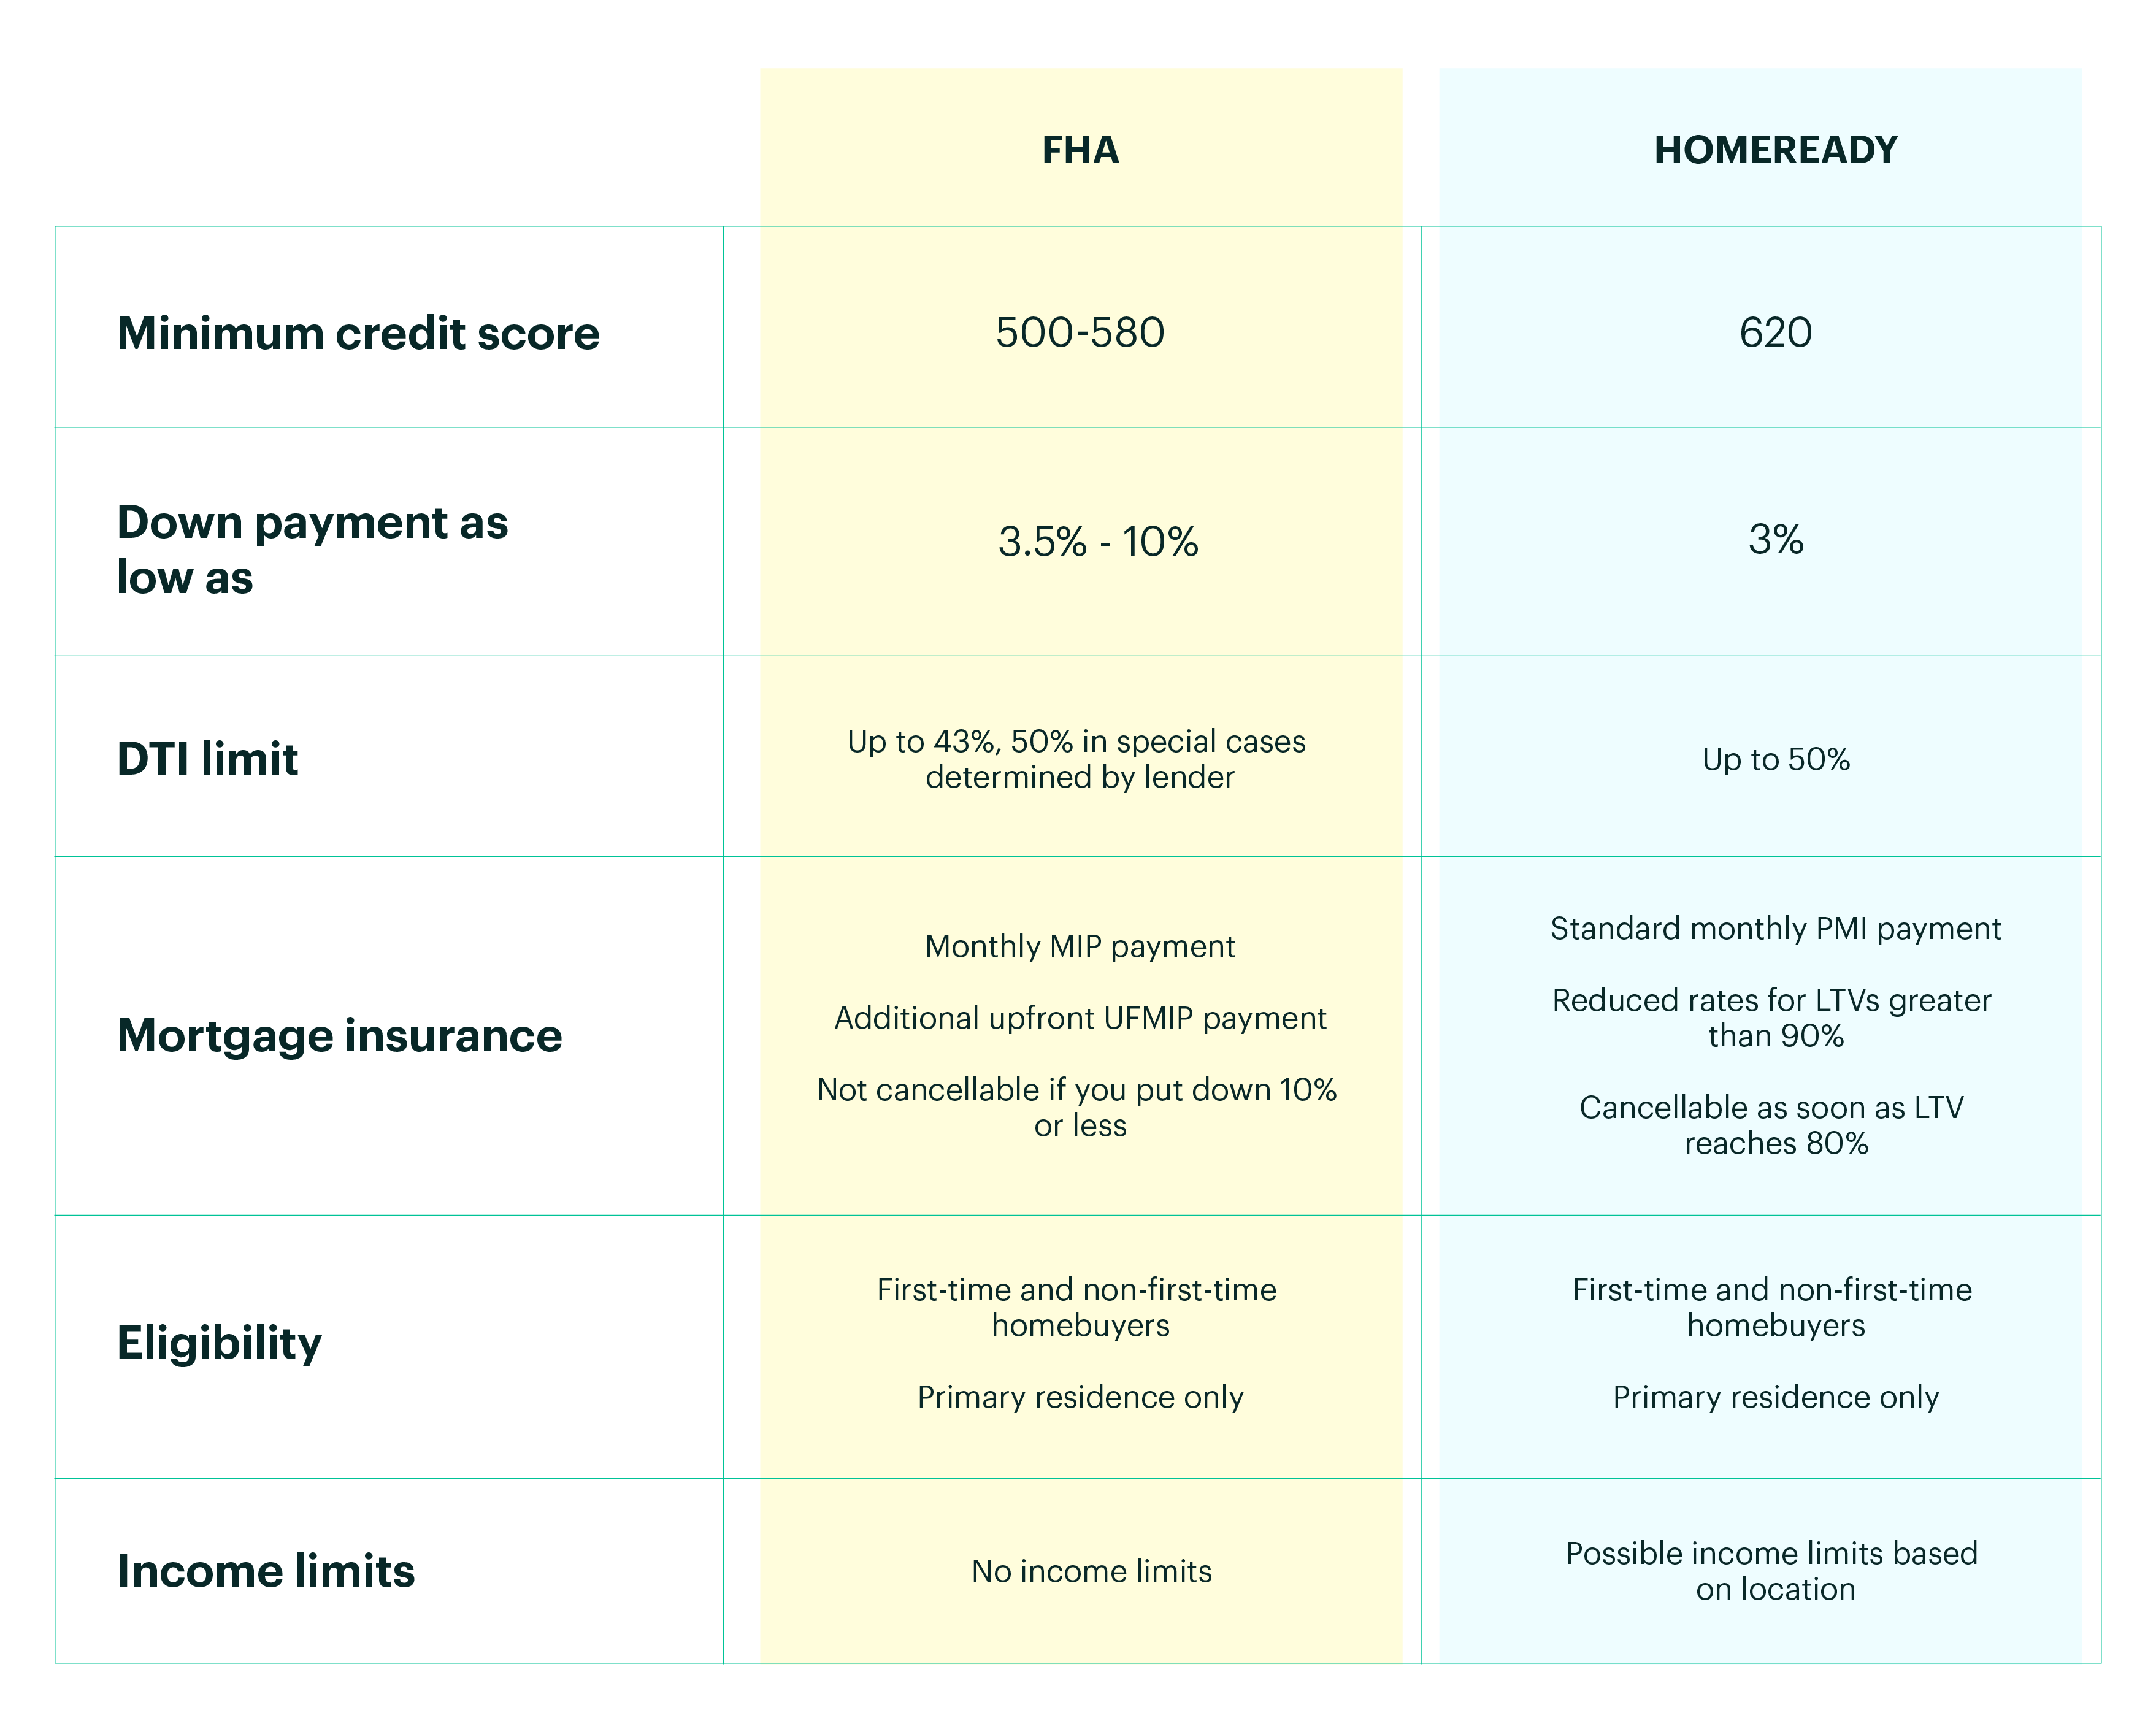
FHA mortgages will go down to a 500 credit score with at least 10% down payment, and if your credit score is higher than 580, you can put the minimum of 3.5% down payment. Additionally, you need to be only 2 years removed from a Chapter 7 bankruptcy, or 1 year from a Chapter 13 bankruptcy.

​Mortgage Insurance on FHA loans

Mortgage insurance is required on most FHA loans and is usually for life of loan with everyone paying the same. If you have a higher credit score and a larger down payment, it would make sense to look at doing a conventional mortgage loan because they are based on your credit score, money down, and debt to income ratio and not for life of loan.

You can get a lower FHA mortgage insurance premium and not have to finance the premiums for life of the loan if you put more than 10% down payment and finance on a 15 year term.

​Why would you consider a FHA mortgage?

​My best opinion is this. ​​​If you have a bankruptcy that is less than 4 years, have a credit score lower than 660, and very little money down, I would recommend at looking to do a FHA mortgage Loan. Your chances of getting approved with likely result in a loan approval as opposed to doing a conventional loan backed by Fannie Mae.

Why would you consider a Conventional Loan?

My best opinion is this. If you have a bankruptcy over 4 years or longer, at least 5% down payment, a credit score of 680 or higher, I would look doing a conventional mortgage loan.


Video: Kentucky FHA mortgage rates and loan options explained
▶ Click to watch on YouTube


​I can help you understand what mortgage is correct for you. Please contact me below and I will be happy to answer any questions.
Got questions about your Kentucky mortgage? Contact Joel Lobb
Joel Lobb (NMLS#57916)
Senior Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708

kentuckyloan@gmail.com


If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.


Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

How to qualify for a Kentucky FHA Home Loan ?

How to qualify for a Kentucky FHA Home Loan ?

Image result for fha loans ky


FHA stands for the Federal Housing Administration which is a government agency created to increase home-ownership across the United States all the way back in 1934. The agency itself doesn’t offer home loans but insures loan that are offered by private lenders (i.e. mortgage companies).

It’s important to understand the different types of loan programs available to you and what benefits and drawbacks there are to each type.

For example, if you’re looking to find a fixer upper this may not be the right loan program for you. But an FHA loan may be a better fit for you if you have little cash saved up for a down payment or if you don’t have a high credit score.

Kentucky FHA loan requirements:

  • At least 18 years old to apply
  • No age limit. just must be 18 years of age to apply.
  • Must occupy the home as a primary residence, no rental homes or investment property
  • An appraisal must be done by an FHA-approved appraiser.Typically FHA appraisal in Kentucky costs anywhere from low-end $325 to $525 with most FHA lenders in KY.
  • Home inspection is not required
  • Termite inspection not required
  • 2 years removed from Chapter 7 bankruptcy, and 1 year in Chapter 13 bankruptcy is possible to get a loan while in bankruptcy
  • Foreclosure or short sale on previous home mortgage requires 3 years removal from those dates.
  • Mortgage insurance (MIP) is required
  • Upfront Mortgage Insurance Premium is 1.75% and monthly mortgage insurance is .85% or .80% depending on loan term and loan to value.
  • Mortgage insurance is for life of loan.
  • No matter your credit scores, everyone pays the same mortgage insurance premiums.
  • Must have 2 years of employment history proving a reliable source of income
  • 500 FICO score requirement with at least 10% down payment
  • 580 FICO score requirement with at least 3.5% down payment
  • Gifts and down payment assistance programs are allowed to meet your down payment requirements. Cannot come from seller, but seller can contribute up to 6% of the sales price toward buyer’s closing costs and prepaids.
  • Student loan payments are factored into the debt-to-income ratio when applying. Typically if loans are deferred, or in an income=based repayment plan, the FHA underwriters will use 1% of the outstanding balance, which sometimes can make it difficult to qualify.
  • Your debt-to-income ratio must not be higher than 31% or total debt obligation cannot be higher than 43% of your current income. This is for a manual underwriter, meaning that if the AUS underwriting system by mortgage lenders will approve you for a higher debt to income ratio, that is fine.


Joel Lobb (NMLS#57916)
Senior  Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346

Text/call 502-905-3708kentuckyloan@gmail.com

If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/
— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

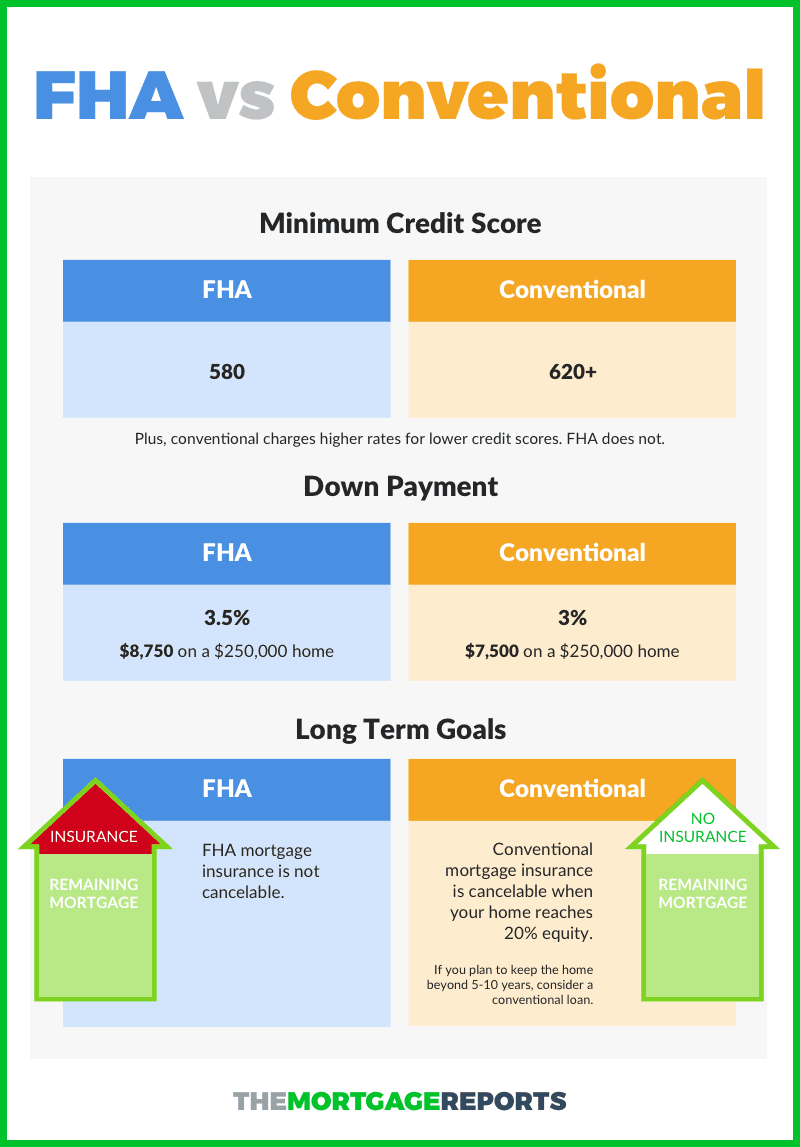
FHA vs Conventional Infograhic

 FHA Mortgage Loans- Gifts to Pay off Debt to Qualify for a FHA Home Loan.


FHA Loans in Kentucky  – Gifts to Pay off Debt

Do you know that a gift can be used to pay off Borrower’s debts to qualify on an Kentucky FHA Loan?

A regular gift (this does not include a gift of equity) may be used to pay off a Borrower’s debt(s) for qualifying purposes as long as both the gift funds and the debt(s) being paid off with the gift funds are accurately disclosed and assessed by AUS TOTAL Scorecard. Whenever a gift is received on an Kentucky FHA loan, regardless of what it is being used for, it carries certain risks that must be assessed by TOTAL Scorecard for qualifying purposes.

When a gift is received to pay off debt(s), follow the steps below to ensure that TOTAL Scorecard accurately assesses the risk of using gift funds in paying off debt for qualifying:

  • Verify that evidence of the debt(s) having a zero balance has been obtained,
  • Enter the gift funds received separate from any account balances and check “will be paid off” for debts in loan origination system (not “paid off”), and
  • Submit the loan to TOTAL Scorecard
 
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708
kentuckyloan@gmail.com

http://www.nmlsconsumeraccess.org/
If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant  Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/
— Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

Kentucky FHA Loan Requirements For Loan Approval.

images (3)


FHA Handbook 4000.1 Updates

Administration (FHA) Single Family Housing Policy Handbook 4000.1. These updates are effective September 30, 2016 and

 Clarification that an Upfront Mortgage Insurance Premium (UFMIP) refund calculation applies even if original UFMIP was
not financed.
 Mortgage Debt Not Included in Credit Report: Clarification that a manual downgrade is not required when there is no history of late payments, as detailed below.
o Not currently delinquent; and
o No 30 day late payments within 12 months of the case number assignment date; and
o No more than 2 x 30 day late payments within 24 months of the case number assignment date.
 A link has been added in the FHA Product Description from Mortgage Payment History requirements to “Credit History
Requirements for Manually Underwritten Loans.”
Appliances that add contributory value must be operable.
 Mechanical components and utilities: The appraiser must report the utility, safety, and capacity of the mechanical systems.
The appraiser must observe and operate all applicable mechanical systems and utilities. In conjunction with this guidance,
existing FHA Handbook guidance on the following topics will be added:
o Electrical System
o Heating and Cooling
o Plumbing
o Utilities

If you have questions about qualifying as first time home buyer in Kentucky, please call, text, email or fill out free prequalification below for your next mortgage loan pre-approval.


The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only.  The posted information does not guarantee approval, nor does it comprise full underwriting guidelines.  This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the views of my employer. Not all products or services mentioned on this site may fit all people

A fast and easy refinance for those with an FHA mortgage | CharlotteObserver.com

A fast and easy refinance for those with an FHA mortgage | CharlotteObserver.com.

Verification and documentation requirements are also very light compared to the traditional mortgage requirements. With an FHA refinance, there is no employment verification and no income verification. While the FHA approves these lighter requirements, some individual lenders may decide to verify these items for their own purposes.

FHA Streamline Refinance also does not require a credit score verification. Instead, payment history is used as a guideline for your ability to pay the loan in the future. So, low FICO scores are not a problem as long as your payment history is in good shape.

The FHA Streamline Refinance program does require several things to get your loan approved:

• First, you’ll need a history of making payments on time over the past year, and at least six months must have passed since the closing date on your original FHA mortgage.

• Second, while there are no requirements for employment verification or income verification, you do need to provide copies of your W-2s or tax returns.

• Third, your loan balance cannot increase to cover closing costs. You can only add the upfront portion of the required mortgage insurance premium to the balance of your loan. So, the new loan balance can’t exceed the current amount outstanding, plus the upfront portion of the mortgage insurance premium. You’ll either have to pay the closing costs upfront in cash, or qualify with your lender for a zero-cost FHA Streamline refinance.

• Finally, the refinance must have a purpose that benefits the homeowner, such as significantly lowering the monthly mortgage payments, or moving from an adjustable-rate mortgage to a more stable fixed-rate mortgage. If lowering the monthly payment is the purpose, you must be able to demonstrate at least a 5 percent drop in your monthly mortgage payments, including the mortgage insurance premiums.

The FHA frequently updates these mortgage guidelines, and individual lenders may add their own specific requirements, so it’s best to check with your preferred lender to determine your exact situation. Also, if your original FHA mortgage was closed after May 31, 2009, the mortgage insurance premiums most likely will be significantly higher, so make sure to evaluate those costs carefully versus the savings you’ll receive from the lower interest rate.

Joel Lobb (NMLS#57916)
Senior  Loan Officer
502-905-3708 cell
502-813-2795 fax
kentuckyloan@gmail.com

Key Financial Mortgage Co. (NMLS #1800)*
107 South Hurstbourne Parkway*

Louisville, KY 40222*