Understanding FHA Appraisal Rules in Kentucky

2026 Kentucky FHA Mortgage Guide

Kentucky FHA Appraisal Requirements for Mortgage Loan Approval

If you are buying a home in Kentucky with an FHA loan, the appraisal is not just about value. FHA also reviews the property condition to make sure the home meets basic HUD safety, security, and livability standards.

Call or Text Joel: 502-905-3708 Email Joel

FHA appraisals can make or break a Kentucky home purchase. A property may appraise for enough money, but still require repairs before the loan can close. That is where buyers, sellers, and realtors sometimes get caught off guard.

The goal of this guide is to explain the major FHA appraisal rules in plain English, including property condition issues, appraisal validity, FHA flipping rules, and how FHA compares with VA, USDA, and conventional financing.

Bottom line: FHA is a strong loan program for many Kentucky buyers, especially buyers with limited down payment funds, but the property still has to meet FHA standards before closing.

Table of Contents

  1. What Is an FHA Appraisal?
  2. Core FHA Appraisal Requirements
  3. FHA Appraisal Validity Period
  4. FHA Anti-Flipping Rules
  5. Exceptions to FHA Flipping Rules
  6. FHA vs. VA, USDA, and Conventional Appraisals
  7. Frequently Asked Questions
  8. Contact Joel Lobb

What Is an FHA Appraisal in Kentucky?

An FHA appraisal is completed by an FHA-approved appraiser. The appraiser reviews the property to determine whether the value supports the purchase price and whether the property meets HUD minimum property standards.

A conventional appraisal is mainly focused on market value. FHA goes further because the property must also meet minimum standards for health, safety, and soundness.

The FHA appraisal has two main jobs:

  • Confirm market value. The appraiser compares the home to similar recent sales to determine whether the purchase price is supported.
  • Review property condition. The appraiser looks for obvious health, safety, and structural concerns that may need to be repaired before closing.

Kentucky buyer tip: The buyer, seller, realtor, and loan officer do not directly select the appraiser. The appraisal is ordered through an independent appraisal process to protect the integrity of the valuation.

Core FHA Appraisal Requirements for Kentucky Properties

FHA does not require the home to be perfect. It does require the property to be safe, structurally sound, and livable. Cosmetic issues usually are not a problem. Health, safety, or structural issues usually are.

Common FHA property items appraisers review

  • Permanent heat source: The home needs a working, permanent heat source capable of heating the living area.
  • Utilities on and working: Electricity, water, plumbing, and other utilities should be on and functional at the time of appraisal.
  • Roof condition: The roof should not show obvious active leaks or major deterioration.
  • Electrical safety: Exposed wiring, missing covers, or unsafe electrical conditions may be flagged.
  • Peeling paint: Peeling or chipping paint can be an issue, especially on homes built before 1978 because of lead-based paint concerns.
  • Stairs, decks, and handrails: Unsafe stairs, missing railings, or unstable decks may require correction.
  • Water intrusion: Standing water, visible moisture damage, or active leaks may create an FHA repair condition.
  • Functional kitchen and bathroom: The home should have basic working kitchen and bathroom facilities.

Important: If the appraiser calls for repairs, those repairs normally must be completed and reinspected before the FHA loan can close. This can delay closing if the seller is not prepared.

Property types that may work with FHA

  • Single-family homes
  • Eligible manufactured homes on a permanent foundation
  • Approved condominiums
  • Eligible multi-unit properties, if the borrower will occupy one of the units
  • New construction, if the property meets FHA and lender requirements

FHA Appraisal Validity Period

FHA appraisal validity rules were updated for case numbers assigned on or after June 1, 2022. In most standard FHA forward mortgage transactions, the initial FHA appraisal is valid for 180 days from the effective date of the appraisal report. An appraisal update can extend the validity period to one year from the effective date of the original appraisal.

Appraisal Item Current FHA Rule
Initial FHA appraisal Generally valid for 180 days from the effective date
Appraisal update May extend validity up to one year from the original appraisal effective date
Old 30-day extension Eliminated under the updated FHA guidance

What this means: Kentucky buyers have more time to close before the appraisal expires, which can help when repairs, title issues, underwriting conditions, or seller delays slow down the file.

FHA Anti-Flipping Rules in Kentucky

FHA flipping rules matter when the seller recently bought the property and is now reselling it. This is common with investor-owned homes, renovated homes, wholesale transactions, and properties purchased through foreclosure or auction.

The 90-day FHA flipping rule

If the seller has owned the property for 90 days or fewer, the property is generally not eligible for FHA financing. This is one of the biggest FHA deal killers on recently renovated homes.

The 91-180 day FHA flipping rule

If the seller has owned the property between 91 and 180 days, FHA may require a second appraisal if the resale price is 100% or more over the price paid by the seller.

Seller Ownership Period FHA Impact
0-90 days Generally not eligible for FHA financing
91-180 days Second appraisal may be required if resale price is 100% or more above the seller’s purchase price
181+ days Standard FHA appraisal rules generally apply

Realtor warning: Before writing an FHA offer on a flipped or renovated property, verify when the seller acquired title. The listing date does not control the FHA flip clock. The seller’s acquisition date does.

Exceptions to FHA Anti-Flipping Rules

Some transactions may be exempt from FHA property flipping restrictions. These exceptions can include certain sales by government agencies, inherited properties, relocation companies, HUD REO properties, and new construction homes that were never occupied.

Even when an exception may apply, the lender still has to document the file correctly. Do not assume the exception applies until the title history and supporting documentation are reviewed.

How FHA Appraisal Rules Compare to VA, USDA, and Conventional Loans

FHA is not the only loan option for Kentucky buyers. Depending on credit, income, military eligibility, property location, and down payment funds, VA, USDA, or conventional financing may be a better strategic fit.

Loan Program Appraisal / Property Notes
FHA Strong option for many buyers, but property condition and FHA flipping rules must be reviewed carefully.
VA No monthly PMI and no down payment for eligible veterans, but VA minimum property requirements still apply.
USDA Rural Housing Zero down payment option for eligible rural properties and eligible household income, with property condition standards similar to FHA in many areas.
Conventional / Fannie Mae May be more flexible on certain property issues, but credit, debt ratio, down payment, and private mortgage insurance must be considered.

Need to Know If a Kentucky Property Will Pass FHA?

Before you spend money on inspections, appraisal fees, or moving forward with a questionable property, it is smart to have the financing reviewed upfront.

Call or text Joel Lobb at 502-905-3708 or email kentuckyloan@gmail.com to review your FHA, VA, USDA, KHC, or conventional mortgage options.

Frequently Asked Questions About FHA Appraisals in Kentucky

How long is an FHA appraisal valid?

For many standard FHA forward mortgage transactions with case numbers assigned on or after June 1, 2022, the initial appraisal is valid for 180 days from the effective date of the appraisal report. An eligible appraisal update can extend validity to one year from the original appraisal effective date.

Can a recently flipped home qualify for FHA financing?

Possibly, but timing matters. If the seller has owned the home for 90 days or fewer, FHA financing is generally not available. If the seller has owned it for 91 to 180 days and the resale price is 100% or more above what the seller paid, FHA may require a second appraisal.

Who orders the FHA appraisal?

The lender orders the appraisal through an independent appraisal process. Buyers, sellers, realtors, and loan officers do not directly choose the appraiser.

What happens if the FHA appraisal comes in low?

If the appraised value is lower than the contract price, the buyer and seller may need to renegotiate, the buyer may need to bring the difference in cash, or the buyer may need to evaluate whether the contract allows them to cancel. The loan amount is based on the lower of the purchase price or appraised value.

What are common FHA repair items?

Common FHA repair items include peeling paint, exposed wiring, missing handrails, roof problems, broken windows, water intrusion, unsafe stairs, and non-working utilities or mechanical systems.

Can an FHA appraisal be transferred to another lender?

FHA appraisals can often be transferred between lenders with the FHA case number and appraisal report, subject to lender review and FHA requirements.

Contact Joel Lobb for a Kentucky Mortgage Pre-Approval

If you are buying a home in Kentucky and want to know whether FHA, VA, USDA, KHC, or conventional financing is the right path, contact Joel Lobb for a mortgage pre-approval review.

About Joel Lobb

Joel Lobb is a Kentucky mortgage loan officer specializing in FHA, VA, USDA, KHC, and conventional mortgage loans. With over 20 years of mortgage experience, Joel helps Kentucky homebuyers understand their loan options, improve file readiness, and move through the pre-approval and underwriting process with confidence.

Joel Lobb
Mortgage Loan Officer
NMLS #57916
EVO Mortgage | Company NMLS #1738461

Equal Housing Lender. This is not a commitment to lend. All loans are subject to credit approval, property approval, program requirements, and underwriting approval. Mortgage loans only offered in Kentucky. Not affiliated with FHA, VA, USDA, KHC, HUD, or any government agency. NMLS #57916 | Company NMLS #1738461.
Mortgage Rates in Kentucky: A Complete Guide

Mortgage Rates Today in Kentucky for FHA, VA, USDA and Conventional Home Loans

If you are buying a home in Kentucky, your mortgage rate is only one part of the total loan cost. The lowest advertised rate is not always the best loan if it comes with high discount points, lender fees, or a higher cash-to-close requirement.

As a Kentucky mortgage broker, I help homebuyers compare FHA, VA, USDA, KHC, and conventional loan options so they can understand the true cost of the rate, the monthly payment, closing costs, mortgage insurance, and how long it may take to break even if they pay points to buy the rate down.

Mortgage rates change daily and are based on credit score, loan type, down payment, property type, occupancy, debt-to-income ratio, and current market conditions. The best way to compare Kentucky mortgage rates is to review a full Loan Estimate, not just the interest rate.

How to Compare Kentucky Mortgage Rates the Right Way

When comparing mortgage rates in Kentucky, do not look at the interest rate by itself. You also need to compare:

  • Interest rate
  • APR
  • Discount points
  • Origination charges
  • Lender credits
  • Monthly payment
  • Mortgage insurance
  • Total cash needed to close

A lower rate with expensive discount points may not make sense if you plan to refinance, sell, or pay the loan off before reaching the break-even point.

Get a Kentucky Mortgage Rate Quote

Want to compare FHA, VA, USDA, KHC, and conventional mortgage options side by side? I can review your credit score, down payment, loan type, and estimated payment range to help you find the best structure for your situation.

Call or text Joel Lobb at 502-905-3708

Email: kentuckyloan@gmail.com

NMLS #57916 | EVO Mortgage Company NMLS #1738461

Equal Housing Lender. Not affiliated with FHA, VA, USDA, HUD, Kentucky Housing Corporation, or any government agency. This is not a commitment to lend. All loans are subject to credit approval, program guidelines, and property approval.

{ “@context”: “https://schema.org”, “@type”: “FAQPage”, “mainEntity”: [ { “@type”: “Question”, “name”: “What is the best mortgage rate in Kentucky today?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “The best mortgage rate in Kentucky depends on the loan type, credit score, down payment, debt-to-income ratio, property type, occupancy, and whether the borrower is paying discount points. FHA, VA, USDA, KHC, and conventional loans may all price differently.” } }, { “@type”: “Question”, “name”: “Are FHA mortgage rates lower than conventional mortgage rates?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “FHA mortgage rates may be competitive, especially for borrowers with lower credit scores, but FHA loans also include upfront and monthly mortgage insurance. Conventional loans may be better for borrowers with stronger credit and lower mortgage insurance costs.” } }, { “@type”: “Question”, “name”: “Do VA loans have good mortgage rates in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “VA loans often offer competitive fixed rates, no monthly PMI, and zero down payment for eligible veterans, active-duty service members, and qualifying surviving spouses. Final approval depends on VA eligibility, credit, income, property approval, and lender guidelines.” } }, { “@type”: “Question”, “name”: “Do USDA loans offer zero down payment in Kentucky?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “USDA Rural Housing loans may allow zero down payment for eligible homes in qualifying rural areas of Kentucky. Borrowers must meet USDA income limits, credit guidelines, property eligibility rules, and underwriting requirements.” } }, { “@type”: “Question”, “name”: “Should I pay points to lower my Kentucky mortgage rate?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “Paying points can lower the interest rate and monthly payment, but it increases upfront closing costs. Borrowers should compare the monthly savings against the extra cost to calculate the break-even point before deciding.” } }, { “@type”: “Question”, “name”: “What is a par mortgage rate?”, “acceptedAnswer”: { “@type”: “Answer”, “text”: “A par mortgage rate generally means the rate is offered without paying discount points to buy the rate down and without taking a higher rate for lender credits. Actual pricing depends on the lender, market conditions, credit score, loan program, and loan structure.” } } ] }

Understanding USDA Loan Asset Requirements in Kentucky

USDA Loan Asset Requirements in Kentucky: What First-Time Homebuyers Need to Know

If you’re applying for a USDA Rural Housing loan in Kentucky, understanding the asset documentation requirements is a critical step in the approval process. Whether you’re a first-time homebuyer in Louisville, Lexington, or a rural Kentucky community, here’s exactly what you need to know about assets when applying for a USDA mortgage loan.

Do You Need Assets to Qualify for a USDA Loan in Kentucky?

Good news for many Kentucky homebuyers — assets are not required to qualify for a USDA Rural Housing loan. However, if you do disclose assets on your loan application, every asset listed must be supported with proper documentation. Incomplete or unsupported asset disclosures can delay or jeopardize your approval.

USDA Loan Asset Documentation Requirements

Below is a complete breakdown of how different types of assets are handled under USDA Rural Housing loan guidelines in Kentucky:

1. Bank Accounts (Checking & Savings)

To verify funds held in a bank account, your lender will require one of the following:

  • A completed Verification of Deposit (VOD) showing the average 2-month balance, or
  • Two consecutive months of bank statements dated within 45 days of the loan application date

Important: Cash on hand is not acceptable as a verified asset for USDA loan purposes. All funds must be traceable and documented.

2. Large Deposits or Sudden Increases in Liquid Assets

If your bank statements show large, unexplained deposits or a significant jump in your account balance, your lender will require a satisfactory written explanation along with supporting documentation. This is a standard USDA underwriting requirement designed to ensure the source of funds is legitimate and not a loan.

3. Earnest Money Deposits

Your earnest money deposit (the good-faith deposit made when you go under contract on a home) may be counted as an asset — provided it is not already reflected in your existing liquid asset balances. Be sure to provide a copy of your cancelled check or wire confirmation as documentation.

4. Retirement Accounts (401k, IRA, Pension)

Retirement accounts such as a 401(k) or IRA can be used as assets for USDA loan qualification, but only at 60% of the vested account balance. This adjustment accounts for early withdrawal penalties and taxes. A current account statement is required.

5. Gift Funds

Gift funds from a family member or approved donor are allowed under USDA guidelines. To properly document a gift, you will need:

  • A signed gift letter from the donor clearly stating the amount of the gift
  • Confirmation that the gift does not need to be repaid
  • Documentation showing the transfer of funds (bank statements, wire transfer, etc.)

6. Proceeds from the Sale of Real Property

If you are using proceeds from the sale of a home or other real estate, you must provide a HUD-1 Settlement Statement or equivalent closing disclosure showing the actual net cash proceeds received by the borrower after all costs and payoffs.

7. Stocks, Bonds, and Investment Accounts

Stocks, bonds, and brokerage accounts must be documented with an official statement from the stockbroker or financial institution managing the portfolio. The statement should show current market value and be dated within 45 days of application.

8. Net Family Assets Greater Than $5,000 — Income Calculation Rule

This is an often-overlooked USDA guideline. If a household’s net family assets exceed $5,000, USDA requires that the greater of the following be counted as income:

  • The actual income earned from those net family assets (e.g., interest, dividends), or
  • A percentage of the asset value based on the current passbook savings rate

This imputed income is added to your annual household income and can affect USDA income eligibility. Be sure to discuss this with your loan officer if you have significant savings, investments, or property holdings.


Why Asset Documentation Matters for Your Kentucky USDA Loan Approval

USDA underwriters review asset documentation not just to verify your down payment and closing costs, but also to ensure your loan complies with federal housing guidelines. Incomplete or missing asset paperwork is one of the most common reasons for loan delays in Kentucky. Working with an experienced local mortgage loan officer who knows USDA guidelines inside and out can make all the difference.

Get Pre-Approved for a USDA Loan in Kentucky Today

With over 20 years of experience helping Kentucky families achieve homeownership, I specialize in USDA Rural Housing loans, FHA, VA, KHC (Kentucky Housing Corporation), and Conventional mortgage loans. I offer free mortgage pre-qualifications with same-day approvals on most applications.

If you’re a first-time homebuyer in Kentucky with little or no money saved for a down payment, ask me about Kentucky Housing Corporation (KHC) down payment assistance programs — funds are still available and can significantly reduce your upfront costs.

Contact Joel Lobb — Kentucky Mortgage Loan Officer

Joel Lobb | Senior Mortgage Loan Officer

📞 Call or Text: (502) 905-3708

📧 Email: kentuckyloan@gmail.com

🌐 Website: www.mylouisvillekentuckymortgage.com

NMLS #57916 | Company NMLS #1738461

Verify license: www.nmlsconsumeraccess.org

Kentucky Mortgage License Only

⚖️ Equal Housing Lender
This website is not affiliated with or endorsed by HUD, FHA, VA, USDA, or any government agency. It is an independent platform created to educate and assist Kentucky homebuyers.

2026 FHA Loan Options for Kentucky Homebuyers

Kentucky FHA Loan Requirements – Updated for 2026

Kentucky FHA loan guidelines are established by the U.S. Department of Housing and Urban Development (HUD). FHA loans remain one of the most flexible mortgage options available to Kentucky homebuyers, particularly first-time buyers, borrowers rebuilding credit, and households using down payment assistance.

Employment and Income Requirements

Borrowers must demonstrate a stable employment history covering the most recent two years. This does not require the same employer, but the work history must show consistency in the same industry or line of work.

Recent college graduates may satisfy the two-year work history requirement by providing college transcripts, provided the current employment aligns logically with the education received.

Self-employed borrowers must document a minimum two-year history of self-employment and provide the most recent two years of federal tax returns filed with the IRS. FHA underwriting uses a two-year average of qualifying income, adjusted for business stability and trends.

All income must be verifiable through acceptable documentation such as pay stubs, W-2s, or tax returns. Cash income, undocumented deposits, or bank-statement-only income is not permitted for FHA qualifying purposes.

Down Payment Requirements

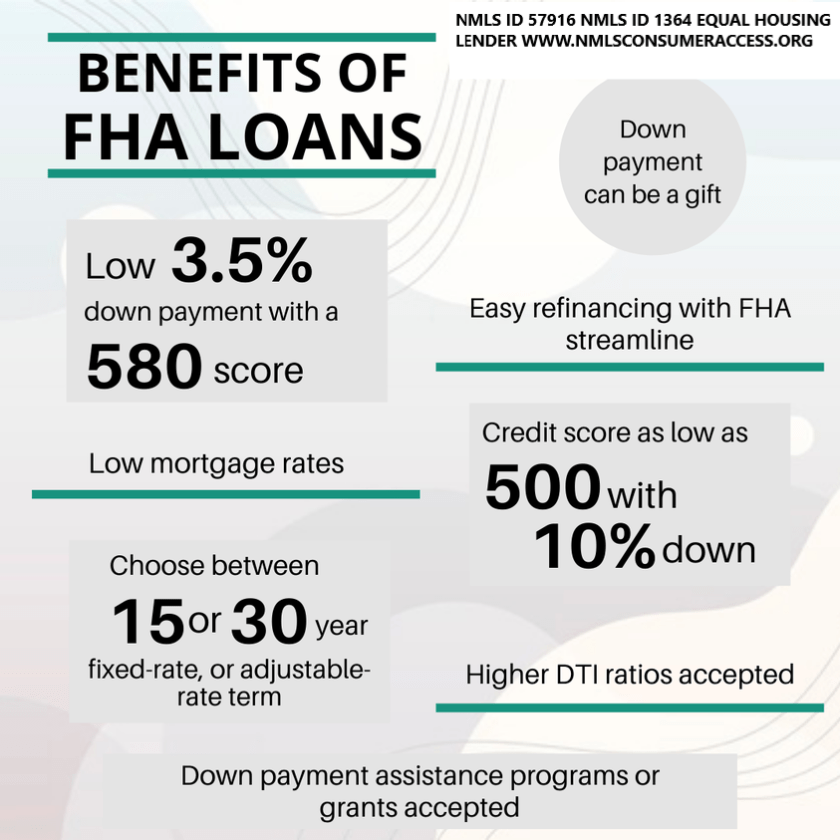
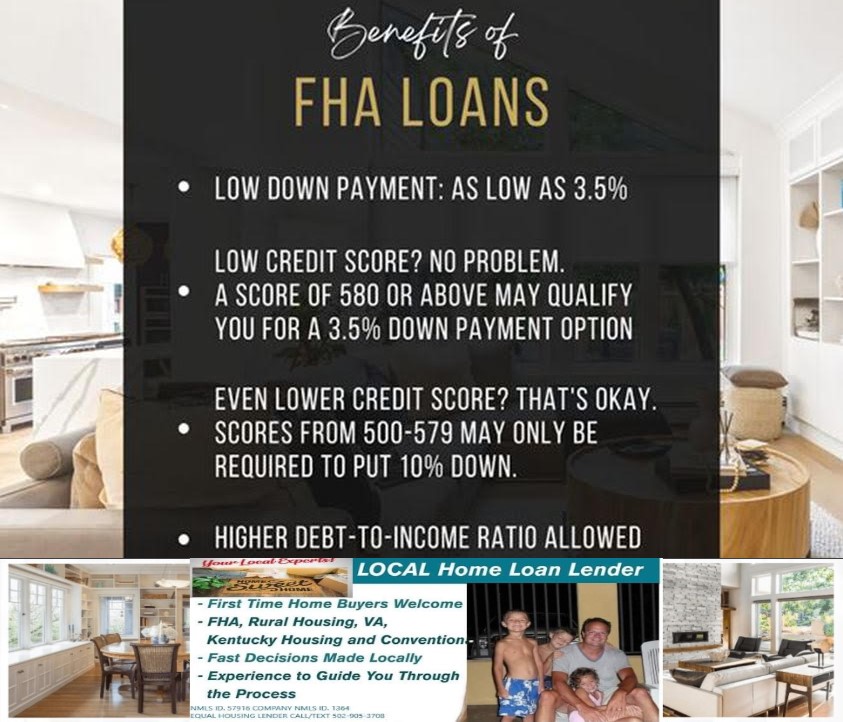
FHA loans require a minimum down payment of 3.5 percent for borrowers with credit scores of 580 or higher.

Borrowers with credit scores between 500 and 579 are limited to a maximum loan-to-value of 90 percent, requiring a minimum 10 percent down payment. In practice, most lenders apply overlays requiring higher credit scores, typically between 580 and 620, even though HUD technically allows lower scores.

Down payment funds must come from an approved source. Acceptable sources include personal savings, retirement account loans or withdrawals, and properly documented gift funds. Large or undocumented cash deposits are not allowed and remain one of the most common reasons for FHA loan delays or denials in underwriting.

Occupancy and Property Use

FHA loans are for primary residences only. The borrower must occupy the property as their primary home and move in within 60 days of closing. FHA financing may not be used for rental properties or investment homes.

Appraisal and Property Standards

The property must be appraised by a Kentucky-licensed, FHA-approved appraiser. The home must meet HUD’s minimum property standards, meaning it must be safe, sound, and secure.

Common appraisal concerns include peeling paint, exposed wiring, missing handrails, roof condition, and health or safety hazards. Most FHA appraisal issues are correctable prior to closing.

Debt-to-Income Ratio Guidelines

FHA evaluates two debt ratios:

The housing ratio (front-end), which includes principal, interest, property taxes, homeowners insurance, mortgage insurance, and HOA dues, is typically capped at 31 percent of gross monthly income.

The total debt ratio (back-end), which includes the housing payment plus all other monthly obligations reported on credit, is typically capped at 43 percent.

However, borrowers receiving an “Approve/Eligible” finding through FHA’s automated underwriting system may qualify with higher ratios, depending on credit scores, cash reserves, and other compensating factors.

Credit Score and Credit History Requirements

The minimum FHA credit score for maximum financing remains 580 in 2026. This does not guarantee approval, as lenders apply additional underwriting standards and overlays.

Borrowers must demonstrate acceptable recent payment history. FHA places significant weight on the most recent 12 months of credit performance.

Bankruptcy and Foreclosure Guidelines

Chapter 7 bankruptcy requires a minimum waiting period of two years from discharge, with re-established good credit and on-time payments afterward.

Chapter 13 bankruptcy may be eligible after at least 12 months of on-time plan payments, with trustee approval, and the borrower must qualify including the Chapter 13 payment.

Foreclosure generally requires a three-year waiting period from the date of foreclosure completion. Exceptions may be considered only for documented extenuating circumstances beyond the borrower’s control. Job relocation alone does not qualify as an extenuating circumstance.

Federal Debt and CAIVRS Requirements

Borrowers may not have delinquent federal debt, defaulted federal student loans, unpaid federal judgments, or unresolved FHA claims.

Lenders are required to check the CAIVRS (Credit Alert Interactive Voice Response System) database for all federally backed loans, including FHA, VA, USDA, and SBA loans. Title 31 of the U.S. Code prohibits delinquent federal debtors from receiving federal loan insurance or guarantees.

If a CAIVRS alert appears, the debt must be resolved or paid in full before closing.

FHA Gift Fund Rules for Down Payments

FHA permits gift funds for down payments and closing costs, provided there is no expectation of repayment.

Acceptable gift sources include relatives, employers, labor unions, close friends with a documented relationship, charitable organizations, and government or public entities.

Unacceptable gift sources include the seller, real estate agents, brokers, builders, or any party with a financial interest in the transaction.

A proper gift letter is required, stating that repayment is not expected. The donor must provide identifying information and documentation showing the transfer of funds from their account to the borrower.

Government and Employer Assistance Programs

Borrowers without access to family gift funds may qualify for state, local, or employer-assisted housing programs that provide down payment or closing cost assistance. In Kentucky, FHA loans can often be paired with Kentucky Housing Corporation (KHC) down payment assistance programs, subject to income limits and program availability.

How FHA Loans Are Used in Kentucky

FHA does not directly lend money. Instead, it insures loans made by FHA-approved lenders. These loans are designed for borrowers with limited down payment funds, past credit challenges, or non-traditional credit profiles.

Many Kentucky borrowers who do not qualify for conventional financing are still able to achieve homeownership through FHA-insured loans at competitive interest rates.

Pros and Cons of FHA Loans

Advantages include low down payment requirements, flexible credit standards, and the ability to combine FHA loans with down payment assistance programs.

Disadvantages include mandatory mortgage insurance. FHA charges an upfront mortgage insurance premium of 1.75 percent of the loan amount, which can be financed, and an annual mortgage insurance premium that ranges from approximately 0.45 percent to 1.05 percent depending on loan term, loan-to-value, and origination date. This annual premium is paid monthly and, in most cases, remains for the life of the loan unless refinanced.

Final Thoughts for Kentucky Homebuyers in 2026

FHA loans continue to be a practical, reliable option for Kentucky homebuyers who need flexibility without sacrificing long-term stability. While FHA guidelines are forgiving compared to conventional loans, preparation matters. Clean documentation, stable income, responsible credit behavior, and proper sourcing of funds are essential to a smooth approval.

Working with an experienced Kentucky FHA lender can help you navigate overlays, improve credit positioning, and pair FHA financing with available assistance programs.


Joel Lobb
NMLS #57916
Text or Call 502-905-3708
kentuckyloan@gmail.com
www.mylouisvillekentuckymortgage.com

Company NMLS #1738461
Equal Housing Lender

Information is provided for educational purposes only and does not guarantee loan approval. All loans are subject to underwriting guidelines, program availability, and lender approval.

 Buying a Kentucky Home with a FHA Mortgage

Is an Kentucky FHA loan right for you?

Here are some benefits of Kentucky FHA loans 🤩
✅ Low down payment options
✅ Down payment assistance programs available
✅ Higher DTI ratios accepted

FHA requires you to establish that the income is in fact stable. I am covering Time on Job, Part Time Income, Seasonal Income and Job Gaps below.
 
Time on Job
There is not a minimum length of time a borrower must have held a position for the income to be eligible. However, the application must identify the most recent 2 years of employment.
If the borrower’s employment history indicates that they were in school or in the military, then the borrower must provide evidence supporting this such as college transcripts or discharge papers.
The current type of employment has to be supported by the college transcripts or discharge papers showing that he borrower’s training enabled them to gain employment in their field of training.
 
Part Time Income 

Part-time and second job income can be used to qualify if documentation is obtained to prove that the borrower has worked the part-time job uninterrupted for the past two years, and plans to continue.
For Qualifying purposed, “part-time” income refers to jobs taken to supplement the borrower’s main income from regular employment, such as a second job that is less than 40 hours per week.
Income: Is averaged over the previous 2 years. If there was a pay rate increase and we can document the increase in pay, you can average the new pay rate over 12 months.
 
Seasonal Income
Seasonal income may be acceptable for qualifying. It is not unusual to have out-of-season income from unemployment income. If the borrower has a 2 year history and continuance is probable, this type of income may be allowed to qualify the borrower.
The key here is history and continuance.
 
Job Gaps
The borrower must provide a signed explanation for gaps in employment as follows:
Income can be considered effective if the following can be verified:
1. Borrower has been employed in the current job for at least six months at the time of the case number assignment AND
2. A two year work history prior to the absence from employment.
 

What does FHA stand for?

FHA stands for Federal Housing Administration, and the FHA is a government agency that insures mortgages. It was created just after the Great Depression, at a time when homeownership was prohibitively expensive and difficult to achieve because so many Americans lacked the savings and credit history to qualify for a loan. The government stepped in and began backing mortgages with more accessible terms. Approved lenders began funding FHA loans, which offered more reasonable down payment and credit score standards.

Today, government-backed mortgages still offer a safety net to lenders—because a federal entity (in this case, the FHA) is guaranteeing the loans, there’s less financial risk if a borrower defaults on their payments. Lenders are then able to loosen their qualifying guidelines, making mortgages available to middle and low income borrowers who might not otherwise be approved under conventional standards.

What’s the difference between FHA and conventional loans?

Home loans fall into two broad categories: government and conventional. A conventional loan is any mortgage that is not insured by a federal entity. Because private lenders assume all the risk in funding conventional loans, the requirements to qualify for these loans are more strict. Generally speaking, FHA loans might be a good fit if you have less money set aside to fund your down payment and/or you have a below-average credit score. While low down payment minimums and competitive interest rates are still possible with a conventional loan, you’ll need to show a strong credit score to qualify for those advantages.

Each loan type has advantages and disadvantages—including different mortgage insurance requirements, loan limits, and property appraisal guidelines—so choosing the one that works best for you really depends on your financial profile and your homebuying priorities.

FHA loans pros and cons

FHA loans are meant to make homeownership more accessible to people with fewer savings set aside and lower credit scores. They can be a great fit for some borrowers, particularly first time homebuyers who often need lower down payment options, but you should weigh the costs and benefits of any mortgage before committing. Here’s a breakdown of the key pros and cons when it comes to FHA loans:

Pros Cons
Low down payment. Down payments make up the majority of cash to close in any purchase loan, and saving up for one can be a significant barrier for some borrowers. FHA loans make it possible to put down as little as 3.5% upfront and still get competitive rates. Mandatory MIP payments. FHA loans are more lenient, but they also come with insurance costs to mitigate risk to the lender. You’ll have to pay Mortgage Insurance Premiums (MIP) no matter what—either for 11 years or for the life of your loan, depending on your down payment.
Lower credit score. Credit scores can be a major hurdle when it comes to conventional loans, but borrowers with credit scores starting at 500 can qualify for FHA loans. Less competitive. Sometimes sellers can be more hesitant to accept FHA loans. In a competitive market, you might not win out against conventional loan bids.
Higher DTI accepted. Your debt-to-income (DTI) ratio gives lenders an understanding of other major financial obligations in your life. This ratio is a key factor in any loan application because it indicates your ability to afford a mortgage based on current household income and existing debt. Again, FHA loans offer more leniency here and borrowers at or below 43% DTI can qualify. Stricter property standards. To offset risk and further protect lenders, FHA loans have strict criteria when it comes to assessing the condition of any property being purchased with an FHA loan. The downside? The house you want to buy might not qualify for an FHA loan. The upside? You’re less likely to be financially burdened by a home that requires expensive repairs or updates.
No income limitations. It’s a common misconception that FHA loans are only available to first-time homebuyers or borrowers with limited income—but they’re not. There’s no maximum income limit that would disqualify you from this type of loan. Loan limits: FHA loan limits are typically lower than conventional loan limits, which means you might not be able to get funding for more expensive houses. This isn’t necessarily a bad thing, since it helps ensure that borrowers get loans they can afford to repay.

How to qualify for an FHA loan

Qualifying for an FHA loan is generally easier than qualifying for a conventional loan, but you’ll still need to meet some basic minimum standards set by the FHA. While the government insures these loans, the funding itself comes through FHA-approved lenders each lending institution may have slightly different qualifying guidelines for its borrowers. Keep in mind that, while these FHA standards offer a basic framework, you’ll need to confirm the individual qualifying rules with your specific lender.

  • Credit score minimum 500. Your exact credit score will play a big role in determining your down payment minimum; typically, the higher your credit score, the lower your down payment and the more favorable your interest rate.

  • Debt-to-income ratio at or below 56.9%. DTI is a standard way of comparing the amount of money you earn to the amount you spend paying off other debts, and FHA loans are more lax on this number.

  • Steady income and proof of employment. Being able to provide at least 2 years of income and employment records is a standard requirement for all loans.

  • Down payment between 3.5%-10%. The down payment minimum for an FHA loan is typically lower than conventional loan, and can be as little as 3.5% depending on your credit score and lender.

  • Property standards apply. You won’t qualify for an FHA loan if the house you want to buy doesn’t pass the appraisal process, which is more strict with this type of loan than conventional mortgages.

  • Maximum FHA loan amount. The amount of money you borrow cannot exceed the FHA loan limits; this number changes based on your county and is determined by how expensive the local market is; the maximum FHA loan limit in 2021 is $420,000 (check HUD resources to confirm the latest limits.)


Joel Lobb
Senior Loan Officer
(NMLS#57916)

American Mortgage Solutions, Inc.
10602 Timberwood Circle, Suite 3
Louisville, KY 40223

text or call my phone: (502) 905-3708
email me at kentuckyloan@gmail.com

The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency.

The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people. NMLS ID# 57916, (http://www.nmlsconsumeraccess.org). Mortgage loans only offered in Kentucky.
All loans and lines are subject to credit approval, verification, and collateral evaluation and are originated by lender. Products and interest rates are subject to change without notice.

Joel E Lobb
American Mortgage
5029053708
email us here
Kentucky FHA, VA, USDA & Rural Housing, KHC and Fannie Mae mortgage loans.

Kentucky Mortgage Broker Offering FHA, VA, USDA, Conventional, and KHC Down Payment Assistance Home Loans's avatarLouisville Kentucky Mortgage Loans

View original post