Credit scores required for A Kentucky Mortgage Loan Approval for FHA, VA, USDA and Conventional Fannie Mae

192199974_1008928599679889_572699217267405025_n
What credit score is needed to buy a house in Kentucky?

Ultimately, there is no singular credit score that can guarantee you a mortgage approval. Each lender is free to set their own credit score requirements.

But many loan types are insured by government organizations. And lenders cannot accept borrowers with credit scores below the minimum these organizations set. The four most popular home loan types are:

Conventional: Not backed by any government agency, but must meet the Fannie Mae and Freddie Mac underwriting guidelines
FHA: Loans backed by the Federal Housing Administration
VA: Loans backed by the US Department of Veterans Affairs (for military members)
USDA: Loans backed by the US Department of Agriculture (for low- to moderate-income families who buy homes in rural areas)

And here are the minimum credit score requirements for each of these loan types:

Conventional: 
620 SCORE NEEDED. BUT TO GET APPROVED FOR A FANNIE MAE LOAN MOSTLY LIKE YOU WILL NEED A 720 SCORE OR HIGHER IF YOU HAVE LESS THAN 20% EQUITY POSITION OR LESS THAN 20% DOWN PAYMENT DUE TO PRIVATE MORTGAGE INSURANCE
FHA: 
580 for a 3.5% down payment
500 for down payments of at least 10%
**MOST FHA LENDERS WILL WANT A 580 to 620  CREDIT SCORE NOWADAYS

VA: 
No minimum BUT MOST VA LENDERS WILL WANT A 580 to 620 CREDIT SCORE
USDA: 
No minimum, but with a credit score of at least 620 to 640 you could qualify for streamlined credit analysis and chances of approval goes way down if score is below 640…

unnamed-2020-09-27t195228.502

Joel Lobb
Senior  Loan Officer

(NMLS#57916)
 Fax:     (502) 327-9119
 
 Company ID #1364 | MB73346

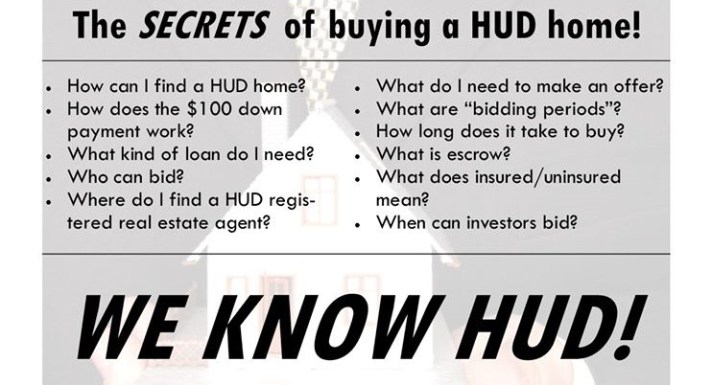
Kentucky HUD Homes for Sale with the FHA $100 Down Program

Buying A HUD Home in Kentucky $100 Down FHA loan

KENTUCKY HUD HOMES SALES INCENTIVES

For a limited time, FHA offers sales incentives on HUD homes that will make these homes more affordable for home buyers when purchasing a property using FHA-insured financing. The incentives VARY from State to State but may include low down payments; sales allowances that can be used to pay closing costs, make repairs, or pay down the mortgage amount; broker bonuses for owner-occupant sales. The benefits of FHA financing are low down payments; competitive interest rates; flexible credit qualifying. To find a HUD-Approved Lender, and for the latest sales incentives in your areas, visit HUDhomestore.com The program incentives are subject to change without prior notice.

Sales Incentives

(subject to change without prior notice)

Participating States

$100 Down Payment! Available to Owner Occupant Homebuyers when purchasing a property using FHA-insured financing.

Kentucky HUD Homes for Sale By FHA

Search Results for HUD Homes in KY

13 listings found
List Gallery
Save Search Email Search View Map Export to Display: 
5
10
20

Joel Lobb
Mortgage Loan Officer
Individual NMLS ID #57916

Text/call:      502-905-3708
fax:            502-327-9119
email:          kentuckyloan@gmail.com

https://www.mylouisvillekentuckymortgage.com/

Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. The content in this marketing advertisement has not been approved, reviewed, sponsored or endorsed by any department or government agency. Rates are subject to change and are subject to borrower(s) qualification.

How does Kentucky FHA Mortgage Rates work?

Kentucky FHA mortgage loans are backed by the Federal Housing Administration under the umbrella of HUD. FHA loans were developed to help borrowers that don’t have a large down payment and a weaker credit profile to buy and refinance their home mortgage loan.

​Kentucky FHA rates are backed by the government, so they are typically lower than other mortgage rates in the secondary market like Conventional loans and portfolio loans at banks, but fall in line compatible to other backed government loans in the secondary market likeUSDA, VA, mortgage loans. Most people seeking FHA mortgages will get a 30 year, 20 year of 15 year fixed rate loan with the security of the house payment not changing. ​

​Lower Credit Standards and Credit Scores for FHA loans

FHA mortgages will go down to a 500 credit score with at least 10% down payment, and if your credit score is higher than 580, you can put the minimum of 3.5% down payment. Additionally, you need to be only 2 years removed from a Chapter 7 bankruptcy, or 1 year from a Chapter 13 bankruptcy.

​Mortgage Insurance on FHA loans

Mortgage insurance is required on most FHA loans and is usually for life of loan with everyone paying the same. If you have a higher credit score and a larger down payment, it would make sense to look at doing a conventional mortgage loan because they are based on your credit score, money down, and debt to income ratio and not for life of loan.

You can get a lower FHA mortgage insurance premium and not have to finance the premiums for life of the loan if you put more than 10% down payment and finance on a 15 year term.

​Why would you consider a FHA mortgage?

​My best opinion is this. ​​​If you have a bankruptcy that is less than 4 years, have a credit score lower than 660, and very little money down, I would recommend at looking to do a FHA mortgage Loan. Your chances of getting approved with likely result in a loan approval as opposed to doing a conventional loan backed by Fannie Mae.

Why would you consider a Conventional Loan?

My best opinion is this. If you have a bankruptcy over 4 years or longer, at least 5% down payment, a credit score of 680 or higher, I would look doing a conventional mortgage loan.


Video: Kentucky FHA mortgage rates and loan options explained
▶ Click to watch on YouTube


​I can help you understand what mortgage is correct for you. Please contact me below and I will be happy to answer any questions.

Got questions about your Kentucky mortgage? Contact Joel Lobb
Joel Lobb (NMLS#57916)
Senior Loan Officer
American Mortgage Solutions, Inc.
10602 Timberwood Circle Suite 3
Louisville, KY 40223
Company ID #1364 | MB73346


Text/call 502-905-3708

kentuckyloan@gmail.com


If you are an individual with disabilities who needs accommodation, or you are having difficulty using our website to apply for a loan, please contact us at 502-905-3708.


Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines and are subject to change without notice based on applicant’s eligibility and market conditions. Refinancing an existing loan may result in total finance charges being higher over the life of a loan. Reduction in payments may reflect a longer loan term. Terms of any loan may be subject to payment of points and fees by the applicant Equal Opportunity Lender. NMLS#57916http://www.nmlsconsumeraccess.org/

How to Ditch FHA Mortgage Insurance Premiums

Originally Posted On: https://thelindleyteam.com/how-to-ditch-fha-mortgage-insurance-premiums/ When you get a mortgage, you’re signing a million sheets of paper and agreeing to pay a lot…

Source: How to Ditch FHA Mortgage Insurance Premiums


When you get a mortgage, you’re signing a million sheets of paper and agreeing to pay a lot of things that you may not understand at the time. Closing costs, down payments, inspections, real estate agent fees, home insurance, escrow, and so on and so forth. One of the numbers that may have gotten rolled into that list is mortgage insurance premiums.

If you got an FHA loan, you’re almost certainly paying FHA mortgage insurance premiums. Read on to learn more about what these are, how much you might be paying each month, and how you can get out from under them.

What Are FHA Mortgage Insurance Premiums?

Before the Federal Housing Administration was founded, in order to qualify to buy a house, mortgage applicants had to have excellent credit and a large down payment. This made it harder for people to buy homes, so the FHA was established to make this process easier for first-time homebuyers. The FHA does not actually give loans they just insure them.

Mortgage insurance is a policy that protects your lender in case you default on your loan. It allows lenders to make higher-risk loans without worrying about losing money. You pay the premiums for that insurance policy as a part of your agreement with the loan.

Mortgage Insurance Rates

If your loan was $625,000 or less and you got a thirty-year fixed-rate mortgage and you paid less than 5 percent on a down payment, you’ll have an annual mortgage insurance premium of 0.85 percent of your loan. If you put down more than 5 but less than 10 percent, you’ll pay 0.8 percent for the life of the loan. If you put down more than 10 percent, you’ll pay 0.8 percent for the first eleven years of the loan

For loans less than $625,000 with a fifteen-year fixed-rate note where you paid less than 10 percent down, you’ll pay 0.7 percent of your loan amount every year for the life of the loan. If you paid more than 10 percent, you’ll pay 0.45 percent every year for the first eleven years.

If you have a mortgage greater than $625,000 with a thirty-year fixed-rate loan and you paid less than 10 percent down, you’ll pay 1 percent of your mortgage every year for the life of the loan. If you paid more than 10 percent down, you’ll pay a slightly higher 1.05 percent, but only for the first eleven years.

And finally, if your loan is greater than $625,000, you have a 15-year fixed-rate mortgage, and you paid less than ten percent down, you’ll pay 0.95 percent of your loan every year for the life of the loan. If you paid more than 10 percent but less than 22 percent, you’ll pay 0.7 percent for the first eleven years of the loan. And if you paid more than 22 percent, you’ll pay 0.45 percent every year for the first eleven years.

How to Get Out of Mortgage Insurance

The good news is that you aren’t stuck forever. Once you get about 20 percent equity in your house, either through improvements or paying down the loan, you can refinance your mortgage. With that 20 percent, you should be able to get a mortgage that doesn’t require FHA protection.

Even if you don’t yet have 20 percent equity in the house, you may be able to refinance into a lower mortgage insurance premium bracket. If you can get 10 percent to put down on your new mortgage, for instance, you may be able to drop to a lower monthly percentage that you’re paying.

Reappraise

Depending on where you live and what work you’ve done on the house, you may be able to get 20 percent equity without having to pay all that money in. If property values in your area are on the rise, your home may be worth more now than when you bought it. The same goes for home improvements, and that total may leave you with more than 20 percent equity in your home so you can refinance out of your mortgage insurance.

A great way to determine if this is the case for you is to have your home appraised again. A home appraisal will cost somewhere between $300 and $400. If you’re paying $520 a month for mortgage insurance premiums (1 percent on a $625,000 loan), this will pay for itself immediately.

How to Refinance

Once you get 20 percent equity in your house, no matter how you do it, you can refinance into a new mortgage. Start by shopping around and applying for a new mortgage with three or four lenders. This will give you an idea of what sort of interest rates you’re looking at and what your new monthly payment should be.

Once you find a lender you like, lock in your interest rate and start on the process of getting the loan closed. You’ll need a fair amount of paperwork for both the application and closing processes. Your last several pay stubs, tax returns, credit reports, and statements of your assets and outstanding debts are a good place to start.

Kentucky FHA Loan Requirements For Loan Approval.

images (3)


FHA Handbook 4000.1 Updates

Administration (FHA) Single Family Housing Policy Handbook 4000.1. These updates are effective September 30, 2016 and

 Clarification that an Upfront Mortgage Insurance Premium (UFMIP) refund calculation applies even if original UFMIP was
not financed.
 Mortgage Debt Not Included in Credit Report: Clarification that a manual downgrade is not required when there is no history of late payments, as detailed below.
o Not currently delinquent; and
o No 30 day late payments within 12 months of the case number assignment date; and
o No more than 2 x 30 day late payments within 24 months of the case number assignment date.
 A link has been added in the FHA Product Description from Mortgage Payment History requirements to “Credit History
Requirements for Manually Underwritten Loans.”
Appliances that add contributory value must be operable.
 Mechanical components and utilities: The appraiser must report the utility, safety, and capacity of the mechanical systems.
The appraiser must observe and operate all applicable mechanical systems and utilities. In conjunction with this guidance,
existing FHA Handbook guidance on the following topics will be added:
o Electrical System
o Heating and Cooling
o Plumbing
o Utilities

If you have questions about qualifying as first time home buyer in Kentucky, please call, text, email or fill out free prequalification below for your next mortgage loan pre-approval.


The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only.  The posted information does not guarantee approval, nor does it comprise full underwriting guidelines.  This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the views of my employer. Not all products or services mentioned on this site may fit all people