Income limits apply, and the property must be in an eligible rural area.
The good news? USDA loans are currently open — no shutdown.
Getting pre-approved is free and there’s no obligation.
If you want to see if you qualify, let’s get started.
Louisville Kentucky FHA Mortgage Loans for Purchases and Refinance
click here to Call/Text: 502-905-3708 with questionsWhat’s a debt-to-income ratio, and why you need a low one to buy a home
In “First Time Home Buyer Loans–Kentucky”https://kentuckyfhaloan.com/wp-content/uploads/2021/01/image.png?w=863

This article is too good not to be shared so it’s copied from The Washington Post.
When it comes to qualifying for a loan to buy a home or to refinance your mortgage, there are plenty of numbers to consider, such as your credit score and the appraised home value. Perhaps one of the most important numbers is your debt-to-income (DTI) ratio, which compares the minimum payments on all debt you must make each month with your gross monthly income.
“The DTI ratio is one of the most important considerations lenders take into account when evaluating the risk associated with a borrower taking on another payment,” says Paul Buege, president and chief operating officer of Inlanta Mortgage in Pewaukee, Wis. “The lower the DTI ratio a borrower has, the more confident the lender is about getting paid on time in the future based on the loan terms.”
It’s not just…
View original post 450 more words
Are you a Kentucky homebuyers looking for information on mobile home loans? Manufactured homes are an affordable option for many buyers. With flexible financing options like Kentucky FHA, VA, USDA, and Conventional loans, achieving homeownership in Kentucky is easier than ever. This guide provides the guidelines for each loan program. It also explains how you can qualify for a free mortgage loan approval for your mobile home in Kentucky.
Manufactured homes offer affordable housing solutions, but the financing process requires specific guidelines. Here’s a breakdown of the major loan programs for mobile home loans in Kentucky, their qualifications, and how they work.
The FHA Loan Program is one of the most popular options for manufactured homes in Kentucky. This program requires a low credit score and offers competitive terms. It is ideal for first-time buyers or those with less-than-perfect credit.
If you are a veteran or active-duty service member, consider the VA Loan Program. It is an excellent option for financing a mobile home. This program offers 100% financing with no down payment required.
The USDA Loan Program provides 100% financing for manufactured homes in eligible rural areas of Kentucky. This loan is ideal for homebuyers looking for affordable financing with no down payment.
The Conventional Loan Program is another option for financing manufactured homes in Kentucky. It offers competitive terms for buyers with stronger credit profiles.
If you’re a Kentucky homebuyer looking to finance a mobile home, understanding the different loan options and guidelines is essential. Below, we break down the requirements for FHA loans. We also cover the requirements for VA, USDA, and Conventional loans. This information will help you secure a mobile home loan in Kentucky. Learn how you can qualify for a free mortgage loan pre-approval today!
| Loan Program | Credit Score Requirement | Eligible Property Types | Loan-to-Value (LTV) | Key Guidelines | Additional Notes |
|---|---|---|---|---|---|
| FHA Loan | 500 minimum FICO score | Singlewide, Doublewide, Triplewide homes | Purchase/Rate-Term up to 96.5% LTV Cash-Out up to 80% LTV | – Manual underwriting allowed – Real Property Conversion allowed at closing – Primary residence only – Exempt from ATR Points/Fees Test | – No prior installation/occupancy at another site – No pricing adjuster for mobile homes – Home must be constructed after June 15, 1976 |
| VA Loan | 500 minimum FICO score | Singlewide, Doublewide, Triplewide homes | Purchase/Rate-Term up to 100% LTV Cash-Out up to 90% LTV | – Manual underwriting allowed – Real Property Conversion allowed at closing – Primary residence only – Exempt from ATR Points/Fees Test | – No prior installation/occupancy at another site – No pricing adjuster for mobile homes – Home must be constructed after June 15, 1976 |
| USDA Loan | 581 minimum FICO score | Singlewide, Doublewide, Triplewide homes | Purchase up to 100% LTV | – Manual underwriting required (Max DTI: 29/41) – Home must be a 2006 model or newer – Located in USDA-eligible rural areas – Primary residence only | – No prior installation/occupancy at another site – No pricing adjuster for mobile homes – RD Program available in specific states, including Kentucky |
| Conventional Loan | 620 minimum FICO score | Singlewide, Doublewide, Triplewide homes | Purchase/Rate-Term up to 95% LTV Cash-Out up to 65% LTV | – Real Property Conversion allowed at closing – Primary and second homes allowed – Cash-Out not allowed on Singlewide homes | – No prior installation/occupancy at another site – Small 50 pricing adjuster for mobile homes – Home must be constructed after June 15, 1976 |
Mobile homes, also known as manufactured homes, offer an affordable housing solution for Kentucky residents. Whether you’re a first-time homebuyer or looking to refinance your property, government-backed loans can help. Conventional options also provide flexible terms. These options make homeownership a reality.
Ready to take the next step? As a Kentucky homebuyer, you can benefit from free mortgage loan pre-approval for your mobile home loan. You might be interested in an FHA, VA, USDA, or Conventional loan. Our experts will guide you through the process. They will find the best option for your needs.
Manufactured homes in Kentucky offer affordability, flexibility, and modern designs. Whether you’re a first-time homebuyer or someone looking to refinance your current mobile home, these loan programs provide tailored solutions. They meet your needs. With low credit score requirements and flexible terms, financing your manufactured home is within reach.
Ready to take the next step? Get a free mortgage pre-approval for your mobile home loan in Kentucky today. We offer expert guidance on FHA, VA, USDA, and Conventional loan programs. We’ll help you find the best financing option for your needs.
Contact us now to get started on your journey to owning a manufactured home in Kentucky. Call or apply online for your free pre-qualification and same-day approval!
Email – kentuckyloan@gmail.com
Call/Text – 502-905-3708
Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans
Website: www.mylouisvillekentuckymortgage.com
Address: 10602 Timberwood Cir, Ste 3, Louisville, KY 40223
Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916
For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.

FHA loan in Kentucky you will be confronted with minimum credit score requirements set forth by FHA and the lender. Even though FHA will insure the mortgage loan at a certain credit score, you will see that lenders will create “credit-overlays” to protect their risk and ask for a higher credit score.
So keep in mind when you are getting an FHA lenders will have higher credit score minimums in addition to the FHA Mortgage Insurance program.
For a Kentucky Homebuyer wanting to purchase a home or refinance their existing FHA loan, FHA requires a 3.5% down payment and the borrower must have a 580 FICO Credit Score. If the score is below 580, then you would need 10% down and still qualify on a manual underwrite.
You must have a FICO score of at least 500 to be eligible for a Kentucky FHA loan. If your FICO score is from 500 to 579, your down payment on the loan is 10 percent of the loan.
If your FICO score is 580 or higher, your down payment is only 3.5 percent. If your credit score is less than 580, it may be more cost-effective to take the necessary steps to improve your score before taking out the loan, rather than putting the money into a larger down payment.
How do they get the credit score: There are three main credit bureaus in the US. Equifax, Experian, and Transunion. The three scores vary but should be relatively close as long as the same creditors are reporting to the same bureaus.
You will get a variation in the scores due to all creditors or collection companies don’t report to all three bureaus. This is why they take the mid score. So if you have a 590 Experian, 680 Equifax, and 620 TransUnion, your qualifying credit score would be 620
Based on my experience with lenders that I deal with in Kentucky on FHA loans, most lenders require 620 middle credit score for consideration for loan approval.
How do they get the score: They take the mid score, so if you have a 590 Experian, 680 Equifax, and 620 TransUnion, your qualifying score would be 620.

▶ Click to watch on YouTube
If your score is below 620, a manual underwrite is where the AUS (Automated Underwriting System) refers your loan to a human being, and they look at the entire file to see if they can overturn and approve the mortgage loan because the Desktop Underwriting Automated Software could not approve you.
With scores below 620, they typically will want to verify your rent history, have no bankruptcies in the last two years, and no foreclosures in the last 3 years.
If you have had any lates since the bankruptcy this will probably result in a denial on a refer manual underwrite file.
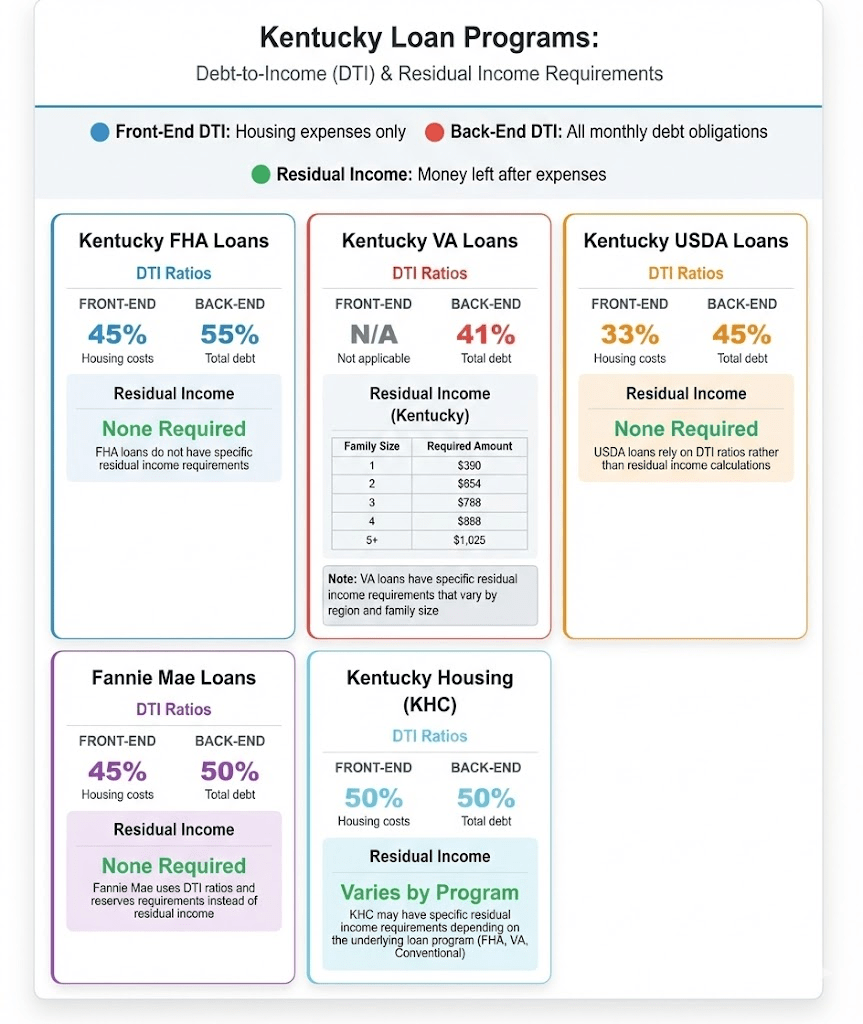
Your max house payment will be set at 31% of your gross monthly income, and your new house payment plus the bills you are paying on the credit report cannot be more than 43%.
Typically, on scores below 620 for FHA loans, they will also look at reserves or money you have saved up after the loan is made to try and qualify you. For example, if you have a 401k or savings account that has at least 4 months reserves (take your mortgage payment x 4) and this would equal your reserves. They look at this as a rainy day fund and could help you keep up on your bills if you were unemployed or could not work.

▶ Click to watch on YouTube
The first thing to keep in mind is that qualifying for a mortgage involves a lot more than just a credit score. While your FICO score is a very important ingredient, it is just one factor. Lenders also look at your income and level of debt, among other things.
As a rule of thumb, however, a credit score below 620 will make buying a home very difficult. A FICO score below 620 is considered sub-prime. In the past, there were mortgage companies that specialized in sub-prime mortgages. Because of the challenges in the credit market over the last year or so, however, sub-prime loans have become difficult if not impossible to obtain.
A FICO score between 600 and 640 is considered fair to good credit. But keep in mind, this range of credit scores does not guarantee you will qualify for a mortgage, and if you do qualify, it won’t get you the lowest interest rate possible. Still, to buy a home aim for a score of at least 620, recognizing that other factors weigh in the decision and that some banks may require a higher score.
What credit score do you need to get a low rate mortgage?
It uses to be that a score of about 720 would yield the lowest mortgage rates available. Today, the best rates kick in with a FICO score of 760. And interest rates go up significantly as your credit score drops. To give you an idea, the following table shows current rates by credit score and calculates a monthly principal and interest payment based on a $300,000 loan:

▶ Click to watch on YouTube
By paying down your credit card balances (credit utilization) and having a good pay history (payment history) ,this is the best way to raise your score.
The credit bureaus don’t update immediately, so I would not add to the balance or open any new bills or have any other lender do an inquiry on your credit report while we wait for the scores to hopefully go up in the next 30 days. Try to keep everything status quo and make your payments on time and keep your balances low or lower than what is now reporting on the credit report.
How to improve your credit score!
Please understand one thing; paying your bills on time each month is the single most important thing you can do to increase your credit scores.
Depending on the credit bureau, there are 4 or 5 main items that determine everyone’s credit score. Of those items, your history of paying bills makes up about 35% of the score. THIS IS HUGE!
Paying your bills on time shows lenders that you are responsible. It will also spare you from paying late fees whether it is a charge from a credit card or an added fee from your landlord.
Use a calendar, or a phone app, or some other organized system to make sure that you pay your bills on time every single month.
MAIN TIP: Do not pay ANY bill late!
First, they look at your available credit limit. Second, they look at the existing balance on each card. From these two figures an available ratio is developed. As the ratio goes higher, so too will your credit score increase.
Here is one simple example. Suppose a person has the following credit cards, corresponding balances, and credit limits
| Credit Card | Current Balance | Credit Limit |
| Chase Visa | $105 | $1,000 |
| MarterCard from local bank | $236 | $1,500 |
| BP MasterCard | $87 | $500 |
| Totals | $428 | $3,000 |
From these numbers, we get the following calculation
$428/$3,000 = 14%
In other words, the person is using 14% of their available credit and they have 86% available credit. The closer that ratio is to 100%, the better the credit score will be.
MAIN TIP: Keep all credit card balances as low as possible.In this particular example, if they had a problem with their car, or needed medical attention or some other emergency, the person would have the money necessary to handle the situation without incurring new debt. This is wise on the consumer’s part and lenders like to see this kind of money management.
The previous example showed a person that utilized just three credit cards. This is much better than someone who has 5+ credit cards, all with available balances. Why? Lenders do not like to see someone that has the potential to get too far in debt in a short amount of time.
Some people have 5, 10 or more credit cards and they use many of them. This shows a lack of restraint and control. It is much better, and neater, to have only 2 or 3 cards with low rates that handle all of your transactions. A lower number of cards are easier to manage and it does not give a person the temptation to go on a huge shopping spree that could take years to payoff.
MAIN TIP: Try to limit yourself to no more than 2-3 credit cards.
Too many people make the mistake of paying off old debts, such as old credit cards, and then closing the account. This is actually a bad idea.
A small part of the credit score is based on the length of time a person has had credit. If you have a couple of credit cards with a long track history of making payments on time and keeping the balance at a manageable level, it is a bad idea to close out the card.
Similarly, if you have been paying on a car or motorcycle for a long time, do not be in a hurry to pay off the balance. Continue to make the payments like clockwork each month.
An account that has a good record will help your scores. An account that has a good record and multiple years of use will have an even better impact on your score.
MAIN TIP: Keep old accounts open if you have a good payment history with them.
Multiple credit inquiries in a short amount of time can really hurt your credit scores. Lenders view the various inquiries as someone that is desperate and possibly on the verge of making a bad financial choice.Too many people make the mistake of getting more credit after they are approved for a loan. For example, if someone is approved for a new credit card, they feel good about their finances and decide to apply for credit with a local furniture store. If they get approved for the new furniture, they may decide to upgrade their car. This requires yet another loan. They are surprised to learn that their credit score has dropped and the interest rate on the new car loan will be much higher. What happened?
If you currently have 2 or 3 credit cards along with either a car loan or a student loan, don’t apply for any more debt. Make sure the payments on your current debt are all up to date and focus on paying them all down.
In a few months of making timely payments your scores should noticeably go up.
MAIN TIP: Limit your new loans as much as possible
Which credit scores do mortgage lenders use to qualify people for a mortgage?
While it’s common knowledge that mortgage lenders use FICO scores, most people with a credit history have three FICO scores, one from each of the three national credit bureaus (Experian, Equifax, and TransUnion).
Most lenders determine a borrower’s creditworthiness based on FICO® scores, a Credit Score developed by Fair Isaac Corporation (FICO™). This score tells the lender what type of credit risk you are and what your interest rate should be to reflect that risk. FICO scores have different names at each of the three major United States credit reporting companies. And there are different versions of the FICO formula. Here are the specific versions of the FICO formula used by mortgage lenders:
Lenders have identified a strong correlation between Mortgage performance and FICO Bureau scores (FICO score). FICO scores range from 300 to 850. The lower the FICO score, the greater the risk of default.
Since most people have three FICO scores, one from each credit bureau, how do lenders choose which one to use?
For a FICO score to be considered “usable”, it must be based on adequate, concrete information. If there is too little information, or if the information is inaccurate, the FICO score may be deemed unusable for the mortgage underwriting process. Once the underwriter has determined if a score is usable or not, here’s how they decide which score(s) to use for an individual borrower:
Lenders have identified a strong correlation between Mortgage performance and FICO Bureau scores (FICO score). FICO scores range from 300 to 850. The lower the FICO score, the greater the risk of default.
If it helps to visualize this information:
| Identifying the Underwriting Score | ||||
|---|---|---|---|---|
| Example | Score 1 | Score 2 | Score 3 | Underwriting Score |
| Borrower 1 | 680 | 700 | 720 | 700 |
Joel Lobb
Mortgage Loan Officer
Individual NMLS ID #57916
email: kentuckyloan@gmail.com
email me at kentuckyloan@gmail.com
The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people. NMLS ID# 57916, (www.nmlsconsumeraccess.org). USDA Mortgage loans only offered in Kentucky.
All loans and lines are subject to credit approval, verification, and collateral evaluation
Buying your first home in Kentucky in 2026? You’re entering a market with more options than ever before. Updated loan limits, competitive interest rates, and powerful down payment assistance programs are making homeownership more accessible for Kentucky families across all 120 counties.
The main options for Kentucky homebuyers in 2026 include Conventional Loans, FHA Loans, VA Loans, USDA Loans, and Kentucky Housing Corporation (KHC) Down Payment Assistance programs. Each offers distinct advantages depending on your credit score, down payment savings, income level, and location.
This comprehensive guide breaks down every program, updated with 2026 loan limits, credit requirements, and qualification guidelines to help you make informed decisions about your home purchase.
Conventional loans remain the most popular choice for Kentucky homebuyers with good credit and stable income. These loans are not government-backed, which means they follow stricter underwriting standards but offer significant benefits for qualified borrowers.
Why Choose Conventional? Borrowers with credit scores of 740+ and 20% down payments often prefer conventional loans because they can avoid mortgage insurance entirely and typically secure the lowest interest rates available.
FHA loans are designed specifically for first-time homebuyers and those with lower credit scores or limited savings. Backed by the Federal Housing Administration, these loans offer the most flexible qualification guidelines of any mortgage program.
Same as conventional loans, plus:
Why Choose FHA? Perfect for first-time buyers rebuilding credit, those with limited savings, or anyone who has experienced past financial challenges. FHA loans are more forgiving and accessible than conventional financing.
VA loans provide unmatched benefits for eligible veterans, active-duty service members, National Guard members, Reservists, and qualifying surviving spouses. These loans eliminate major barriers to homeownership.
Why Choose VA? The combination of no down payment, no monthly mortgage insurance, and competitive interest rates makes VA loans the most powerful financing option available for eligible borrowers.
USDA loans offer 100% financing for eligible rural and suburban properties throughout Kentucky. Despite the “rural” designation, many suburban areas qualify, including parts of major metro areas.
Why Choose USDA? Perfect for buyers purchasing in eligible rural or suburban areas who want 100% financing. Many Kentucky locations qualify, including areas near Louisville, Lexington, and other cities.
The Kentucky Housing Corporation offers the most comprehensive suite of programs for first-time homebuyers in the state, combining competitive interest rates with substantial down payment assistance.
1. Conventional Preferred Program
2. Conventional Preferred Plus 80 Program
3. Mortgage Revenue Bond (MRB) Program
Income limits vary by county and household size. Here are representative examples:
Why Choose KHC? The combination of below-market interest rates and up to $12,500 in down payment assistance can save Kentucky homebuyers thousands of dollars over the life of their loan.
The Kentucky Welcome Home Grant is expected to return in March 2026, offering additional down payment assistance to eligible Kentucky homebuyers.
Important: The Welcome Home Grant consistently sells out within days of opening. Get pre-approved now and be ready to act immediately when the program launches.
| Program | Min. Credit Score | Down Payment | Max DTI | 2026 Loan Limit (1-Unit) |
|---|---|---|---|---|
| Conventional | 620 | 3-5% | 43-50% | $832,750 |
| FHA | 580 | 3.5% | 31/43-57% | $541,287 |
| VA | 580-620 | 0% | No max* | $832,750 (or unlimited) |
| USDA | 620 | 0% | 29/41-45% | Based on income limits |
| KHC Programs | Varies | 3-3.5% | Varies by loan type | $544,232 |
*VA loans evaluate residual income rather than strict DTI limits
Q: Can I combine KHC down payment assistance with FHA or VA loans?
A: Yes! KHC assistance can be layered with FHA, VA, USDA, or Conventional loans, making it possible to buy with minimal out-of-pocket costs.
Q: What’s the difference between the Welcome Home Grant and KHC down payment assistance?
A: The Welcome Home Grant is a forgivable grant (not repaid), while KHC down payment assistance is a second mortgage with monthly payments at 3.75% interest.
Q: Do all Kentucky counties have the same FHA loan limits?
A: Yes. For 2026, all 120 Kentucky counties use the same FHA floor limit of $541,287 for single-family homes.
Q: Can I buy a multi-unit property with these programs?
A: Yes! FHA, VA, and Conventional loans all allow 2-4 unit purchases, with the requirement that you occupy one unit as your primary residence.
Q: How long does the mortgage approval process take?
A: Pre-approval typically happens within 24 hours. Full approval to closing typically takes 30-45 days depending on the loan type and your responsiveness.
Q: What if I have student loan debt?
A: All programs allow student loan debt. Lenders will calculate either 0.5-1% of the balance or use your actual payment amount in DTI calculations.
Navigating multiple loan programs, down payment assistance options, and changing requirements requires expertise and local knowledge. Working with a Kentucky-licensed mortgage professional who specializes in first-time homebuyer programs ensures:
Ready to explore your Kentucky home buying options? The 2026 loan limits and programs provide more opportunities than ever for Kentucky families to achieve homeownership.
📧 Email: kentuckyloan@gmail.com
📞 Call/Text: 502-905-3708
🌐 Website: www.mylouisvillekentuckymortgage.com
Joel Lobb
Mortgage Loan Officer – Kentucky Mortgage Loan Specialist
20+ Years Experience | 1,300+ Families Helped
NMLS Personal ID: 57916
Company NMLS ID: 1738461
Equal Housing Lender | Licensed for Kentucky Mortgage Loans Only
Disclaimer: This website is not endorsed by or affiliated with the FHA, VA, USDA, or any government agency. Information provided is for educational purposes. Loan programs, rates, and requirements subject to change. All borrowers must meet program eligibility requirements.
Kentucky’s housing market continues to show strength in 2026, with steady home price appreciation and competitive interest rates creating favorable conditions for buyers. The increased loan limits provide greater purchasing power, while expanded down payment assistance programs make homeownership more accessible.
Whether you’re a first-time buyer, a veteran, or someone looking to purchase in a rural area, Kentucky’s diverse loan programs offer a pathway to homeownership that fits your unique financial situation.
Start your journey today by