Top Mortgage Lenders in Kentucky | Joel Lobb

Best Mortgage Lenders in Kentucky with Joel Lobb

Are you a prospective homebuyer in Kentucky searching for the best mortgage lenders? Joel Lobb is a trusted mortgage broker. He has a proven track record of helping clients secure competitive mortgage rates. He also helps clients with financing options. With Joel Lobb by your side, you can access top-notch mortgage lenders in Kentucky. He will help you make your dream of homeownership a reality.

Joel Lobb has established strong relationships with a network of reputable mortgage lenders in Kentucky. These lenders offer a wide range of loan programs. These programs can suit your unique needs and financial goals. Whether you’re a first-time homebuyer, a seasoned investor, or looking to refinance your existing mortgage, Joel Lobb can connect you with the best mortgage lenders that offer:

  1. Competitive Interest Rates: Access mortgage loans with competitive interest rates. These rates can save you money over the life of your loan.
  2. Flexible Loan Programs: Choose from a variety of loan programs. These include FHA, VA, USDA, conventional, jumbo loans, and more. They are tailored to your specific requirements.
  3. Personalized Guidance: Receive personalized guidance and support throughout the mortgage process. This includes steps from pre-qualification to closing. These efforts ensure a smooth and stress-free experience.
  4. Quick and Efficient Approval: Benefit from efficient loan processing. Experience quick approval times, allowing you to close on your new home faster.
  5. Transparent and Honest Service: Experience transparent and honest communication throughout your mortgage journey. We provide full transparency on loan terms, fees, and requirements.

When you are looking for the best mortgage lenders in Kentucky, Joel Lobb stands out. He is a trusted advisor and advocate for his clients’ best interests. With Joel Lobb’s expertise and industry knowledge, you can navigate the complex world of mortgage lending with confidence. You can achieve your homeownership goals.

Contact Joel Lobb today. Learn more about the best mortgage lenders in Kentucky. Start your journey towards owning the perfect home for you and your family.

Joel Lobb  Mortgage Loan Officer

Text/call: 502-905-3708

email:
 kentuckyloan@gmail.com

http://www.mylouisvillekentuckymortgage.com/

📞 Call/Text: 502-905-3708
📧 Email: kentuckyloan@gmail.com
🌐 Website: www.mylouisvillekentuckymortgage.com
🏠 Address: 10602 Timberwood Cir, Ste 3, Louisville, KY 40223
NMLS #57916 | Company NMLS #1738461
➡️Click here to apply for Free Info & Homebuyer Advice →
Kentucky Mortgage Loan Expert
FHA | VA | USDA | KHC Down Payment Assistance | Fannie Mae
Equal Housing Lender. This is not a commitment to lend. All loans are subject to credit approval and program requirements.


Kentucky USDA Loans | Rural Housing Loans Kentucky


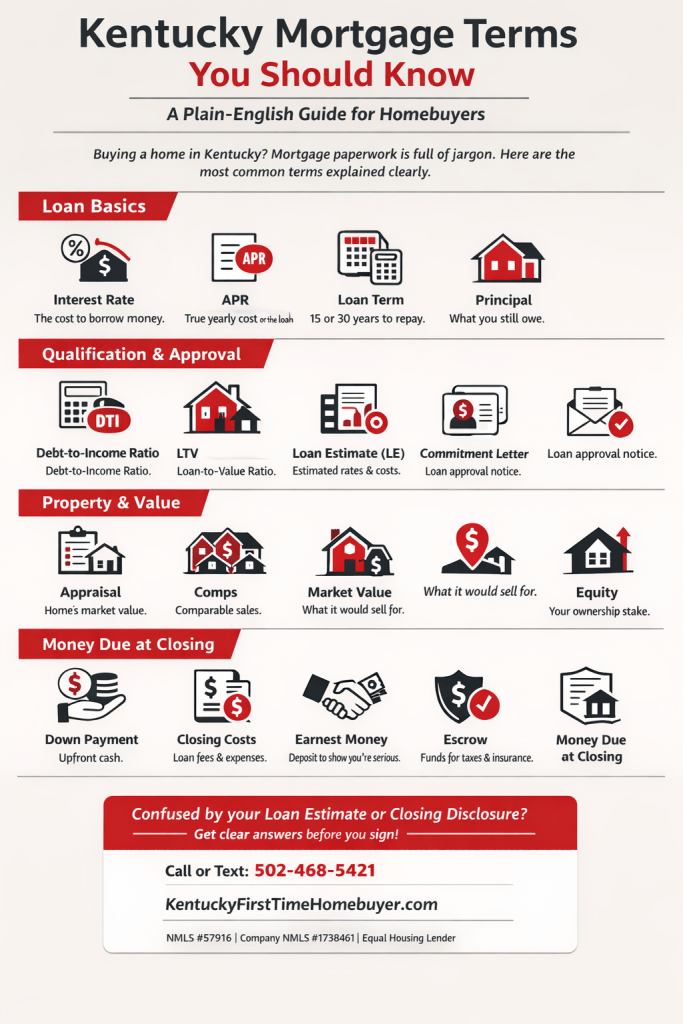
Essential Mortgage Terms Every Kentucky Homebuyer Should Know

Kentucky Mortgage Broker Offering FHA, VA, USDA, Conventional, and KHC Down Payment Assistance Home Loans's avatarKentucky First-Time Home Buyer Programs | USDA, FHA, VA & KHC Loans

Glossary of Mortgage Terms to Know For A Kentucky Mortgage Loan.

ACCRUED INTEREST: Accumulated interest since the principal investment that has
not yet been paid.
AMORTIZATION: Paying off debt, principal and interest, with a fixed repayment schedule
in regular installments over a fixed period of time.
ANNUAL PERCENTAGE RATE (APR): The annual rate charged for borrowing money
expressed as a percentage. APR takes into account interest, discount points, lender fees
and mortgage insurance.
APPLICATION FEE: A fee charged by a lender to cover the initial costs of processing a
loan application.
APPRAISAL: A written estimate of a property’s current market value, based on the current
condition of the property and recent sales information from similar properties in the same
area.
APPRAISAL FEE: The cost to have a licensed, certified appraiser estimate the market value
of a property as of a specific date.
BORROWER: An individual who receives a loan from…

View original post 827 more words

Kentucky FHA Mortgage Loans with Private Flood Insurance

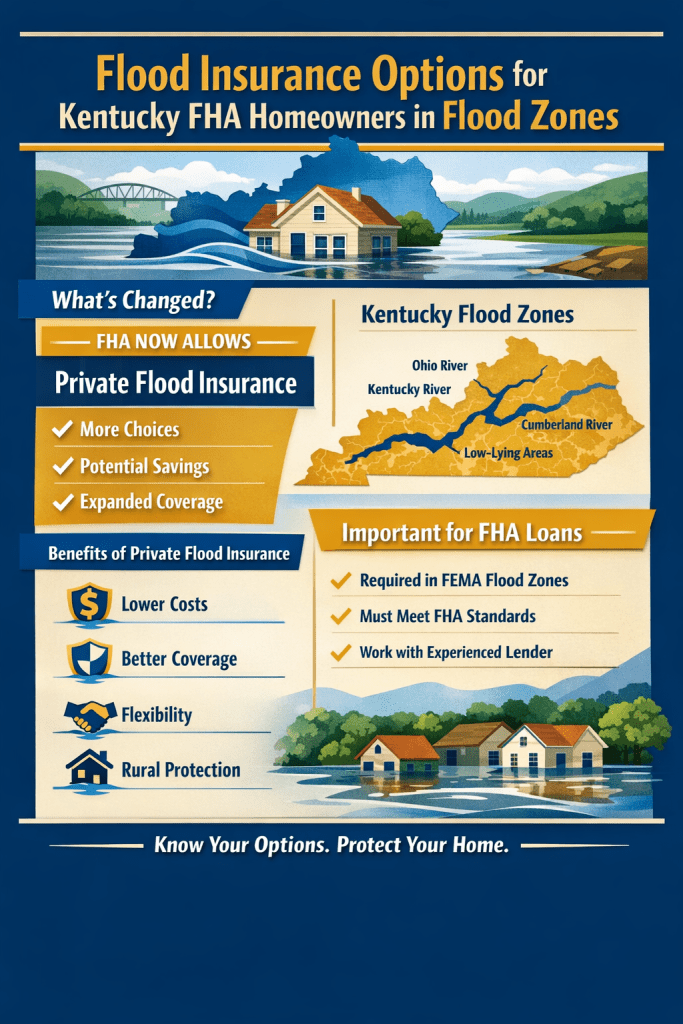
HUD INCREASES FLOOD INSURANCE OPTIONS FOR KENTUCKY HOMEOWNERS WITH KENTUKY FHA MORTGAGES LIVING IN FLOOD AREAS

Federal Housing Administration to allow private flood insurance policies on insured single-family mortgages in special flood hazard areas

WASHINGTON – The U.S. Department of Housing and Urban Development (HUD), through the Federal Housing Administration (FHA), is announcing today that effective December 21, 2022, it will allow homeowners with FHA-insured mortgage financing to obtain flood insurance policies that conform to FHA requirements from private insurance providers. The change was announced through a final rule published in the Federal Register today and in a companion Mortgagee Letter, also published today, that provides implementation guidance for FHA-approved lenders.

FHA requires that insured mortgages for properties in Federal Emergency Management Agency (FEMA)-designated Special Flood Hazard Areas (SFHAs) have flood insurance. Previously, only flood insurance obtained through the National Flood Insurance Program (NFIP) was permissible for FHA-insured mortgages, which limited choices for consumers.

“Today, HUD is increasing the flood insurance choices available to individuals and families with FHA-insured loans in areas that FEMA has designated to be at special risk for flooding,” said HUD Secretary Marcia L. Fudge. “Flood insurance is required to ensure families and individuals are prepared if disaster strikes. Increasing consumer options for this important protection is one way we are building more resilient communities in the face of climate change.”

“We know borrowers face affordability challenges right now, yet a flood can be devastating to a family who is not properly insured,” said Federal Housing Commissioner Julia Gordon. “The choice to select a private flood insurance option may enable some borrowers to obtain policies that are less expensive or provide enhanced coverage.”

As part of its implementation, as of December 21, 2022, FHA will require lenders to provide detailed flood insurance coverage information when electronically submitting mortgages for FHA insurance on properties in SFHAs. This data collection is an objective included in HUD’s Climate Action Plan and will allow FHA to capture and analyze flood insurance information on mortgages in its portfolio at a more granular level than has been possible previously.

Ensuring that borrowers are protected against flood risk is a key component of HUD’s Climate Action Plan. In 2021, HUD released its Climate Action Plan in response to President Biden’s Executive Order on Tackling the Climate Crisis at Home and Abroad. HUD has been implementing this broad approach to the climate crisis that reduces climate pollution; increases resilience to the impacts of climate change; protects public health; delivers environmental justice; and spurs well-paying union jobs and economic growth. The action today further guides the integration of climate resilience and environmental justice into HUD’s core programs and policies. For more information about HUD’s work to advance sustainable communities and address climate change, visit hud.gov/climate.

#fha #fhaloans #fhaloan #floodinsurance #mortgage #homeloan #homebuying #homebuyingtips

First-time home buyers in Kentucky Joel Lobb

Joel Lobb specializes in a wide array of mortgage loans, including:
– **FHA Loans**: These loans are a great fit for buyers with lower credit scores or those who can afford only a minimal down payment.
– **VA Loans**: Tailored for veterans and active military members, offering favorable terms with little to no down payment.
– **USDA Loans**: Designed for rural home buyers, providing 100% financing options.
– **KHC Loans**: In collaboration with the Kentucky Housing Corporation, these loans come with down payment assistance, making them ideal for first-time buyers.

Complete Guide to FHA Loan Requirements in Kentucky

FHA loans are a popular choice for many first-time homebuyers in Kentucky. This is due to their flexible qualifying criteria. If you’re considering an FHA loan in the Bluegrass State, understanding the key qualifying factors is crucial. Here’s a comprehensive guide to the criteria you need to know:

  1. Credit Score Requirements:
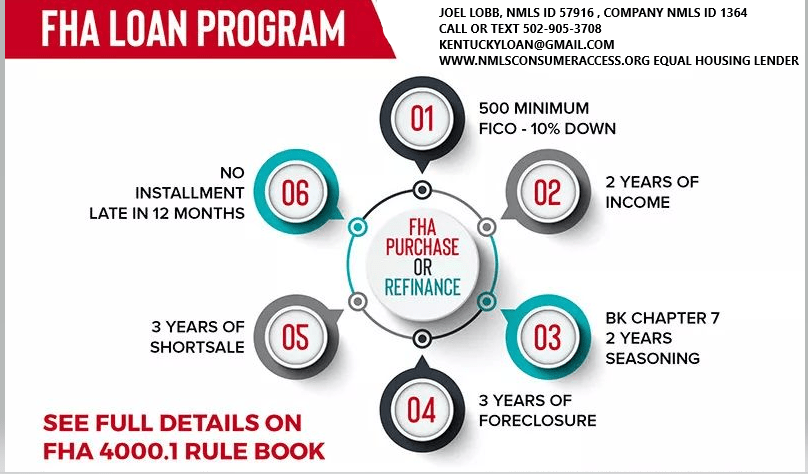
    • FHA loans are known for accommodating borrowers with lower credit scores. The minimum required credit score can vary. Typically, a credit score of 580 or higher is needed to qualify for the minimum down payment of 3.5%. Borrowers with credit scores between 500 and 579 might still qualify. They will need a higher down payment, usually around 10%.
  2. Down Payment:
    • The minimum down payment for an FHA loan in Kentucky is 3.5% of the home’s purchase price. This is advantageous for buyers who may not have substantial savings for a larger down payment, making homeownership more accessible.
  3. Work History:
    • Lenders typically look for a steady 2 year employment history when considering FHA loan applications. A consistent work history is beneficial. It is preferable to have worked with the same employer or within the same field. This helps demonstrate financial stability and the ability to repay the loan.
  4. Debt-to-Income Ratio (DTI):
    • The debt-to-income ratio is a crucial factor in mortgage approval. For FHA loans, the maximum allowable DTI ratio is typically around 40% to 45% of your gross monthly income. It can go higher up to 56% with good credit scores, a large down payment, or a shorter-term loan. Lenders may also consider higher ratios in certain cases if compensating factors are present.
  5. Bankruptcy and Foreclosure:
    • FHA loans have lenient guidelines regarding bankruptcy and foreclosure. Generally, borrowers with a past bankruptcy may qualify for an FHA loan after two years. This is possible if they have re-established good credit and demonstrated responsible financial behavior. For foreclosures, the waiting period is usually three years.
  6. Mortgage Term:
    • FHA loans offer various mortgage term options, including 15-year, 20 year, 25 year and 30-year fixed-rate loans. The choice of term depends on your financial goals and ability to manage monthly payments.
    • Occupancy: Primary residences with 1-4 units. Not for investment properties or second homes.
    • Mortgage Insurance on the loan for life of loan. Larger down payments and shorter terms will reduce the upfront mi and monthly mi premiums
    • can be used for refinances, not only for purchases.
    • No income limits nor property restrictions on where home is located
    • Can close within 30 days typically with good appraisal and title work

FHA Loan Requirements in Kentucky for Credit scores, Down payment, Debt Ratio and work history below

RequirementDetails
Credit Score– 580+: Eligible for a 3.5% down payment.
– 500-579: Requires a 10% down payment.
Down PaymentMinimum of 3.5% for qualified buyers; 10% for lower credit scores below 580 to 500 score range
Debt-to-Income Ratio (DTI)– Ideal: 45% or lower on front end ratio or housing ratio.
– Acceptable: Up to 57% with compensating factors. There are two ratios. Front end and back end with front end being maxed at 45% and the backed end ratio being 56.99% with an AUS approval. If manually underwritten, see guidelines here
Employment HistoryMust provide at least **2 years of consistent employment—College transcripts can supplement with a less than 2 year work history

Key Benefits of FHA Loans in Kentucky

  1. Low Credit Score Requirements
    • FHA loans accept borrowers with credit scores as low as 500. However, a score of 580+ qualifies you for the lowest down payment option.
  2. Low Down Payment Options
    • You can purchase a home with as little as 3.5% down if you meet credit requirements, making FHA loans more accessible than conventional loans.
  3. Competitive Interest Rates
    • FHA loans typically offer rates comparable to conventional mortgages. They may even offer lower rates. This could save you money over the life of the loan.
  4. Flexible Loan Uses
    • With an FHA 203(k) loan, you can bundle home purchase and renovation costs into a single mortgage.
  5. Assumable Loans
    • FHA loans can be transferred to a new buyer. This feature is especially valuable if you sell your home when interest rates are higher.

Understanding these qualifying criteria can help you navigate the FHA loan application process in Kentucky more effectively. Working with an experienced mortgage professional can provide valuable guidance. They offer assistance tailored to your specific financial situation and homeownership goals.

Joel Lobb  Mortgage Loan Officer

Any questions, please don’t hesitate to reach out via, text, email,  or call.  Advice is always free. 
 
One of Kentucky’s highest rated mortgage loan officers for FHA, VA, USDA, Kentucky Housing KHC and conventional mortgage loans.  
1 – 📅 Email – kentuckyloan@gmail.com 
2.  📞 Call/Text – 502-905-3708
 

Joel Lobb
Mortgage Loan Officer – Expert on Kentucky Mortgage Loans

🌐 Website: www.mylouisvillekentuckymortgage.com
🏢 Address: 10602 Timberwood Cir, Ste 3, Louisville, KY 40223


Evo Mortgage
Company NMLS# 1738461
Personal NMLS# 57916

For assistance with Kentucky mortgage loans, reach out via email, call, or text Joel Lobb directly.

Kentucky Local Home Loan Lender Services

✅ First-Time Home Buyers Welcome
✅ FHA, Rural Housing (USDA), VA, and Kentucky Housing Corporation (KHC) Loans
✅ Conventional Loan Options Available
✅ Fast Local Decision-Making
✅ Experienced Guidance Through the Home Buying Process


NMLS 57916  | Company NMLS #173846
The view and opinions stated on this website belong solely to the authors, and are intended for informational purposes only. The posted information does not guarantee approval, nor does it comprise full underwriting guidelines. This does not represent being part of a government agency. The views expressed on this post are mine and do not necessarily reflect the view of my employer. Not all products or services mentioned on this site may fit all people.
(www.nmlsconsumeraccess.org).
Kentucky First Time Homebuyers FHA, VA, USDA & Rural Housing, KHC and Fannie Mae mortgage loans